Meet The Early Movers In America’s $3T Push For Manufacturing Construction


Manufacturing facilities have broken ground in a burst over the last two years, helped along by incentive programs that span presidencies, with President Donald Trump’s latest rounds of tax breaks passed through the One Big Beautiful Bill Act specifically aimed at unleashing their development. 
There are roughly two dozen facilities under construction across the country totaling around $500B in committed capital, with a deep pipeline of projects behind them, according to Avison Young. The brokerage is tracking 124 projects that have been proposed or announced, amounting to $3.4T in potential investment. 

Avison Young’s lead industrial researcher, Peter Kroner, said he expects the pace of groundbreakings will accelerate through the end of the year.

“We fully anticipate another hockey stick that’s going to dwarf this starting to happen at the end of the year,” Kroner said, describing a steep upward shift in momentum on a line chart that is shaped like the sports equipment. “We’ve peaked in terms of that trough of uncertainty for 18 months, and there’s a lot of excitement from manufacturers to take advantage of what’s in this bill.”

Some of what is breaking ground today is leveraging benefits from former President Joe Biden’s CHIPS and Science Act, but Trump’s One Big Beautiful Bill Act and the ongoing trade war have also driven firms to bring manufacturing stateside.

Biden’s other policy package, the Inflation Reduction Act, has largely been sidelined by the administration that inherited it, but the CHIPS Act has continued to ride the wave of monumental demand for digital infrastructure amid the mass deployment of artificial intelligence, said Craig Van Pelt, who leads research at Cresa.

“The CHIPS Act is a huge deal, one of the biggest financial packages we’ve ever done in the United States, but there’s a long way to go from permitting and site preparation to active construction and production,” he said. 

Republicans’ One Big Beautiful Bill Act added a raft of new incentives to build new factories, not just for chip fabricators but for the broader manufacturing sector. 

Tech dominates the largest projects leveraging the tax incentives today, but pharmaceutical and automotive production round out the top projects that have broken ground. Aerospace is also quickly growing, although at a smaller scale, as drone technology is rapidly developed and as the business of going to space is increasingly privatized by the government and given to companies like SpaceX and Blue Origin.

Most of the projects being built today aren’t the types of operations that involve hundreds of blue-collar workers on production floors. Instead, they rely on advanced robotics to maintain precise production lines, Van Pelt said.

“A lot of the stuff that’s coming back is not traditional manufacturing, but it is more technically advanced manufacturing, which takes a different kind of worker,” he said. “We’re not going to get a bunch of steel workers back here.”

Here is a look at the biggest projects now underway, according to Avison Young.
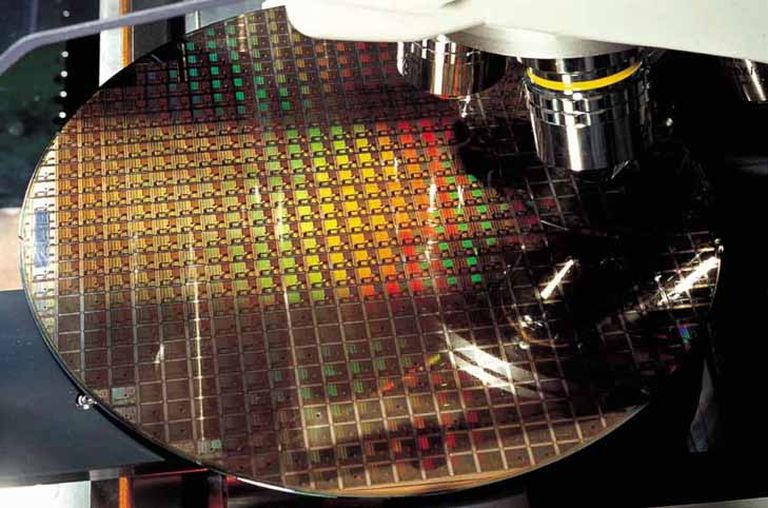
A chip wafer like what will be produced by TSMC in Arizona

TSMC In Arizona

Location: Phoenix
Project Investment: $100B

TSMC, the world’s largest chipmaker, began construction in April 2025 on a third chip fabrication site to complement two existing facilities in Phoenix. The groundbreaking followed a March 2025 announcement expanding the planned facility from a $65B plant to a $165B megasite. This July, TSMC announced plans to invest another $100B in the state, raising its total commitment in Arizona to $265B.

Micron Expands In New York

Location: Clay, New York
Project Investment: $100B

Micron Technology is building a $100B manufacturing plant in central New York that is slated to be the largest semiconductor facility in the U.S. The project officially broke ground in January, and chip production is expected to begin in 2030. 

Micron also pledged $30B in June 2025 to expand chip production facilities in Boise, Idaho, where it is headquartered, and to upgrade a manufacturing facility in Manassas, Virginia. The Idaho commitment was part of a planned $50B campus that would include an additional production facility and a research and development center. In all, the tech giant says it has pledged more than $250B to increase its manufacturing and research presence in the U.S.

Flickr/The White House/Daniel Torok

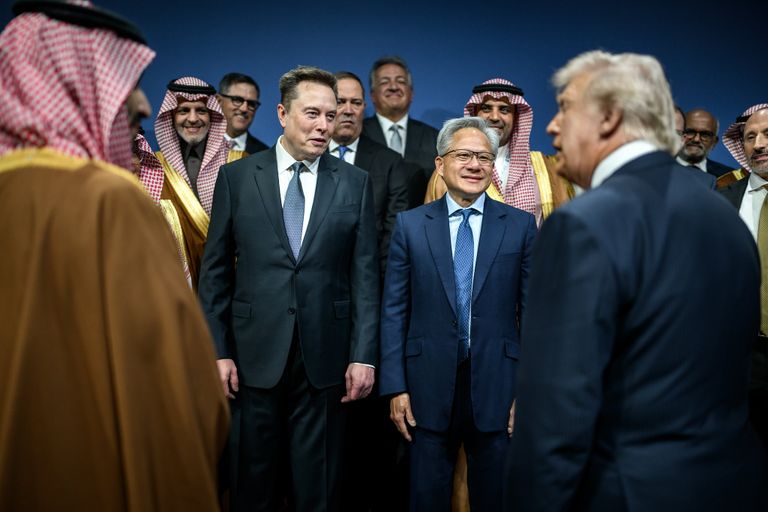
Elon Musk and Nvidia’s Jensen Huang at the U.S.-Saudi Investment Forum in November 2025

Elon Musk’s Terafab

Location: Grimes County, Texas
Project Investment: $16.8B

Elon Musk took to his social media platform in March to announce that xAI, SpaceX and Tesla would build a 100M SF megacampus to produce chips to power his companies’ AI ambitions. The project has a more than $16.8B price tag and a delivery date in 2028, with Gov. Greg Abbott’s office saying the factory will create 3,000 jobs. 

Eli Lilly Picks Texas

Location: Houston
Project Investment: $6.5B

Pharmaceutical giant Eli Lilly waded through more than 300 proposals before selecting a site outside Houston for a $6.5B plant that will manufacture the company’s first oral GLP-1 weight-loss drug and ingredients for other medicines. The project was announced in September 2025 and broke ground a year later. 

The new plant, which is expected to create more than 600 jobs, is one of four Lilly said in 2025 that it would build. The pharmaceutical company later rolled out plans for a $5B plant outside Richmond, Virginia, in September 2025 and announced plans for a $6B production facility in Huntsville, Alabama, in December 2025. Those projects have yet to break ground. 
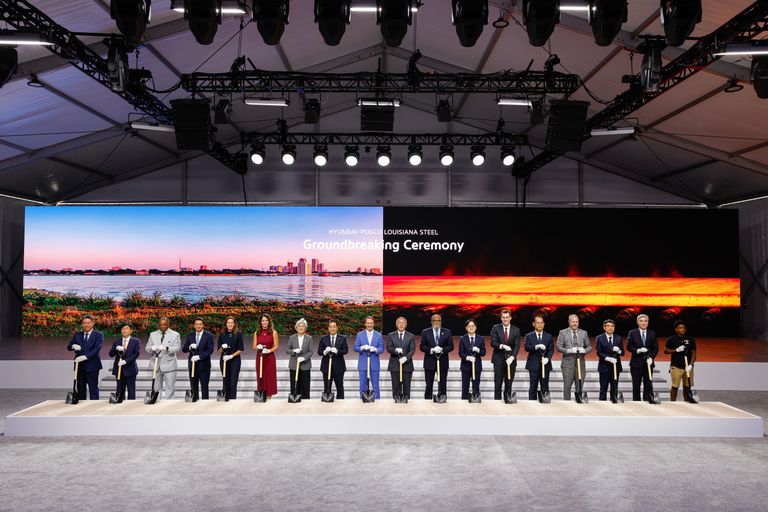
South Korean executives and leading state officials gather in Louisiana for a ceremonial groundbreaking in September.

Hyundai’s American Steel Mill

Location: Donaldsonville, Louisiana
Project Investment: $5.8B

Site work is underway in Donaldsonville, Louisiana, for a 1,700-acre steel mill that Hyundai expects will eventually produce 2.7 million metric tons of steel per year. A ceremonial groundbreaking for the $5.8B facility was held in September, but South Korea-based Hyundai is still working with state officials to secure an air pollution permit before extensive development can get underway, The Advocate reported. The steel mill will support 1,300 direct jobs and is a piece of Hyundai’s pledge from August 2025 to invest $26B into the U.S. by 2028.

Rivian Expands Production

Location: Stanton Springs, Georgia
Project Investment: $5B

Executives from automaker Rivian and political leaders from Georgia, including Gov. Brian Kemp, gathered outside Social Circle, Georgia, in September 2025 for a groundbreaking ceremony for a new manufacturing site that promises to create 7,500 jobs by 2030. The facility was originally expected to be built in two phases, with each phase generating a plant capable of rolling 200,000 cars off the production line annually. 

Rivian shifted plans in April and said the first phase would leverage a $4.5B loan from the Department of Energy — down from the $6.6B allocated under the Biden administration — to complete the first phase of the project, which would have an increased 300,000-unit capacity. The site for the second phase would be reserved for future expansion, Chief Financial Officer Claire McDonough said on the firm’s earnings call, TechCrunch reported.
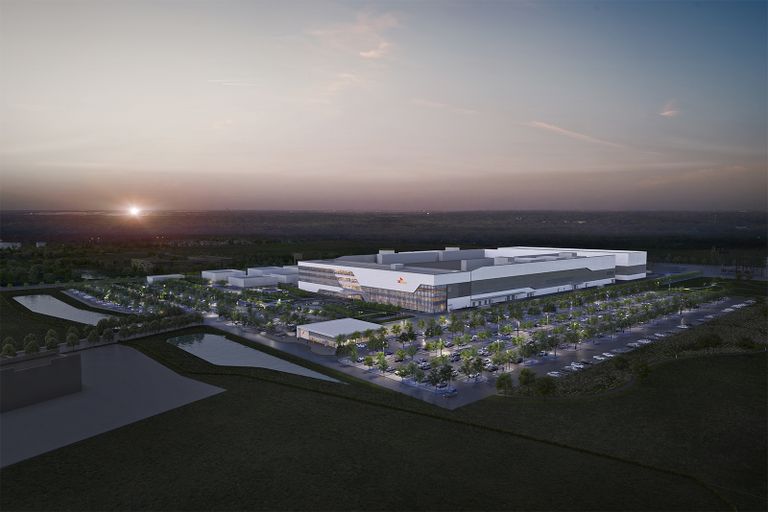
A rendering of SK Hynix’s under-construction advanced memory packaging facility being built in West Lafayette, Indiana

SK Hynix Comes To America

Location: West Lafayette, Indiana 
Project Investment: $4B

Indiana Gov. Mike Braun, Sen. Todd Young, the president of Purdue University, and a host of SK Hynix executives were on hand at the August groundbreaking of a $4B memory packaging hub that will be the South Korean giant’s first manufacturing site in the U.S. The project is expected to create 1,000 jobs and research opportunities through a collaboration with nearby Purdue. The 133-acre site will host a high-bandwidth memory production hub that uses advanced packaging to stack multiple chips on top of one another to optimize size and performance.

Free Training

Source link

SMITH AND FORD Push East-West Energy, Infrastructure and Manufacturing Ties at Calgary Enserva Event – Canadian Energy News, Top Headlines, Commentaries, Features & Events


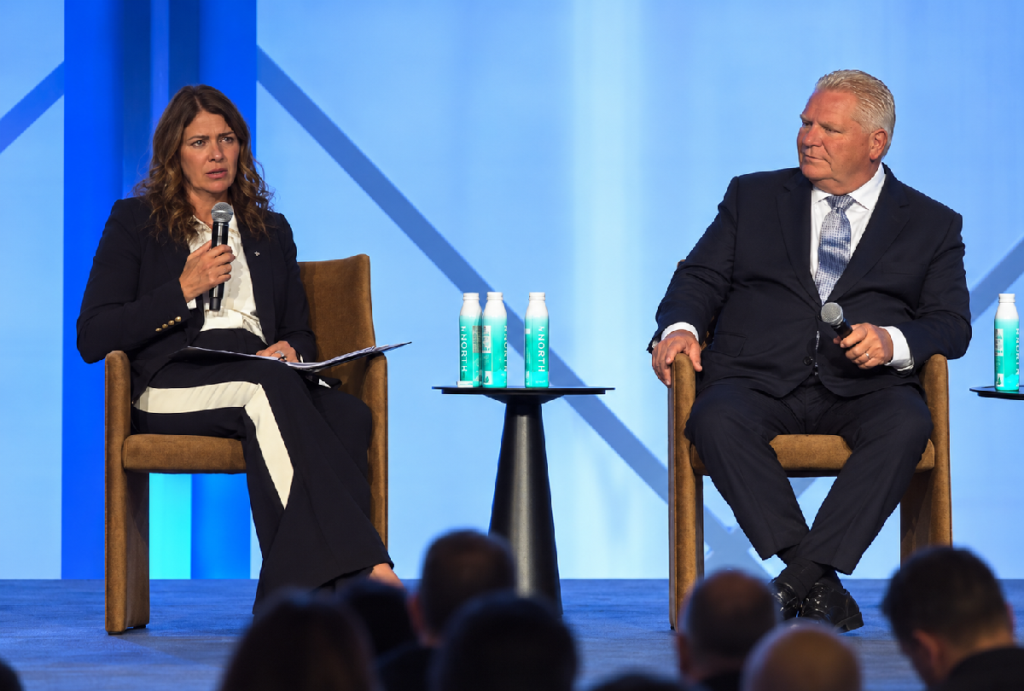
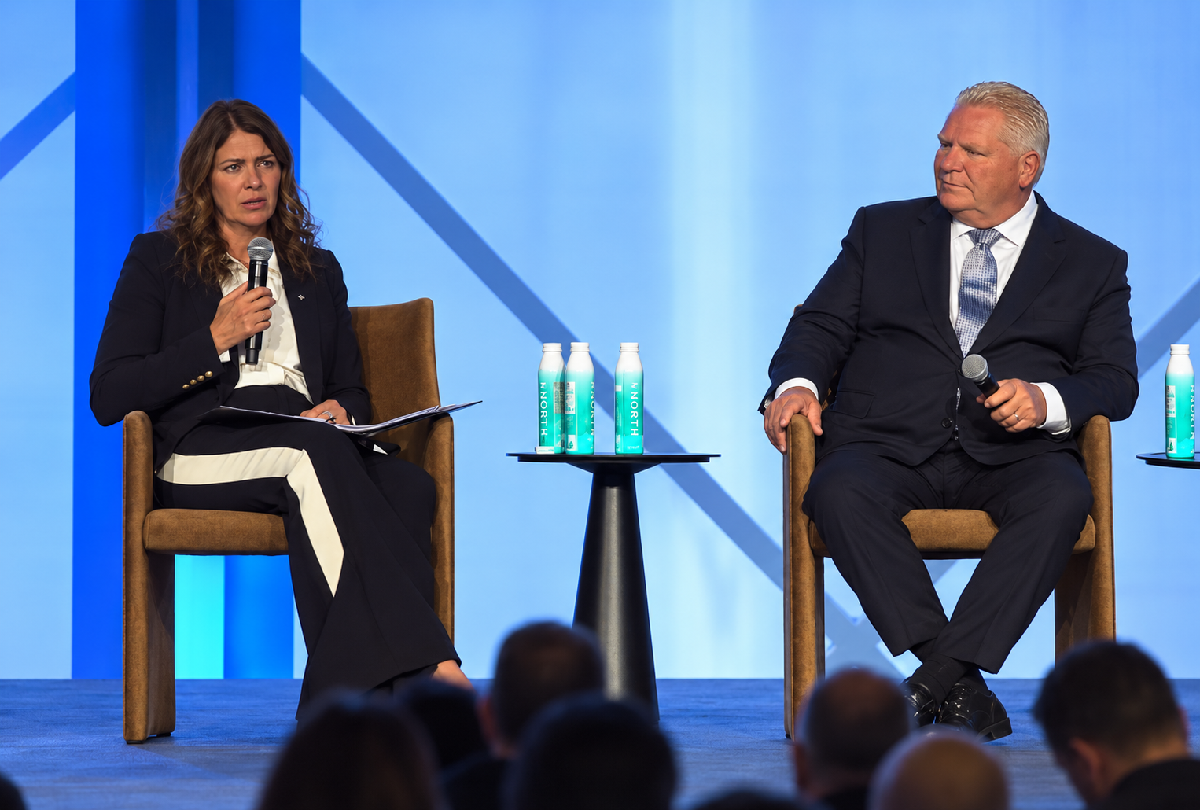
smith ford enserva event 1200x810Premiers Danielle Smith and Doug Ford during a fireside chat hosted by Enserva at the Calgary Telus Convention Centre September 28, 2026 – EnergyNow Media
EnergyNow Media

The two premiers appeared September 28 at the Enserva Speaker Series — Build Canada Stronger: Powering Canada’s Economic Future at the Calgary TELUS Convention Centre. The event brought together energy and business leaders to discuss energy security, infrastructure, trade and Canada’s ability to compete in global markets. It was moderated by Enserva President and CEO Gurpreet Lail. Enserva

The discussion highlighted both areas of agreement and differences between Smith and Ford, particularly on Canada’s evolving relationship with the United States.

Get the Latest Canadian Focused Energy News Delivered to You! It’s FREE: Quick Sign-Up Here

Smith said Alberta’s exposure to U.S. tariffs differs significantly from Ontario’s because most Alberta exports entering the United States are energy products that remain largely tariff-free.

“If you’re looking at a bit of a difference in tone between Premier Ford and I, that’s what it comes down to,” Smith said, pointing to Alberta’s large existing trade relationship with the United States and the role played by cross-border energy companies including Cenovus, TC Energy and Enbridge.

Smith argued that Canada could potentially use energy as the foundation for a broader economic agreement with Washington, suggesting significantly larger volumes of Canadian oil could ultimately move south if a comprehensive Canada-U.S. arrangement were reached.

Ford struck a somewhat different tone but emphasized that he remains strongly supportive of the broader Canada-U.S. relationship.

“I truly love Americans,” Ford said, noting Ontario’s deep economic integration with U.S. manufacturing and trade. He argued for what he called a “Fortress North America” approach in which Canada and the United States strengthen their economic and security relationships while Canada simultaneously expands trade with other countries.

Ford said the current trade friction could ultimately push Canada to become economically stronger.

“He woke us up that we needed to be woken up, and he’s united the country like I’ve never seen before,” Ford said of U.S. President Donald Trump. “We’re going to diversify our trade, but continue building a strong relationship with our closest friends and allies, and that’s the Americans.”

Pipelines Move to Centre Stage

The conversation quickly turned to pipelines and major infrastructure projects — a central theme of the Enserva event, which was promoted around the question of how Canada can build, move and sell more energy to global markets. Enserva

Smith said she has become increasingly confident about the prospects for a proposed new West Coast oil pipeline.

“I’m feeling more and more confident every day that the West Coast oil pipeline is going to potentially even be the first of the projects that go ahead,” she said.

Smith argued that global concerns about supply security have strengthened Canada’s position as a potential long-term supplier to Asian countries seeking greater diversification.

She also pointed to additional export possibilities through the United States and to the proposed Northern Shield corridor, which Alberta and Ontario have been advancing as a potential east-west energy and infrastructure route.

Ford was emphatic that Canada should not be forced to choose between individual pipeline routes.

“We need the West, we need the North, we need the South, and we need to go east,” he said. “Why can’t we do it simultaneously?”

Ford also signalled Ontario’s willingness to participate financially in the Northern Shield concept, saying he evaluates major infrastructure according to its potential return to taxpayers.

“You show me the numbers, and if you can clip those coupons after we get it built every single year, that’s a great investment for our province,” Ford said.

Skilled Labour Could Become the Next Constraint

Both premiers warned that even if governments approve more infrastructure, Canada will need enough skilled workers to actually build it.

Smith pointed to Alberta’s expansion of apprenticeship programs, dual-credit education and partnerships with unions and employers. She said Alberta now has 81,000 apprenticeship positions and argued provinces need greater ability to align immigration with labour-market shortages.

“We need some office jobs, but we sure need a heck of a lot more factory floor jobs and field jobs,” Smith said. Pasted markdown

Ford said Ontario has invested more than $2 billion through its Skills Development Fund and said more than 750,000 people have received training through various programs.

“Number one issue: supply chain and labour. Who is going to fill these jobs?” Ford said, arguing that provinces should have greater influence over immigration programs so workers who have developed needed skills can remain in Canada. Pasted markdown

Alberta Energy Meets Ontario Manufacturing

Perhaps the strongest area of agreement came around creating deeper economic links between Alberta’s energy sector and Ontario’s manufacturing base.

Ford argued governments need to reduce regulatory barriers and create conditions that encourage companies to invest.

“The biggest problem, biggest hurdle is government,” Ford said, pointing to regulation, taxation and permitting as obstacles governments can address. Pasted markdown

Smith then outlined several areas where the provinces could work together directly.

One is natural gas-fired power generation. Alberta wants to substantially expand electricity generation to support industrial growth and data centres, but Smith said global demand for natural gas turbines has created long equipment lead times.

“We’ve got the cheapest natural gas probably anywhere in the world, sitting on an ocean of it,” she said.

Smith suggested Ontario’s manufacturing expertise could help develop a Canadian supply chain for natural gas turbines and related electricity infrastructure.

Another opportunity is steel.

With pipelines, energy projects and other infrastructure requiring enormous volumes of steel pipe and fabricated components, Smith said Alberta should identify the equipment its energy industry will need and work with Ontario manufacturers to produce more of it domestically.

“Let’s figure out how we can identify the steel fabricated items that we need, and let’s work with our friends in Ontario,” Smith said.

She also suggested Canada needs stronger east-west supply chains, rather than relying predominantly on north-south trade with the United States or imported products arriving through West Coast ports. Pasted markdown

The message fit closely with the theme Enserva established for the event. Using Canadian energy, infrastructure and industrial partnerships to improve the country’s economic competitiveness and energy security. Enserva said the discussion was intended to examine how Canada could “look beyond provincial boundaries” to unlock its energy potential.

For Canada’s energy services sector, the discussion underscored a potentially significant shift: major energy development is increasingly being presented not simply as a Western Canadian issue, but as an opportunity to connect Alberta resources, Ontario manufacturing, Canadian workers and new international markets.

And on that central point, Smith and Ford were clearly aligned.

“We’re stronger together,” Ford said.

Free Training

Source link

Marine boots fail in the Arctic amid push for US manufacturing: Report


A new report revealing quality-control issues with Marine Corps-issued cold-weather boots highlights the potential consequences of limiting the number of suppliers for essential gear.

According to a new report by Newsweek, an unspecified number of Marines had to have their brand-new boots replaced during cold-weather training ahead of a Norwegian-led NATO exercise earlier this year.

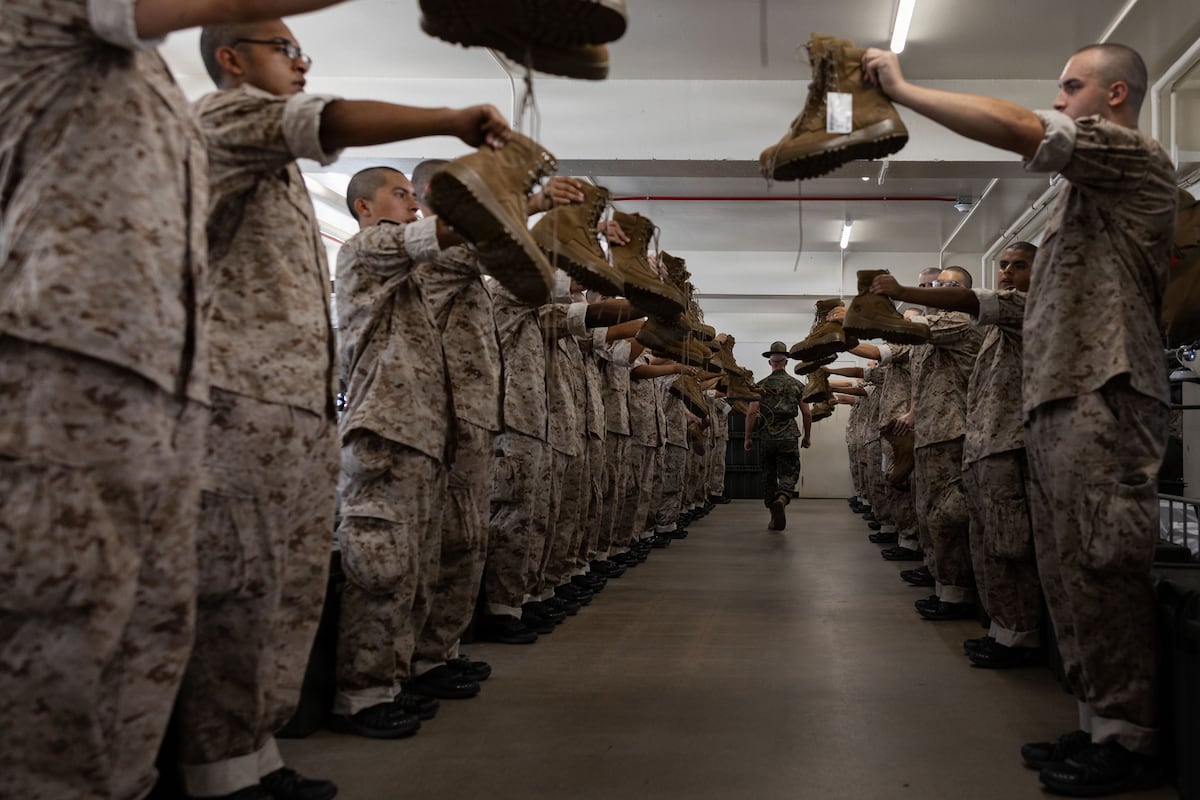
Marines reportedly wore holes through the boots’ leather and saw the soles separate from the fabric, allowing freezing water to seep into the boots as they hiked and skied.

The issue, according to the report, stems from a legal requirement that the Pentagon use its funds to buy American-made boots.

Although the intent behind the federal law is to support U.S. companies, the domestic industry is too small to meet demand, which can create problems with product quality and price.

Troops can currently wear non-American-made boots if they purchase them on their own. That standard could change, however, as federal lawmakers consider the Better Outfitting Our Troops, or BOOTS, Act.

The measure would prohibit service members from wearing optional combat boots in uniform unless they were manufactured entirely in the U.S.

Critics of the measure, like the Cato Institute, say the BOOTS Act “would deny service members the ability to find boots that best fit their feet so U.S. manufacturers can make a few extra bucks.”

The libertarian think tank argued that the primary force behind the measure is an “aggressive lobby” working on behalf of an industry rather than “the warfighter.”

Cato listed the United States Footwear Manufacturers Association, or USFMA, as the leading lobbyist group behind the BOOT Act. The organization represents a variety of footwear companies, including Belleville Boot Company, which manufactured the boot in question.

A Pentagon official told Newsweek that expanding the domestic boot industry would not necessarily be a bad thing. But scaling up production while maintaining existing quality standards could prove difficult for manufacturers.

Daniel Terrill is a contributor to Military Times. He’s been reporting on military issues, the gun industry, and the outdoors for nearly two decades. Although writing is his passion, he’s been a Marine, police officer, and, perhaps the most dangerous job of his career, a substitute teacher.

Free Training

Source link

First Solar (FSLR) Details Its US Manufacturing Push In New Responsibility Report


  • First Solar released its 2026 Corporate Responsibility Report, outlining progress on domestic manufacturing expansion and R&D investment.
  • The report highlights First Solar’s end to end control of its US based production and supply chain transparency.
  • It also details sizable US capital spending and job creation as the company responds to heavily subsidized overseas competitors.

First Solar, traded as NasdaqGS:FSLR, is using this new report to explain how its US focused manufacturing footprint fits into the broader solar industry. The stock closed at $206.01, with a return of 17.9% over the past year and 124.9% over the past five years. Those figures help frame how investors might weigh this disclosure alongside past performance.

The company’s emphasis on vertically integrated, US based production and ongoing R&D spend gives investors a clearer view of how it is trying to build resilience around technology and supply chain control. This update also arrives at a time when US solar policy and support for domestic manufacturing remain important variables for the sector. Investors can use this report to refine their view of First Solar’s long term positioning in a contested global market.

Stay updated on the most important news stories for First Solar by adding it to your watchlist or portfolio. Alternatively, explore our Community to discover new perspectives on First Solar.

NasdaqGS:FSLR Earnings & Revenue Growth as at Jul 2026NasdaqGS:FSLR Earnings & Revenue Growth as at Jul 2026

4 things going right for First Solar that this headline doesn’t cover.

For First Solar, this 2026 Corporate Responsibility Report reads like a business update as much as a sustainability document. The company is linking its domestic manufacturing build out, end to end control of production, and US focused capital spending to how it thinks it can compete against heavily subsidized exporters such as LONGi, JinkoSolar, and other Asian manufacturers. Investors also have fresh hard numbers to anchor that story. For the second quarter of 2026, First Solar reported US$1,056.19m of sales and US$422.57m of net income, with earnings per share above the prior year. For the first half, sales were US$2,100.43m and net income was US$769.19m. Management also reaffirmed 2026 guidance and expects third quarter 2026 module sales of 3.9 GW to 4.5 GW, with the bulk from US facilities. Put together, the report suggests that the push into US manufacturing, backed by sizable capital spending and R&D, is not just a policy story. It is already tied into current profitability and volume expectations that investors can monitor from quarter to quarter.

How This Fits Into The First Solar Narrative

  • The report underlines a key narrative catalyst, namely that US centered manufacturing and policy support can support demand and pricing for First Solar’s modules by reducing exposure to foreign supply chains affected by tariffs.
  • It also highlights a risk already flagged in the narrative, specifically that heavy reliance on US incentives and trade rules leaves First Solar exposed if policies, tariffs, or domestic content rules change over time.
  • The scale of capital spending, job creation, and detailed supply chain transparency outlined in the report may not be fully captured in previous narrative assumptions about execution capacity and operating complexity.

Knowing what a company is worth starts with understanding its story.
Check out one of the top narratives in the Simply Wall St Community for First Solar to help decide what it’s worth to you.

The Risks and Rewards Investors Should Consider

  • ⚠️ Concentration on US policy support, including tariffs and tax credits, creates the risk that changes in legislation or enforcement could affect First Solar’s margins and demand for its domestically produced modules.
  • ⚠️ Competing against low cost Chinese and other Asian manufacturers, whose capacity has been flagged as large enough to supply global demand for years, may keep pricing pressure high even with a differentiated US footprint.
  • 🎁 The latest report, together with the second quarter and first half 2026 results, shows that First Solar is currently generating solid profitability while expanding domestic capacity and investing in R&D.
  • 🎁 Analysts have highlighted 4 key rewards, including past earnings growth and expectations for future earnings growth, which some investors may see as supporting the case for continued interest in the stock.

What To Watch Going Forward

After this report, focus on how First Solar converts its projected US manufacturing output into sustained module sales within the guided 3.9 GW to 4.5 GW range and beyond. Track whether future quarters keep pairing sizable US capital spending and R&D with healthy net income, as seen in the second quarter and first half of 2026. Policy remains central. Any updates to US tariffs, tax credits or domestic content rules will feed directly into the economics of its end to end US supply chain. Competitive responses from peers such as LONGi and JinkoSolar, including pricing and new technologies, also matter for assessing how differentiated First Solar’s model really is over time.

To ensure you’re always in the loop on how the latest news impacts the investment narrative for First Solar, head to the community page for First Solar to never miss an update on the top community narratives.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: AI Stock Screener & Alerts

Our new AI Stock Screener scans the market every day to uncover opportunities.

• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies

Or build your own from over 50 metrics.

Explore Now for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

Indiana manufacturing push and acquisition drive keep focus on


Eli Lilly & Co. shares on the NYSE traded above USD 1,060 on 06/03/2026 as the United States-based pharma group steps up a multibillion-dollar manufacturing expansion in Indiana and signals a more aggressive acquisition strategy for its drug pipeline.

Eli Lilly & Co. shares remain in focus on the New York Stock Exchange as investors digest the latest signals on the United States company’s capital deployment, combining large-scale manufacturing investments in Indiana with an expanded acquisition strategy to bolster its portfolio of innovative medicines. The stock traded around USD 1,064 on 06/03/2026 on the NYSE under the ticker LLY, according to data cited by GuruFocus as of 06/03/2026, keeping the United States blue chip firmly among the largest healthcare names by market capitalization.

The Indianapolis-based group has been pushing ahead with a sizable expansion of its domestic production base. According to an article published by Manufacturing in Focus on 06/2026, Eli Lilly is topping out its Indiana investment by allocating an additional USD 4.5 billion to its manufacturing footprint in the state, building on earlier commitments to facilities including its LEAP Research and Innovation District near Indianapolis. The report highlights that the expansion is intended to support growing demand for the company’s diabetes and obesity treatments and other biologic therapies, while anchoring high-value pharmaceutical manufacturing in the United States.

Parallel to this capital expenditure program, management has also been signaling a more assertive approach to business development. On 06/03/2026, GuruFocus reported that Eli Lilly’s oncology dealmaker Jacob Van Naarden is leading a significant ramp-up in acquisitions, with more than USD 10 billion of deals already announced in 2026 to acquire or partner with smaller biotech innovators. The article notes that across eight transactions this year, the company has committed over USD 10 billion upfront and potentially up to USD 25 billion when including milestone payments, as it targets cutting-edge assets in oncology and other high-growth therapeutic areas.

The same GuruFocus analysis calculates a proprietary GF Value of USD 1,388.64 per share for Eli Lilly as of 06/03/2026 versus a contemporaneous share price of about USD 1,064.15, implying the stock was trading at roughly a 23.4 percent discount to that intrinsic value estimate. While this is not a market consensus, it illustrates how one valuation framework interprets the company’s growth trajectory, pipeline prospects, and balance sheet strength at the current trading level on the NYSE. For German investors accessing the stock via off-exchange platforms, Eli Lilly is also tradeable on venues such as Tradegate in euros, although liquidity and reference pricing remain centered on the US listing.

Interest from institutional investors continues to underpin trading in the United States. According to a MarketBeat filing summary dated 06/03/2026, Westpac Banking Corp increased its position in Eli Lilly by 39.5 percent in the fourth quarter, purchasing 4,030 additional shares and bringing its total holdings to 14,235 shares. The disclosure underscores how large global asset managers are still adding exposure to the group, with the same MarketBeat overview citing a consensus rating of “Moderate Buy” and an average price target of USD 1,227 among covering analysts as of the latest data. These figures provide a snapshot of how the sell side is framing upside and risk for the stock at current levels.

The combination of escalation in US-based manufacturing investment and heightened acquisition activity is central to how the market evaluates Eli Lilly’s growth case. Investors are paying close attention to whether the expanded Indiana production network will effectively support supply for high-demand medicines, and how quickly newly acquired pipeline assets can be integrated and advanced through clinical trials and regulatory review. With the company’s primary listing and regulatory reporting anchored in the United States, updates via NYSE trading data and SEC filings will remain key reference points for both domestic and international shareholders following the stock.

As of: 06/03/2026

By the editorial team – specialized in equity coverage.

At a glance

  • Name: Eli Lilly & Co.
  • Sector/industry: Pharmaceuticals and biotechnology
  • Headquarters/country: Indianapolis, United States
  • Core markets: United States, Europe, key international pharmaceutical markets
  • Key revenue drivers: Diabetes and obesity therapies, immunology and oncology drugs, other specialty pharmaceuticals
  • Home exchange/listing venue: New York Stock Exchange (LLY)
  • Trading currency: USD

Eli Lilly & Co.: core business model

Eli Lilly focuses on discovering, developing, and commercializing branded prescription medicines, with revenue concentrated in chronic disease areas such as diabetes, obesity, immunology, and oncology that can support long product lifecycles and premium pricing.

Eli Lilly & Co. in peer comparison

In the global large-cap pharmaceutical space, Eli Lilly is often assessed alongside peers such as Novo Nordisk, Pfizer, and Johnson & Johnson, which likewise operate diversified portfolios of patented therapies and vaccines. Novo Nordisk, for example, has also invested heavily in obesity and diabetes medicines and reached a market capitalization above USD 500 billion in early 2026 on the back of demand for GLP-1-based treatments, underlining the scale of the metabolic disease opportunity for sector leaders. Pfizer, by contrast, has been reallocating cash flows from its COVID-19 franchise into pipeline rebuilds and bolt-on acquisitions, while Johnson & Johnson maintains a more diversified business that includes medical devices and consumer health in addition to pharmaceuticals.

Compared with these peers, Eli Lilly’s current strategy of combining substantial US manufacturing commitments in Indiana with an enlarged acquisition budget exceeding USD 10 billion in 2026 places it toward the more aggressive end of the spectrum in terms of reinvesting cash into long-term growth initiatives. Investors monitoring the stock on the NYSE and in European trading are therefore weighing similar questions across the peer group: how quickly new metabolic and oncology products can be scaled, how effectively supply chains can keep pace with demand, and whether the balance between shareholder returns and reinvestment supports sustainable earnings growth.

Sentiment and reactions on Eli Lilly & Co.

The combination of expanded Indiana manufacturing investment and a more active acquisition pipeline has sparked ongoing discussion among market participants on social platforms about how these moves might influence Eli Lilly & Co.’s long-term earnings power and valuation.

YouTubeXTikTokInstagram

Conclusion

Eli Lilly & Co. remains a closely watched United States healthcare stock, with its NYSE-listed shares trading just above USD 1,060 on 06/03/2026 as the group deploys capital into an expanded Indiana manufacturing footprint and a stepped-up acquisition agenda. The latest reports on more than USD 10 billion of 2026 dealmaking and an additional USD 4.5 billion in state-side plant investment highlight the company’s decision to prioritize future capacity and pipeline breadth alongside ongoing shareholder returns.

For investors comparing Eli Lilly & Co. with global pharma peers such as Novo Nordisk, Pfizer, and Johnson & Johnson, the current strategy underscores a distinct emphasis on scaling high-demand metabolic and oncology therapies through both organic infrastructure builds and external innovation sourcing. How effectively these initiatives translate into sustained revenue and earnings growth over the medium term will remain central to how the stock is valued on the New York Stock Exchange and in secondary trading venues worldwide.

Disclaimer: This article does not constitute investment advice. The comprehensive scope of this informative article was made possible through the use of a.i.. Stocks are volatile financial instruments.


en | US5324571083 | ELI LILLY & CO. | boerse | 69478848 | bgmi


Free Training

Source link

Toyota Plans $2bn Texas Expansion as Automakers Deepen North American Manufacturing Push


Toyota Plans $2bn Texas Expansion as Automakers Deepen North American Manufacturing Push

Toyota Motor Corporation is seeking approval to build a new vehicle assembly line at its manufacturing complex in Texas as the Japanese automaker accelerates long-term investment in North American production amid intensifying competition in trucks, electric vehicles, and regional supply-chain localization.

According to a filing with the Texas Comptroller of Public Accounts, Toyota plans to invest roughly $2 billion in the proposed expansion project, internally named “Project Orca,” at its existing San Antonio manufacturing site. The filing shows construction is expected to begin by the end of 2026, while vehicle production at the new assembly line is targeted to commence in 2030.

Toyota plans to spend approximately $1.05 billion on buildings and property improvements, alongside another $950 million dedicated to machinery and manufacturing equipment. The project is also expected to create about 2,000 new jobs between 2028 and 2030, adding to Toyota’s already substantial employment footprint in Texas and reinforcing the growing importance of the southern United States in the global automotive industry.

In a statement to Reuters, Toyota said, “We regularly evaluate our manufacturing footprint to ensure we remain competitive and aligned with customer demand. This reflects our long-term commitment to investing in the North American region, local manufacturing/jobs, and suppliers.”

Toyota’s San Antonio facility has historically focused heavily on pickup truck production, including the Toyota Tundra and Toyota Sequoia, two models central to the company’s efforts to compete in the highly profitable North American truck and SUV market. The new assembly line could significantly expand Toyota’s ability to serve U.S. demand locally at a time when automakers are under growing pressure to shorten supply chains and reduce exposure to overseas manufacturing risks.

Texas has become increasingly attractive to automakers and industrial manufacturers because of its large labor market, logistics infrastructure, relatively lower operating costs, and business-friendly regulatory environment. The state is also emerging as a major center for energy-intensive industries, including electric vehicles, semiconductors, and artificial intelligence data centers.

Toyota’s investment adds to a broader wave of manufacturing expansion across the southern United States, where automakers are pouring billions into new factories, battery plants, and supplier networks. The region has become particularly important as companies attempt to comply with North American sourcing requirements tied to trade incentives and industrial policies in both the United States and Canada.

The timing of Toyota’s proposed expansion is notable because it comes during one of the most significant transitions in automotive history. The industry is simultaneously managing the shift toward electrification, the rise of software-defined vehicles, growing competition from Chinese manufacturers, and changing consumer demand patterns.

While Toyota was initially criticized by some investors and environmental groups for moving more cautiously on fully electric vehicles than rivals such as Tesla or BYD, the company has increasingly accelerated investment across hybrid, battery-electric, and hydrogen technologies.

At the same time, Toyota has maintained a strong focus on profitability and production discipline, particularly in trucks and hybrid vehicles, where demand remains resilient. The company’s continued investment in U.S. manufacturing suggests it expects North America to remain one of its most important long-term growth markets regardless of how rapidly electrification evolves.

Industry analysts believe that local manufacturing has become strategically more important for automakers following the supply-chain shocks triggered by the COVID-19 pandemic and geopolitical tensions between the United States and China. Semiconductor shortages, shipping disruptions, and rising trade frictions exposed vulnerabilities in globally dispersed production networks, pushing many manufacturers to localize more operations closer to major consumer markets.

Toyota’s Texas expansion fits squarely within that broader industrial realignment.

The planned investment also reflects the enormous capital requirements now confronting global automakers. Companies are simultaneously funding traditional internal combustion production, electric vehicle development, battery manufacturing, software systems, and advanced automation technologies.

For Toyota, maintaining a competitive scale in North America is especially important because the region remains one of the company’s largest profit generators, particularly in larger vehicles and hybrid models.

The proposed spending on machinery and equipment indicates the new line could incorporate significant automation and advanced manufacturing technologies designed to improve efficiency and production flexibility.

Modern vehicle plants increasingly rely on robotics, AI-assisted quality systems, and digitally integrated supply-chain management tools to manage rising production complexity.

Toyota has historically been regarded as one of the world’s leading manufacturing companies through its “Toyota Production System,” which revolutionized lean manufacturing and operational efficiency across the global auto industry. The San Antonio expansion, therefore, likely represents not just additional capacity, but also another phase in Toyota’s modernization of North American operations.

Like this:

Like Loading…


Free Training

Source link

U.S. manufacturing push and Q1 2026 results in focus


Amgen Inc. has announced a fresh $300 million U.S. manufacturing investment and reported first?quarter 2026 financial results, highlighting growth in product sales and margins.

Amgen Inc. has moved into the spotlight after announcing an additional $300 million investment in its U.S. manufacturing network and releasing its first?quarter 2026 financial results. The new capital commitment brings the company’s total U.S. manufacturing outlay over the past year to nearly $2 billion, underscoring its focus on domestic capacity and next?generation biologics production. At the same time, Amgen’s latest quarterly figures show continued revenue growth and solid profitability, reinforcing its position as a leading biotech player for U.S. investors.

According to a press release dated May 4, 2026, Amgen plans to allocate the $300 million to expand and modernize its U.S. manufacturing footprint, including advanced technologies and supply?chain resilience for key medicines. The company emphasized that the investment will support a reliable supply of therapies for patients and align with broader U.S. policy goals around onshoring critical drug production. PR Newswire as of May 4, 2026

On the financial side, Amgen reported first?quarter 2026 results on April 24, 2026, with product sales and overall revenue trending higher year?over?year. Earlier filings and third?party summaries indicate that the company’s quarterly revenue rose about 5.8% versus the same quarter of the prior year, while net margin and return on equity remained strong, reflecting disciplined cost management and pricing power in its core franchises. Stock Titan as of April 24, 2026

As of: 09.05.2026

By the editorial team – specialized in equity coverage.

At a glance

  • Name: Amgen Inc.
  • Sector/industry: Biotechnology / Pharmaceuticals
  • Headquarters/country: Thousand Oaks, California, United States
  • Core markets: United States, Europe, Japan and other developed markets
  • Key revenue drivers: Oncology, cardiovascular, inflammation and bone health franchises
  • Home exchange/listing venue: Nasdaq (ticker: AMGN)
  • Trading currency: U.S. dollar

Amgen Inc.: core business model

Amgen Inc. operates as a global biotechnology company focused on discovering, developing and commercializing innovative human therapeutics. The firm’s business model centers on proprietary biologic platforms and a diversified portfolio of marketed medicines, primarily in oncology, cardiovascular disease, inflammation and bone health. By investing heavily in research and development, Amgen aims to extend the lifecycle of existing products while advancing a pipeline of novel candidates that can address unmet medical needs.

Amgen’s strategy combines internal R&D with targeted acquisitions and collaborations, allowing it to broaden its therapeutic footprint without over?relying on any single indication. The company markets its products through a global commercial infrastructure, with a particularly strong presence in the United States, where it benefits from favorable reimbursement dynamics and a large patient base. This U.S.?centric exposure makes Amgen a relevant name for American retail investors seeking exposure to the biotech sector.

Main revenue and product drivers for Amgen Inc.

Amgen’s revenue is driven by a portfolio of established biologic brands, including therapies for cancer, cardiovascular risk reduction, inflammatory conditions and osteoporosis. These products typically command premium pricing and benefit from long?term treatment regimens, which support recurring sales and relatively predictable cash flows. Recent quarterly filings indicate that product sales have grown steadily, with total revenues rising to about $9.56 billion in the third quarter of 2025 from $8.50 billion a year earlier, reflecting both volume growth and favorable pricing dynamics. Stock Titan as of November 4, 2025

Within this portfolio, oncology and cardiovascular franchises have been key growth engines, supported by label expansions and new indications. Amgen’s ability to maintain high net margins and strong return on equity suggests effective cost control and pricing power, even as the company continues to invest in R&D and manufacturing. The additional $300 million U.S. manufacturing investment announced in May 2026 is expected to further strengthen supply reliability and operational efficiency, which can help protect margins and support long?term revenue growth.

Conclusion

Amgen Inc. is drawing attention from U.S. investors following a fresh $300 million U.S. manufacturing investment and solid first?quarter 2026 financial results. The company’s focus on expanding domestic production capacity aligns with broader policy trends and may enhance supply reliability for its key medicines. At the same time, continued revenue growth and strong profitability metrics suggest that Amgen’s core franchises remain resilient in a competitive biotech landscape.

For U.S. retail investors, Amgen offers exposure to a diversified biotech portfolio with significant domestic sales and a track record of disciplined capital allocation. However, the stock remains sensitive to regulatory developments, pricing pressures and pipeline execution, which can influence both near?term performance and long?term growth prospects. As with any equity, investors should weigh these factors carefully and consider their own risk tolerance before making decisions.

Disclaimer: This article does not constitute investment advice. Stocks are volatile financial instruments.


en | US0311621009 | AMGEN INC. | boerse | 69298087 | bgmi

Free Training

Source link

Walmart’s AI Push Links Gemini App Experience With U.S. Manufacturing Shift


  • Walmart (NasdaqGS:WMT) is expanding its partnership with Google to integrate Gemini AI into the Walmart mobile app, aiming to support instant checkout and more personalized shopping.
  • The company is also backing Unspun’s AI driven textile production initiative in the U.S., targeting more domestic, tech enabled apparel manufacturing.
  • These moves come alongside Walmart’s broader shift toward platform style profit streams and more advanced, sustainable supply chains.

For investors watching Walmart (NasdaqGS:WMT), these AI and manufacturing moves sit on top of a share price of $126.787 and a 1 year return of 37.8%. Returns over 3 and 5 years are very large, with shares up 165.2% and 188.9% respectively. This underlines how closely the market is tracking Walmart’s repositioning beyond traditional retail margins.

The Gemini AI rollout and Unspun partnership point to Walmart tying digital engagement more tightly to how products are sourced and produced. For you as a shareholder or potential investor, the key question is how these projects influence customer loyalty, cost structure and the mix of higher margin, platform like revenue over time.

Stay updated on the most important news stories for Walmart by adding it to your watchlist or portfolio. Alternatively, explore our Community to discover new perspectives on Walmart.

NasdaqGS:WMT Earnings & Revenue Growth as at Apr 2026NasdaqGS:WMT Earnings & Revenue Growth as at Apr 2026

📰 Beyond the headline: 1 risk and 2 things going right for Walmart that every investor should see.

Quick Assessment

  • ⚖️ Price vs Analyst Target: At US$126.79, Walmart trades about 7% below the US$136.02 analyst target, which sits inside a wide US$62 to US$150 range.
  • ⚖️ Simply Wall St Valuation: The shares are described as trading close to estimated fair value, so this AI and manufacturing news comes against a roughly balanced valuation backdrop.
  • ✅ Recent Momentum: A 30 day return of 2.67% suggests the trend has been slightly positive into this announcement.

There is only one way to know the right time to buy, sell or hold Walmart: head to Simply Wall St’s
company report for the latest analysis of Walmart’s Fair Value.

Key Considerations

  • 📊 Gemini AI in the app and AI led U.S. textile production both speak to Walmart tying digital retail, data and supply chain control more tightly together.
  • 📊 Watch how engagement metrics, unit economics in fulfillment and any disclosure around AI driven productivity show up alongside the current 46.2x P/E.
  • ⚠️ One flagged risk is significant insider selling over the past 3 months, which some investors may weigh against these long term tech and manufacturing projects.

Dig Deeper

For the full picture including more risks and rewards, check out the
complete Walmart analysis. Alternatively, you can check out the
community page for Walmart to see how other investors believe this latest news will impact the company’s narrative.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

Valuation is complex, but we’re here to simplify it.

Discover if Walmart might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.

Access Free Analysis

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

Tesla (TSLA) reportedly in talks to buy $2.9B in Chinese solar equipment for 100 GW US push


FERC July 2025
Image: Tesla

Elon Musk’s plan to build 100 GW of solar manufacturing capacity in the United States just got its first major price tag: $2.9 billion in equipment from Chinese suppliers, according to a Reuters exclusive.

If the deal closes, it marks the biggest concrete investment yet in Musk’s solar ambitions, and a stunning reversal for a company that effectively abandoned its solar business just two years ago.

The deal

Reuters reports that the equipment is valued at roughly 20 billion yuan ($2.9 billion) and that Tesla is in discussions with multiple Chinese suppliers. The frontrunner is Suzhou Maxwell Technologies, a Shenzhen-listed company that dominates the global market for solar cell screen-printing production lines.

Other potential suppliers include Shenzhen S.C New Energy Technology and Laplace Renewable Energy Technology.

Advertisement – scroll for more content

The Chinese companies have been told to deliver the equipment before this autumn, with at least two sources indicating it would be shipped to Texas. That aligns with Tesla’s expanding Texas manufacturing footprint, which already includes its Austin Gigafactory and a new Houston Megafactory under construction for Megapack production.

One significant hurdle remains: Suzhou Maxwell needs export approval from China’s commerce ministry, and it’s unclear how quickly that clearance will come. Beijing has been tightening its grip on solar technology exports over the past two years, and China’s commerce ministry recently made export controls a top priority for 2026.

On the US side, the equipment faces a more favorable regulatory path. Solar manufacturing equipment was excluded from Section 301 tariffs in 2024 at the urging of American solar panel makers, and that exemption has been extended by the Trump administration through November 2026.

The 100 GW ambition

The $2.9 billion equipment purchase is tied directly to a goal Musk laid out at the World Economic Forum in Davos in January 2026. There, he announced that both Tesla and SpaceX are independently working to build 100 GW per year of solar manufacturing capacity in the US — covering the entire supply chain from raw materials to finished panels.

The company’s own job listings reinforce the scale of the ambition, explicitly referencing a target of 100 GW of “solar manufacturing from raw materials on American soil before the end of 2028.”

For context, total US solar installations in 2023 reached about 32 GW. Tesla wants to manufacture more than three times that, every single year, on its own.

The driving force behind the urgency isn’t climate policy, it’s AI. Data center construction and the broader electrification of transportation pushed US power consumption to a second consecutive record in 2025, and the projections keep rising. Musk has argued that no other energy source can scale fast enough or cheaply enough to meet those demands.

Tesla’s troubled solar history

The irony is thick. Tesla acquired SolarCity for $2.6 billion in 2016 and promised to revolutionize the residential solar market with its Solar Roof tiles. Musk set a target of 1,000 new solar roofs per week by the end of 2019. Tesla never came close. By Q2 2022, the company was deploying approximately 23 roofs per week — roughly 2% of the target.

Today, Tesla never talks about its solar roof; it’s essentially a dead product.

Tesla’s solar deployment declined steadily after the SolarCity acquisition. Panasonic, which had partnered with Tesla at the Buffalo Gigafactory to manufacture solar cells, exited the facility in 2020. By late 2024, Tesla stopped reporting solar deployment altogether, and the word “solar” didn’t appear once during the company’s Q3 2024 earnings call.

There were signs of a revival in early 2026 when Tesla launched a new US-made solar panel (the TSP-420) assembled at the Buffalo factory, featuring a proprietary 18-zone power optimization system. But the scale was modest — initial capacity at the Buffalo facility was just over 300 MW per year, a rounding error compared to the 100 GW target.

Energy storage is a different story

While Tesla’s solar business withered, its energy storage division exploded. Tesla deployed a record 46.7 GWh of energy storage in 2025, a 48% increase year-over-year, generating $12.8 billion in revenue with a 29.8% gross margin — nearly double what Tesla earns selling cars.

Energy storage now accounts for 13% of Tesla’s total revenue and 23% of its gross profit. The Lathrop Megafactory in California produces Megapacks at its full planned capacity of 40 GWh per year, and the new Houston facility targets 50 GWh of annual output by end of 2026.

The solar manufacturing push would complement this storage infrastructure — Tesla could theoretically pair its own solar panels with Megapacks and Powerwalls for integrated energy solutions, and potentially use the output to power its own operations and even SpaceX satellites.

Electrek’s Take

We’ve been tracking Tesla’s solar journey since the SolarCity acquisition, and the trajectory has been one of consistent underdelivery. The Solar Roof never materialized at scale. Solar deployments cratered. The entire solar business segment became an afterthought as energy storage consumed all of Tesla’s energy division attention.

So when Musk announced a 100 GW solar manufacturing target at Davos, our first instinct was skepticism — and it still is. Going from roughly 300 MW of annual solar panel capacity at the Buffalo factory to 100 GW is a staggering 300x increase, on a timeline of less than three years.

That said, the $2.9 billion equipment purchase suggests this isn’t just talk. That’s real capital being deployed (or at least negotiated), and the autumn delivery deadline for equipment in Texas suggests Tesla intends to move fast. The company also has genuine tailwinds: the tariff exemption on solar manufacturing equipment, surging electricity demand from AI data centers, and a proven energy division that can integrate solar with its storage products.

The biggest risks are execution, Tesla’s solar track record is dismal, and the Chinese export approval, which Beijing could use as leverage in the ongoing trade tensions. We’ll believe the 100 GW target when we see equipment on the ground and production lines running.


Add Electrek as a preferred source on Google

FTC: We use income earning auto affiliate links. More.

Free Training

Source link

Is CSL’s US$3 Billion US Manufacturing Push Altering The Investment Case For CSL (ASX:CSL)?


  • Earlier this month, CSL broke ground on a major expansion of its Kankakee, Illinois manufacturing facility, aiming to boost plasma-derived therapy and albumin output using its patented Horizon 2 process while adding at least 300 new pharmaceutical roles and about 800 construction jobs.
  • This multiyear U.S. build-out, part of more than US$3.00 billion invested in American operations since 2018, signals CSL’s intention to deepen its U.S. manufacturing base and improve plasma efficiency to support longer-term therapy supply.
  • We’ll now examine how this large-scale U.S. manufacturing expansion, built around CSL’s Horizon 2 technology, could influence the company’s investment narrative.

The future of work is here. Discover the 32 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.

CSL Investment Narrative Recap

To own CSL, you need to believe its plasma and specialty therapies portfolio can translate operational improvements into healthier margins after a tough stretch of lower profitability and share price underperformance. The Kankakee Horizon 2 expansion supports the longer term efficiency story, but it does not materially change the near term focus on cost control, execution on new product launches, and the risk that rising collection and manufacturing costs keep pressuring margins.

The recent Kankakee expansion update ties most closely to CSL’s broader manufacturing and cost transformation efforts, including the multiyear US$0.5 billion savings program targeting better plasma collection and processing efficiency. Together with initiatives like Horizon 2, these moves sit at the heart of the main positive catalyst for the stock: whether CSL can convert process improvements into sustainably higher gross margins while managing risks from price competition, regulatory shifts and the planned Seqirus demerger.

Yet investors should be aware that rising plasma costs and lower recent profit margins could still weigh on CSL if…

Read the full narrative on CSL (it’s free!)

CSL’s narrative projects $18.1 billion revenue and $4.2 billion earnings by 2028.

Uncover how CSL’s forecasts yield a A$205.16 fair value, a 52% upside to its current price.

Exploring Other Perspectives

ASX:CSL 1-Year Stock Price ChartASX:CSL 1-Year Stock Price Chart

Some of the lowest ranked analysts were assuming only about 2.9 percent annual revenue growth to roughly US$16.9 billion and earnings around US$3.7 billion, which is far more cautious than the consensus and could be challenged or reinforced by how effectively CSL’s Kankakee build and wider efficiency plans actually improve margins over time.

Explore 18 other fair value estimates on CSL – why the stock might be worth over 2x more than the current price!

The Verdict Is Yours

Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.

Ready For A Different Approach?

Our top stock finds are flying under the radar-for now. Get in early:

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: AI Stock Screener & Alerts

Our new AI Stock Screener scans the market every day to uncover opportunities.

• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies

Or build your own from over 50 metrics.

Explore Now for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link