WASHINGTON POLICY FORUM EXAMINES PHYSICAL AI, MANUFACTURING AND COMPETITIVENESS


At LG-Supported Forum, Policymakers and Industry Leaders Explore How Allied
Manufacturing Partnerships Can Translate AI Advances Into Real-World Industrial Deployment

News Summary

  • “Physical AI in America: Robotics, Manufacturing and the Allied Industrial Base,” a Washington, D.C. policy forum convened by LG Group, examined how Physical AI is reshaping U.S. manufacturing, supply chains and industrial competitiveness.
  • Ambassador Yunju Ko, President of LG Group’s Global Strategy Center, underscored the importance of partnerships across allied nations, pointing to LG’s collaboration with NVIDIA as an example of AI advancing into real-world industrial applications.
  • The forum brought together representatives from government, industry, academia and the policy community who emphasized that technology and supply chain cooperation across allied partners will be essential to building a resilient AI-driven industrial ecosystem.

WASHINGTON, Sept. 29, 2026 /PRNewswire/ — Policymakers, technology leaders and manufacturing experts examined how Physical AI is reshaping U.S. manufacturing, supply chains and industrial competitiveness today at “Physical AI in America: Robotics, Manufacturing and the Allied Industrial Base,” a Washington, D.C. policy forum supported by LG Group.

Participants discussed the industrial capacity and policy framework needed to sustain U.S. AI leadership as AI extends beyond software and computing into the physical economy through robotics, autonomous systems and smart factories. Topics included advanced manufacturing, semiconductors, batteries, energy infrastructure, resilient supply chains and cooperation among trusted allies, including the U.S. and South Korea.

Ambassador Yunju Ko, President of the LG Global Strategy Center, opened the event with a fireside chat. A panel discussion followed, featuring Jessica McBroom, Director at Micron; Juan Higueros, Co-Founder and Chief Operating Officer of Bear Robotics; Tim Del Monico, Chief of Staff to U.S. Representative Sam Liccardo; and Martijn Rasser, Vice President for Technology Leadership at the Special Competitive Studies Project.

Turning AI Innovation Into Industrial Competitiveness
In his remarks, Ko emphasized that long-term AI leadership will depend on both industrial application and closer collaboration with strategic partners.

“The future AI race will not be won by any single company or country acting alone,” said Ko. “It will be won through trusted partnerships that connect innovation, manufacturing and investment across allied nations. By strengthening these partnerships, we can build a more resilient industrial base and ensure that the benefits of AI are translated into real-world economic growth.”

To illustrate this approach, Ko cited LG’s collaborations with NVIDIA across mobility, AI infrastructure and Physical AI. The partnership uses NVIDIA Omniverse libraries, Cosmos world models and the open NVIDIA Isaac robotics platform to create robot training data from LG’s extensive manufacturing experience. Using this data and simulating processes at LG Electronics’ Tennessee appliance factory, LG CLOiD robots are being trained how to move, stack and assemble parts for potential use at U.S. manufacturing sites.

Cooperation Takes Center Stage in Physical AI Discussion
Building on the forum’s broader discussion, panelists focused on the policy priorities and industrial capabilities shaping the development of Physical AI.

The discussion examined the U.S. AI ecosystem, including areas of strength and gaps that could affect long-term technological leadership. Panelists also highlighted that stronger technology and supply chain cooperation between the U.S. and South Korea can contribute to a more resilient AI-driven industrial ecosystem, with supportive policy needed to advance it at scale.

Expanding Investment in U.S. Industry and Future Technologies
Over the past decade, LG has invested more than USD 20 billion in the United States across batteries, advanced manufacturing, electronics and mobility technologies. These efforts have contributed to the U.S. industrial base and approximately 20,000 jobs, while creating a foundation for LG’s collaboration with leading U.S. technology companies in AI, robotics and smart manufacturing.

“As a long-term investment partner, LG has consistently contributed to the growth of the U.S. industrial base,” Ko said. “We look forward to working with innovative U.S. companies, to help accelerate the deployment of AI across real-world industrial applications.”

About the LG Global Strategy Center
The LG Global Strategy Center (GSC) serves as LG Group’s headquarters for global strategy and external affairs. The GSC analyzes geopolitical, economic, and industry developments to assess their implications for LG’s businesses, while coordinating global external engagement and strengthening relationships with key government, policy, and business stakeholders worldwide.

About the LG Washington D.C. Office
The LG Washington D.C. Office is LG Group’s representative office for government affairs and public policy engagement in the United States. Working closely with policymakers, industry stakeholders, think tanks, and business organizations, the LG Washington Office provides strategic insights and promotes constructive dialogue on issues affecting innovation, trade, manufacturing, supply chains, and economic competitiveness. Through these efforts, it supports LG’s commitment to responsible business growth and investment in the United States.

Media Contacts:

LG Group Washington Office   
Joohwa Jin
+1 202 922 9054
[email protected]                              

SOURCE LG Group

Free Training

Source link

DYCM builds US solar manufacturing play amid policy shifts


In 2024, DYCM Power announced plans to develop a 6GW solar cell and module manufacturing facility in the US, backed by an US$800 million investment in partnership with Macquarie Capital. The facility was initially planned to begin commercial operations in the first half of 2026, starting with 2GW of annual production capacity before scaling to its full 6GW of capacity.

In August this year, the company closed an investment round to finance the growth of its business. The financing was secured from investment firms Octo Capital, Audrose Capital Partners and affiliates of Antarctica Capital. Located in Morgan Hill, California, the company’s 150,000-square-foot module assembly plant is expected to begin commercial module shipments from its first heterojunction (HJT) production line in the fourth quarter of 2026.

Speaking to PV Tech Premium, Das acknowledges that the company has adjusted its plans in response to changing policy and market conditions but said its end goal remains the same.

“The overarching goal and the premise of the business haven’t changed,” he says. “We think the need for a reliable supply chain partner is pressing for our customers.”

That reliability is central to DYCM’s pitch. Das says the company has “prioritised transparent negotiations and consistency with customers”, arguing that “module buyers have experienced delays, changing contract terms and other difficulties from suppliers in the past.”

Tapping into cell manufacturing

The next major piece is cell manufacturing. DYCM is working towards establishing its own cell production capability, and the company’s chief technology officer is set to outline its technology choice at PV CellTech USA 2026, taking place on 13–14 October in the San Francisco Bay Area, California.

Das says the company is making good progress but is not yet ready to disclose the technology.

The decision is strategically important. DYCM currently sees a gap in the US market for high-efficiency domestic cells, particularly for leading technologies such as HJT and tunnel oxide passivated contact (TOPCon). Rather than relying indefinitely on external supply, Das says the long-term solution is to manufacture cells itself.

The company is also deliberately limiting its module portfolio. DYCM’s current offering includes modules around 720-730W, a 640W class and a residential class around 450-500W. Utility-scale products are expected to represent roughly two-thirds to three-quarters of output, while smaller modules would use production capacity less efficiently.

US policy and the global supply chain

For DYCM, domestic sourcing is not a reaction to every new policy announcement. Das says he “instructed his team more than two years ago to develop US suppliers for every module component where possible.”

That work has taken time because the domestic solar supply ecosystem remains uneven. DYCM has now developed multiple suppliers for roughly 15 module components, with three or four sources for each item and at least one domestic option in most cases. Das says all suppliers must meet the company’s strict compliance requirements, while supply-chain resilience is also a priority.

Cells are the major exception. DYCM believed it had secured a domestic cell supplier, but that supplier has since encountered problems. The company is working to resolve the situation while developing its own cell capability.

European equipment is being used for DYCM’s manufacturing line, reflecting a strategy that Das says was designed from the outset to avoid problematic supply-chain dependencies. The company’s approach predates some of the latest US trade and policy measures.

Das views the policy environment as broadly positive because incentives encourage customers to buy domestic products. But he also argues that DYCM ultimately needs to be cost-competitive without relying on incentives to generate profits.

For future investment, however, policy certainty matters. Large manufacturing projects require long time horizons, and Das says a more stable five-year policy runway would make it easier to commit significant capital.

India next?

India is an obvious potential next step. Das says DYCM initially explored partnerships with Indian companies, attracted by the country’s scale, manufacturing ambitions and emphasis on supply-chain resilience. Sharma’s background at Vikram Solar and Das’s own connections also give the company a natural familiarity with the market.

But there is no immediate India expansion commitment. Das stresses that DYCM wants to establish its first US facilities successfully before pursuing international growth.

That caution mirrors the company’s broader philosophy: build progressively rather than respond to every market opportunity simultaneously. India remains “the obvious place”, Das says, but it comes after the US manufacturing platform is established.

Looking ahead

The immediate evidence that DYCM’s strategy is gaining traction is customer demand. Das says the company’s order book has increased almost tenfold in three months, compared with the previous year. That has prompted him to begin looking for another building, potentially expanding the company’s manufacturing footprint.

The milestone matters because DYCM’s financing and factory development have had to overcome a classic manufacturing ‘chicken and egg’ problem: customers want to see a factory before committing to a new supplier, while financiers want evidence of sales before backing the factory.

Closing financing earlier this year and ordering equipment for the first production line therefore represented a significant step, allowing customers to see that the project is becoming tangible.

Das now has ambitions well beyond a small initial operation. He says DYCM ultimately wants to become a 10GW company, although he acknowledges the capital required to reach that scale in the US is substantial.

That ambition is also shaped by what Das sees happening beyond conventional utility-scale demand. Data centre developers need new power quickly, and he argues that solar remains one of the fastest routes to deployment. For DYCM, that creates a demand signal that extends beyond today’s policy cycle. The company’s challenge will be converting that demand into bankable long-term capacity while preserving the supply-chain discipline that it sees as its principal competitive advantage in an increasingly volatile US market.

The company is therefore taking what Das repeatedly describes as “one step at a time”. Its next major milestone could be the announcement of its own cell technology and manufacturing plans before the end of the year.

For now, the strategy is clear: build a compliant, resilient US supply chain; establish cell manufacturing; expand capacity as contracted demand develops; and retain the flexibility to pursue markets such as India later.

The policy landscape may continue to change. Das’s answer is not to redesign the business with every regulatory shift, but to stay focused on the underlying thesis that first brought DYCM into the market: US solar demand will continue to grow, and customers will value dependable domestic supply.

DYCM will announce its technology choice for domestic cell manufacturing at our PV CellTech USA conference in California on 13-14 October, which will include further discussions of the US PV industry and its fast-growing domestic supply chain. For further details and booking, visit the event website.

Free Training

Source link

When Drug Pricing Becomes Trade Policy


For years, pharmaceutical companies could treat U.S. reimbursement, European market access, trade policy and manufacturing strategy as related but mostly separate issues. That separation is becoming harder to defend.

The Administration has linked U.S. drug prices to prices paid abroad, pursued voluntary most favored nation agreements, proposed international benchmarks in Medicare, and tied pharmaceutical tariff treatment to both pricing and domestic manufacturing commitments. The important change is not simply that the United States wants lower drug prices.

Foreign reimbursement systems and manufacturing choices are now being pulled into U.S. trade policy. The Supreme Court held in February 2026 that IEEPA does not authorize the President to impose tariffs.

The Administration responded by preserving and expanding other statutory tools. Section 232 is being used against patented pharmaceutical imports and Section 301 is being used to examine foreign pharmaceutical pricing practices.

FDA is also using the Commissioner’s National Priority Voucher (CNPV) program to connect regulatory timing with priorities that include domestic manufacturing and supply chain resilience.

The United Kingdom shows the negotiated path. Germany shows the enforcement path.1-6,13

C SUITE TAKEAWAY

Management should ask more than “What does this reimbursement rule require?” The better question is “How does this pricing, launch, manufacturing or market access decision change our exposure under U.S. payment policy and trade law?”

Seven developments define the current landscape

  1. Most Favored Nation (MFN) pricing has moved from policy idea to announced company agreements. The White House says it has announced 17 agreements with major pharmaceutical manufacturers designed to bring U.S. prices closer to those paid in other developed countries.7
  2. GLOBE and GUARD are still proposed CMS models. They are not final rules. They matter because they show how international prices could become inputs into Medicare Part B and Part D payment policy.8,9
  3. The proposed GLOBE and GUARD rules would exclude a drug while a Medicare Maximum Fair Price is in effect. That reduces the direct IRA versus MFN conflict earlier versions of this paper anticipated.8,9
  4. In February 2026, the Supreme Court held that IEEPA does not authorize the President to impose tariffs. The same day, the White House expressly stated that the rollback did not affect duties imposed under Sections 232 or 301.1,2
  5. The post decision response was immediate. USTR announced accelerated Section 301 investigations, specifically identifying pharmaceutical pricing practices as an area of concern, while the Administration maintained Section 232 tariffs and investigations.3
  6. On April 2, 2026, the President imposed Section 232 tariffs on patented pharmaceuticals and associated ingredients, with tariff treatment linked to trade deals, onshoring plans and MFN pricing agreements. In June, USTR opened a Section 301 investigation into Germany’s alleged underpayment for innovative medicines. Together, those actions show a coordinated two statute strategy directed at both supply chains and foreign pricing systems.4,5
  7. FDA is also adding regulatory speed to the manufacturing equation. The CNPV program can accelerate review for selected products that advance priorities including domestic manufacturing and supply chain resilience or affordability. FDA describes a target review timeline of one to two months and lists multiple approvals under the program in 2026.13

Drug Pricing is Becoming an Enterprise Risk

The old line between reimbursement policy and corporate strategy is fading. The change is easy to describe. A pricing concession in one country can affect an international benchmark.

A launch delay can change which country becomes a reference point. A manufacturing location can change tariff exposure or government leverage.

A market access decision that once looked local can now affect U.S. revenue assumptions. Consider a simple example in which a manufacturer launches a drug in Europe at a lower negotiated price.

That price could later become relevant to a U.S. international benchmark. The same company may manufacture the drug outside the United States, creating a separate tariff question.

Two decisions made by different teams can now affect the economics of the same product. This does not mean every European price automatically becomes a U.S. price or every foreign reimbursement decision becomes a trade violation. The rules differ by program, product and country.

Some U.S. models remain proposed, and the Germany investigation has not produced a final finding. The direction is nevertheless clear: U.S. policymakers are using international price comparisons, company agreements, and trade authorities to influence pharmaceutical economics at home and abroad.

Therefore, management cannot leave drug pricing only to market access, trade only to customs counsel, manufacturing only to operations, or government affairs only to monitoring. Senior leaders need one view of how a decision in one part of the company can move value or risk somewhere else.

MANAGEMENT IMPLICATION

The strategic advantage is understanding what a price or manufacturing decision in one market can do to the rest of the company.

What Changed After the Supreme Court?

The Supreme Court narrowed one tariff pathway. The Administration then turned more heavily to laws that specifically authorize trade action. [Primary source anchors: Supreme Court,1 White House,2 USTR.3]

On February 20, 2026, the Supreme Court held in Learning Resources, Inc. v. Trump, together with Trump v. V.O.S. Selections, Inc., that IEEPA does not authorize the President to impose tariffs. The Court’s ruling matters because it rejected the use of a broad emergency economic statute as tariff authority.

It did not hold that the President lacks all tariff authority. Congress has separately delegated trade powers through other statutes.1

The Administration made its response explicit. On the day of the decision, the White House ended the IEEPA tariff actions at issue while stating that duties imposed under Section 232 of the Trade Expansion Act and Section 301 of the Trade Act were not affected.

USTR separately announced that it would initiate several accelerated Section 301 investigations and specifically identified pharmaceutical pricing practices as a target area.2,3

Section 122 served as a temporary bridge through a 150-day import surcharge tied to balance of payments concerns, but pharmaceuticals and pharmaceutical ingredients were exempt. The more durable pharmaceutical story is the Administration’s move toward Sections 232 and 301.2

What Do Sections 232 and 301 Actually Do?

Section 232 focuses on the product: where it comes from and whether imports threaten national security. On April 2, 2026, the President used it to impose a 100% baseline tariff on covered patented pharmaceuticals and associated ingredients, with different rates for trade deal countries and preferential treatment for companies with approved U.S. manufacturing plans or MFN pricing agreements.

The proclamation links tariff treatment, MFN pricing and domestic manufacturing. Section 301 focuses on the foreign government: whether its acts, policies or practices may be unreasonable, discriminatory or burdensome to U.S. commerce.

On June 18, USTR used that authority to open the Germany pharmaceutical pricing investigation.4,5 The legal novelty is not that Sections 232 and 301 are new statutes.

Both have long histories and established procedures. What has not yet been squarely tested by the Supreme Court is this coordinated post Learning Resources use of statute specific trade authorities to recreate leverage that had previously been asserted through IEEPA, especially when pharmaceutical pricing, reimbursement, market access, and onshoring are treated as parts of one trade strategy.

That does not mean the architecture is unlawful. It means companies should treat litigation risk and statutory fit as part of the strategic analysis rather than assume the new scheme has already received judicial approval.

THE LEGAL POINT

The post IEEPA strategy is not simply “more tariffs.” Section 232 pressures products, manufacturing, and supply chains through a national security theory. Section 301 pressures foreign government practices through an unfair trade theory. Used together, they create leverage on both the company and the country. The statutes are established. Their coordinated pharmaceutical use in this form is still developing.

Regulatory Speed Adds Another Dimension to U.S. Manufacturing Decisions

Trade policy is not the only way the federal government is influencing pharmaceutical manufacturing decisions. FDA is also using regulatory incentives that may change how management evaluates the economics of producing medicines in the United States.13

The CNPV program is designed to accelerate review of selected drugs and biologics that advance defined U.S. health priorities. Those priorities include domestic manufacturing and supply chain resilience, affordability, unmet medical need and important medical innovation.

FDA describes a target review timeline of one to two months for selected applications, compared with six months or more under other priority review programs.13 For management teams, the important point is the value of time.

A U.S. manufacturing decision has traditionally been evaluated against construction costs, labor, taxes, supply chain reliability, and access to the U.S. market. Regulatory timing can now become another part of that calculation.

A company considering U.S. manufacturing should therefore ask whether the location of manufacturing could affect more than tariff exposure and supply chain risk. If a product can qualify for CNPV review, faster regulatory timing may also affect launch planning, revenue timing and the value of the asset. FDA lists multiple approvals under the program in 2026.13

A company should not move manufacturing simply to pursue a voucher. CNPV eligibility depends on the product and the program criteria, and manufacturing investments remain long term decisions. The program does give CEOs and boards another variable to consider when comparing U.S. manufacturing with alternatives elsewhere.

THE MANAGEMENT IMPLICATION

For companies already evaluating U.S. manufacturing capacity, regulatory timing belongs in the same discussion as construction costs, labor, taxes, tariff treatment and supply chain resilience. CNPV does not change the need for a sound manufacturing business case. It gives management another factor to consider when comparing U.S. manufacturing with alternatives elsewhere.13

How MFN Is Being Put into Practice

There is not a single MFN program, as the Administration is using several different approaches that connect prices paid abroad with U.S. pricing policy. The current MFN approach began with Executive Orders in April and May 2025 directing federal agencies to lower prescription drug prices and pursue prices for Americans that more closely reflect prices available in comparable developed countries.10

Since then, the White House says it has announced 17 MFN agreements with major pharmaceutical manufacturers. Those agreements, TrumpRx and related pricing initiatives show that the Administration is using several tools at once: negotiation, public pressure, federal payment policy, market access programs and trade leverage.7,11

GLOBE: Proposed international benchmarking for Part B

GLOBE is a proposed mandatory CMS Innovation Center model for certain Medicare Part B drugs. As proposed, manufacturers would owe rebates when U.S. prices exceed an international benchmark.

CMS currently anticipates an October 1, 2026, start, subject to a final rule.8 One point is especially important. GLOBE would not simply stack a lower international price on top of an IRA negotiated price.

The proposal would exclude a Part B drug while an IRA Maximum Fair Price, or MFP, is in effect. The challenge is therefore managing different pricing systems at different points in a product’s life, not choosing the lower of two federal prices.8

GUARD: Proposed international benchmarking for Part D

GUARD is a proposed mandatory CMS Innovation Center model for certain Medicare Part D drugs. If finalized, CMS anticipates a January 1, 2027, start. Like GLOBE, GUARD would use rebates tied to prices paid in economically comparable countries.9

GUARD would also exclude a drug while an MFP is in effect. International pricing can still affect U.S. economics before or after that period, so management needs to know which program applies when and how an earlier pricing decision may affect the product later.9

GENEROUS: Medicaid and international net prices

GENEROUS works differently—it is a voluntary Medicaid model launched in January 2026. Participating manufacturers provide supplemental rebates intended to align Medicaid net prices with what selected other countries pay, while participating states use standardized coverage rules.12

For executives, the acronym is not the important part. The larger point is that international price comparisons are becoming more common inside U.S. healthcare policy while trade policy is simultaneously being used to pressure foreign pricing and manufacturing behavior. Payment and trade are now moving on parallel tracks.

WHAT NOT TO DO

Do not treat GLOBE, GUARD, and GENEROUS as one unified “MFN rule.” They work differently, apply to different populations and are at different stages. The C-suite needs a product-by-product map, not one slogan.

The United Kingdom: Pricing as the Price of Trade Accommodation

The UK shows how reimbursement policy and tariff policy can be negotiated together [Primary source anchor: UK Government].6

The U.S. and UK pharmaceutical arrangement is one of the clearest examples of reimbursement, MFN policy and trade law being negotiated together. Under the arrangement published April 2, 2026, the UK committed to increase the net NHS price paid for prospective new medicines by 25% beginning in April 2026, increase spending on new medicines over time, modify NICE access economics and cap specified VPAG repayment rates.6

In return, the United States committed to protect qualifying UK pharmaceutical products from Section 232 tariffs through January 19, 2029, provided specified company MFN and tariff agreement conditions are met, and to refrain from additional Section 301 pharmaceutical tariffs during the stated period. The arrangement also expressly references GENEROUS and anticipated GLOBE and GUARD protections intended to reduce launch disincentives in a lower priced market.6

The significance is straightforward. The arrangement does not treat drug prices, patient access, supply chain resilience, MFN, Section 232 and Section 301 as separate policy files. It puts them in the same bargain. That is the architecture this analysis is describing.

What a CEO should see in the UK example

  • A country’s reimbursement system can become part of a broader economic negotiation.
  • Tariff protection can depend on company behavior and government pricing commitments.
  • Governments are now paying attention to launch incentives because a low launch price can affect international reference models.
  • A country’s expected revenue is only one factor in a market access decision.

THE DEEPER LESSON

The UK arrangement is the negotiated version of the new framework: price and access commitments on one side, tariff and launch protections on the other. For global manufacturers, market access and trade strategy need to be managed together.

Germany: Section 301 Turns Reimbursement into Trade Enforcement

Germany shows how the same policy shift can reach a foreign reimbursement system. [Primary source anchor: USTR].5

On June 18, 2026, USTR opened a Section 301 investigation into Germany’s alleged “persistent underpayment” for innovative pharmaceutical products. In simple terms, USTR is asking whether German pricing and reimbursement practices are unreasonable or discriminatory and burden or restrict U.S. commerce.

Those are allegations being investigated, not final legal findings.5 The investigation is still underway.

Written comments were due August 10, 2026, and USTR has scheduled a public hearing for September 22, 2026. The process can end without tariffs, through findings and responsive action, or through a negotiated resolution.5

The larger point goes beyond Germany. Section 232 can pressure where and how pharmaceutical companies manufacture. S

ection 301 can pressure how foreign governments pay for medicines. Germany therefore supplies the second half of the coordinated strategy that the April Section 232 proclamation began to make concrete.4,5

A CAUTION FOR MANAGEMENT

Do not assume the Germany investigation means tariffs are inevitable. Section 301 is a process. Management should assume, however, that foreign pharmaceutical pricing policy can now lead to U.S. trade scrutiny, political pressure, and, potentially, responsive action.

Five Questions the C Suite Should Ask Now

The objective is to turn policy complexity into decision discipline.

  1. Where should we launch, and in what order? Launch sequencing now affects more than time to revenue. Management should ask whether a launch price in one market could influence an international benchmark, affect another government negotiation or change the economics of entering a lower priced market.
  2. Which international prices create U.S. exposure? The company should know which products, countries and net price arrangements could matter under GLOBE, GUARD, GENEROUS, voluntary MFN commitments or future federal models. Where a policy looks to net pricing, the analysis should include confidential rebates and not just public list prices.
  3. What happens if another country “becomes Germany?” Every major market access strategy should be tested for two questions: what does this mean locally, and could U.S. policymakers view the system as unfair to U.S. commerce?
  4. How does manufacturing location change our options? Section 232 makes manufacturing location, country of origin and domestic manufacturing commitments relevant to tariff treatment. CNPV adds a separate regulatory consideration because domestic manufacturing and supply chain resilience are among the priorities that can support accelerated review for selected products. Section 301 remains relevant where a foreign government’s reimbursement system becomes a trade issue. Management should model what the company controls, what regulatory incentives may be available and what a government partner may be pressured to change.13
  5. Who inside the company makes sure these decisions connect? If legal, market access, finance, government affairs, trade and supply chain teams optimize separately, the company may create global exposure while making a locally rational decision. Senior management needs a process that forces those perspectives into the same room before a material commitment is made.

How Management Can Put the Pieces Together

The goal is simple: give management one way to see how pricing, trade, manufacturing and market access decisions connect. Management does not need to predict every final rule.

It needs a repeatable way to test major decisions against a changing set of legal and commercial risks. We recommend building one cross border pricing and trade exposure map around the company’s major products and pipeline assets.

The transaction and investment lens

This same framework should be used in acquisitions, licensing deals and major capital projects. A product’s pricing history, European launch sequence, manufacturing footprint and government commitments can affect future value even when they do not stand out in a traditional healthcare regulatory review. Investors and boards should ask whether those factors add value, limit flexibility or create a risk that has not been modeled.

What Management Teams Should Do in the Next 90 Days

The current environment favors preparation over prediction. Build one enterprise exposure map. Do not maintain separate U.S., UK, and EU trade analyses that never connect. Put the major products, markets, prices, rebates, launch dates and manufacturing locations on one decision map.

Revisit launch sequencing assumptions. Identify lower priced markets that could affect an international benchmark or a government negotiating position. Consider whether timing, sequencing, or a different contract structure changes the economics.

Stress test the UK and Germany scenarios. Ask what the company would do if a key market were offered a UK style accommodation, faced a Germany style Section 301 investigation, or saw its pharmaceutical exports subjected to Section 232 leverage.

Review the manufacturing footprint through a trade and regulatory lens. For each critical patented product and ingredient, identify country of origin, applicable Section 232 treatment, domestic manufacturing commitments, trade deal status, alternative sourcing and the financial cost of a tariff or policy change.

For products tied to current or planned U.S. manufacturing, assess whether CNPV eligibility or regulatory timing should be part of the investment analysis.13

Set a senior escalation rule. Major pricing, launch and manufacturing decisions should trigger a cross functional review before the company gives up flexibility that may be valuable in another market. Monitor the rules that can change the map.

GLOBE and GUARD remain proposed, the Germany Section 301 process is ongoing, and the pharmaceutical Section 232 regime contains country and company specific conditions. Management should plan around the current landscape while keeping enough flexibility to update assumptions as rules, agreements, enforcement actions, and litigation evolve.

BOARD LEVEL QUESTION

Can management explain, on one page, how a major pricing decision in Europe could change U.S. reimbursement, trade, manufacturing and valuation exposure? If not, the company probably does not yet have one enterprise view of the risk.

Conclusion

Drug pricing has entered a new phase. Foreign pharmaceutical prices are now part of more than a domestic affordability debate.

International prices appear in federal payment models and manufacturer agreements, while pharmaceutical pricing, manufacturing and market access have become subjects of bilateral trade negotiation and statutory trade enforcement.

The Supreme Court’s Learning Resources decision removed IEEPA as the tariff authority the Administration had been using. The policy response was not retreat.

The White House expressly preserved Sections 232 and 301, USTR announced new Section 301 investigations that included pharmaceutical pricing, the President imposed a pharmaceutical Section 232 regime in April, and USTR opened the Germany pharmaceutical pricing investigation in June.1-5

For CEOs, CFOs, general counsel and commercial leaders, the most important development may be the structure that emerges from those actions. Section 232 can link tariff treatment to manufacturing, domestic investment and MFN commitments.

Section 301 can convert a foreign reimbursement policy into a U.S. trade dispute. CNPV adds regulatory timing to the manufacturing decision by making domestic manufacturing and supply chain resilience relevant to accelerated review eligibility for selected products.

Together, these tools can affect company decisions, government policy and the economics of where a product is developed, manufactured and launched.13

The statutes themselves are not new, and this paper does not assume that a court would uphold or invalidate every future application. The unresolved issue is how far this coordinated use of Sections 232 and 301 can go when tested against the language, procedures and limits of Sections 232 and 301.

Companies should not wait for that litigation to be resolved before understanding their exposure. The better approach is to see the connections before the commercial decision is made. That is where policy foresight becomes business strategy.

About the Author

Ron Lanton, Senior Partner & Global Strategist at Lanton, Lanton & Sosa Law PLLC.

References

The following primary government sources support the principal legal and policy developments discussed in this paper. They are included so readers can independently verify the underlying events. All were current as of August 14, 2026.

  1. Supreme Court of the United States. Learning Resources, Inc. v. Trump; Trump v. V.O.S. Selections, Inc. Opinion issued February 20, 2026. supremecourt.gov
  2. The White House. Ending Certain Tariff Actions; Imposing a Temporary Import Surcharge to Address Fundamental International Payments Problems. Published February 20, 2026. whitehouse.gov
  3. Office of the US Trade Representative. Ambassador Greer Issues Statement on Supreme Court IEEPA Decision. Published February 20, 2026. ustr.gov
  4. The White House. Adjusting Imports of Pharmaceuticals and Pharmaceutical Ingredients into the United States. Published April 2, 2026. whitehouse.gov
  5. Office of the US Trade Representative. USTR Announces Initiation of Section 301 Investigation of Germany’s Persistent Underpayment for Innovative Pharmaceutical Products. Published June 18, 2026. ustr.gov
  6. Government of the United Kingdom. Arrangement Between the United States of America and the United Kingdom on Pharmaceutical Pricing. Published April 2, 2026. gov.uk
  7. The White House. Fact Sheet: Expansion of TrumpRx.gov and 17 Most-Favored-Nation Drug Pricing Agreements. Published May 18, 2026. whitehouse.gov
  8. Centers for Medicare & Medicaid Services. GLOBE Model. cms.gov. Accessed August 19, 2026.
  9. Centers for Medicare & Medicaid Services. GUARD Model. cms.gov. Accessed August 19, 2026.
  10. The White House. Lowering Drug Prices by Once Again Putting Americans First. Published April 15, 2025. whitehouse.gov; The White House. Delivering Most-Favored-Nation Prescription Drug Pricing to American Patients. Published May 12, 2025. whitehouse.gov
  11. The White House. Savings from Most-Favored-Nation Drug Pricing Policy. Published May 5, 2026. whitehouse.gov
  12. Centers for Medicare & Medicaid Services. GENEROUS Model. Updated July 1, 2026. cms.gov
  13. US Food and Drug Administration. Commissioner’s National Priority Voucher (CNPV) Pilot Program. Updated August 14, 2026. fda.gov

Free Training

Source link

235 new clean energy factories opened in 5 years as a US manufacturing boom powers through policy headwinds


235 new clean energy factories opened in 5 years as a US manufacturing boom powers through policy headwinds Photo Credit: iStock

America’s clean energy manufacturing boom is still gaining speed — even as tariffs and broader policy uncertainty hang over the sector.

According to SolarQuarter, a new industry report said the United States added more than 235 clean energy factories in just five years, with domestic production emerging as a major force in both the economy and the energy transition.

What’s happening?

The American Clean Power Association’s second annual State of Clean Energy Manufacturing said the sector has grown rapidly.

In addition to the new clean energy manufacturing facilities, the report found that U.S. production capacity is sufficient to meet domestic demand for solar modules, battery modules, wind towers, and wind nacelles. That marks a major shift for an industry that has long depended on overseas supply chains.

Jason Grumet, CEO of the American Clean Power Association, said the surge is especially important amid rising energy demand, per SolarQuarter. But he also cautioned that sustaining the momentum will require clear, targeted, and consistent trade policy, along with realistic timelines for tariff compliance and greater regulatory certainty.

Why does it matter?

More domestic clean energy manufacturing can help make the electrical grid more reliable, reduce dependence on foreign supply chains, and support the faster deployment of renewable power sources (such as wind and solar) that can lower energy costs over time.

The report also found that each clean energy manufacturing job supports four additional jobs across the broader economy — one linked to suppliers and three tied to household spending.

As U.S. manufacturing expands, technologies like solar panels and batteries may become more accessible.

What are people saying?

Grumet said that as energy demand rises, the U.S. needs more clean power systems built at home.

The ACPA report points to factory growth, domestic manufacturing strength, and the sector’s ripple effects on jobs and local economies.

Even with policy headwinds, clean energy manufacturing can become a cornerstone of American industry.

Get TCD’s free newsletters for easy tips, smart advice, and a chance to earn $5,000 toward home upgrades. To see more stories like this one, change your Google preferences here.

Free Training

Source link

Reshoring Initiative Seeking Survey Responses to Shape U.S. Manufacturing Policy Decisions


The Reshoring Initiative, in collaboration with Regions Recruiting, is seeking responses to its 2026 Reshoring Survey. U.S. manufacturing policy is being decided now — and it will directly affect costs, supply chain and competitiveness. The Reshoring Initiative is pivoting its strategy based on survey feedback.

The Reshoring Initiative’s goal is to collect data to get an accurate picture of the industry at this pivotal time in U.S. manufacturing history. This 10-minute survey questions how trade conditions, global risks and federal policies are affecting reshoring and foreign direct investment (FDI) decisions. Survey responses go directly into the data used by policymakers and economic developers working to strengthen U.S. manufacturing. This survey is one of the most direct ways to influence policy outcomes.

The Reshoring Initiatives 2025 survey explored the likely impact of contemplated 2025 policy changes. The survey also revealed the strategic imperatives necessary for U.S. re-industrialization, including:

  • Level the cost playing field
  • Develop or grow a larger, skilled workforce
  • Apply total cost of ownership (TCO) principles
  • Prepare for geopolitical risk

The 2026 survey focuses more on the impact of actual policy changes, including taxes, tariffs and the resulting uncertainty, the need for a robust skilled workforce and training system and the expected impact of AI. This year’s survey assesses the rationalizations behind reshoring decisions in addition to the impacts of the 2025 federal policy changes.

Data provided will be analyzed by the Reshoring Initiative and Regions Recruiting to produce industry-wide reports and strategic recommendations aimed at strengthening the U.S. manufacturing sector. The findings will be shared with industry leaders as well as the Trump administration to help shape the policies that will benefit both manufacturing and the country.

“The pandemic was an eye-opener and now, the war with Iran is showing us what’s at risk when supply chains are disrupted. Most of our OEM clients continue to work on supply chain resiliency strategies — and the building of teams and technological capabilities required to execute them,” says Kathy Nunnally, managing partner at Regions Recruiting. “There is a bright future ahead for domestic contract manufacturers, that’s for sure.”

The organization is monitoring the responses coming into the 2026 Reshoring Survey and their heat map has some significant “cold spots.”


Source: Reshoring Initiative

Despite industrial output, the Reshoring Initiative has seen little to no participation from:

  • Indiana: Often ranked number one in manufacturing as a percent of state GDP
  • Michigan: The historical heart of the U.S. automotive industry
  • Arizona: A leading hub for semiconductors and aerospace
  • Tennessee and Alabama: Modern hubs for automotive and critical equipment
  • South Carolina and Georgia: Centers for aerospace, automotive and more.

The Reshoring Initiative needs participation from these vital regions. With their participation, the Reshoring Initiative can provide the insights necessary to support U.S. re-industrialization.

The nationwide 2026 Reshoring Survey will remain open to respondents through July 15, 2026. The survey will gather experience and insights from manufacturing operations, supply chain/procurement decision-makers and contract manufacturers.

The Reshoring Initiative invites OEMs and contract manufacturers CMs to participate in this brief survey about the current trends in reshoring and FDI, shifting manufacturing operations and sourcing to the United States.

Your participation in the 2026 Reshoring Survey can help influence national policy. To access the full list of resources offered by the Reshoring Initiative, visit www.reshorenow.org/resources/.

Free Training

Source link

U.S. Clean Energy Manufacturing Surges Ahead Despite Policy Hurdles, Reports The American Clean Power Association


Representational image. Credit: Canva

Momentum in the American clean energy manufacturing sector continues to build despite ongoing policy challenges, according to the second annual State of Clean Energy Manufacturing report released by the American Clean Power Association. The report shows that clean energy manufacturing has become a key pillar of the U.S. industrial economy, offering affordable, reliable and quickly deployable domestic solutions to meet the nation’s growing energy needs.

By increasing production within the United States, the industry also boosts national security by reducing dependence on foreign energy supplies and international supply chains.Speaking about the findings, Jason Grumet emphasized that rising energy demand makes it essential to expand clean power systems built in the U.S.

He explained that to sustain the current manufacturing growth, the country needs clear, targeted and consistent international trade policies. This includes reasonable timelines for complying with tariffs and greater regulatory certainty, which would allow clean energy manufacturers to continue supporting economic development and strengthening local communities across the nation.The report highlights several important trends.

It notes that every clean energy manufacturing job generates four additional jobs across the wider economy—one through supply-chain activities and three more through household spending. It also points out that more than 235 new clean energy manufacturing facilities have opened in the United States over the past five years.

Today, more than 300 factories nationwide produce essential components such as wind turbine blades, towers, nacelles, solar modules and batteries. The report further states that domestic manufacturing capacity is now sufficient to fully meet U.S. demand for solar modules, battery modules, wind towers and wind nacelles.

Overall, the findings reinforce that clean energy manufacturing is not only advancing the country’s energy infrastructure but also significantly contributing to economic growth and national resilience, even in the face of policy headwinds.

Free Training

Source link

Assessing the Impacts of Foreign Pollution on U.S. Public Health and Manufacturing • Bipartisan Policy Center


Executive Summary

Major economies like China and India emit more pollution than the United States to produce the same value of goods. High-altitude winds carry this foreign pollution long distances to U.S. shores, damaging America’s air quality. Foreign-produced pollution elevates West Coast ozone levels by up to 20% seasonally, while particulate matter produced abroad causes an estimated 8,000 premature deaths and over $60 billion in health care costs in the United States annually.

Meanwhile, foreign pollution has contributed to “nonattainment” designations in at least 85 U.S. counties, meaning these areas fail to meet federal air-quality standards in part because of foreign-produced pollutants. This status forces states to tighten pollution controls to maintain healthy air quality, which can delay industrial permits and limit manufacturing operations even for low-polluting firms. The United States currently lacks a legal framework to exclude routine foreign pollution from nonattainment designations, but creating new exemptions would weaken air-quality protections to the detriment of public health. Additional policy solutions are needed to address foreign pollution at its source, such as investment in intercountry pollution monitoring to better understand the scope of the problem and targeted pollution tariffs to encourage improved environmental practices abroad.

Introduction

Shifts in global manufacturing have concentrated industrial production in economies with lax environmental standards and enforcement. In many instances, foreign companies leverage government policies to subsidize and expand industries that depend on outdated, low-cost, environmentally irresponsible practices.[1] This undercuts U.S. manufacturers that maintain higher environmental and labor standards, which has a compounding effect on American jobs, U.S. national security, and the planet’s climate.[2]

This issue brief shows how foreign pollution threatens U.S. public health and manufacturing directly. Winds sweep foreign-produced air pollutants, distinct from greenhouse gases (GHGs), across oceans and continents into America’s atmosphere.[3] These intrusions contribute to respiratory, cardiovascular, and neurological diseases, which have been linked to premature deaths across the country.[4]

Moreover, foreign pollution constrains American manufacturing by filling up maximum pollution thresholds. The Environmental Protection Agency (EPA) designates certain geographic areas as being in “nonattainment” when they do not meet federal air quality standards for specific pollutants under the Clean Air Act. When foreign pollution contributes to a county receiving a nonattainment designation, it unfairly restricts American industry by curbing manufacturing activity and blocking permits for new industrial facilities.

This issue brief examines the multifaceted effects that foreign pollution has on U.S. environmental and economic security. It evaluates the sufficiency of existing domestic countermeasures and recommends policies that could reduce foreign pollution levels at the source—long before foreign pollutants arrive in the United States. For more on the scale of foreign pollution relative to U.S. levels and its pathways into the U.S. atmosphere, see Appendix I and II.

Impacts of Foreign Pollution on the United States

When major manufacturing hubs abroad operate without sufficient environmental standards, the consequences are global. Foreign pollution is a problem that harms American citizens directly.

Table 1. Estimated Annual Impacts of Foreign Pollution on the United States

ImpactEstimated Number (annual)Specific CausePremature Deaths8,000Breathing of particulate matter pollutionHealth Care Costs$60BIncreased medical expenses, rehabilitation, prescription medications, lost wagesCounties with Nonattainment Designations85+Western U.S. counties affected by foreign pollution and designated as being in nonattainment

Sources: Nature[5], NRDC[6] , and EPA[7]

Threat to Public Health

Foreign pollution exacts a heavy toll on America’s public health. Trans-Pacific ozone and particulate matter from Asian sources contribute to thousands of premature deaths annually in the Western United States, alongside nonfatal respiratory, cardiovascular, and neurological illnesses.[8] The EPA links elevated levels of ozone, black carbon, and carbon monoxide to adverse outcomes, including heart attacks, asthma exacerbation, lung damage, and premature mortality.[9]

Overall, air pollution in the United States imposes health and economic costs exceeding $800 billion annually,[10] with foreign-sourced contributions representing a portion that disproportionately affects vulnerable border and coastal communities. For example, estimates suggest that foreign-produced pollution causes more than $60 billion in U.S. health care costs per year.[11]

Threat to Manufacturing

Under the Clean Air Act, states must meet National Ambient Air Quality Standards (NAAQS) for six criteria pollutants, including ozone and particulate matter. [12] This means that foreign pollution can limit American companies even on American soil, if the levels of a particular pollutant are near or exceed the NAAQS in the area where the company operates.

At least 85 counties impacted by Chinese pollution are in nonattainment for criteria pollutants,[13] meaning that they do not meet federal air-quality standards. This status can block industrial permits and inhibit manufacturing growth, even for U.S. firms that operate with low levels of pollution, by requiring states to adopt and enforce State Implementation Plans to lower pollution levels.[14] This “exported nonattainment” from other countries stifles economic activity in border and Western states, exacerbating job losses due to high-polluting competitors abroad.[15] Recent nonattainment designations leading to tighter restrictions, such as in Phoenix-Mesa, AZ, explicitly cite international pollution as a factor in pushing local air-quality levels above federal standards.[16]

Gaps in U.S. Law for Foreign Pollution and the Public Health Consequences of Weakening Standards

Current U.S. law limits the ability to exclude routine foreign pollution from nonattainment designations,[17] and for good reason. Attempts to create additional exceptions for these foreign pollution sources would endanger American public health because they would increase domestic pollution levels overall.

No Mechanism Exists to Exclude Persistent Foreign Pollution

Existing legal frameworks provide little relief for the contribution of foreign pollution to nonattainment designations. The Cross-State Air Pollution Rule (CSAPR), for instance, targets domestic interstate pollution by requiring 28 Eastern states to cut power plant emissions of sulfur dioxide (SO₂) and nitrogen oxides (NOx)—but it entirely ignores foreign sources.[18] This lapse leaves trans-Pacific or cross-border contributions unaddressed despite their role in exacerbating nonattainment across the country.

 The “exceptional events” rule under the Clean Air Act does allow states to submit a request to exclude certain pollution events from nonattainment calculations. This exception, however, is designed only for “exceptional events”: pollution from natural events like wildfires or human-caused activities that are unlikely to reoccur.[19] Routine pollution from foreign sources does not qualify.

Exclusions for Foreign Pollution Could Endanger Public Health

Despite the potential benefits for domestic manufacturing, carve-outs for persistent foreign pollution would come at a cost to public health. If foreign pollution is excluded from nonattainment designations, the result would be higher acceptable levels of pollution in the United States. Maintaining healthy pollution levels is critical to protect Americans from harmful overexposure to pollutants. As a result, reforms to existing standards are insufficient to address the full scope of the problem.

A more targeted approach is needed to reduce foreign pollution before it occurs, balancing the protection of American public health with the best interests of U.S. manufacturing.

Conclusion and Policy Recommendations

Foreign pollution is a danger to American lives, jobs, and the economy. Mitigation will require an increased ability to evaluate foreign pollution and action to lower high pollution levels at their sources. To accomplish this goal, U.S. domestic policy should:

  1. Invest in Pollution Monitoring: Allocate resources for advanced monitoring of transboundary pollutants, including through satellite networks, to better understand the scope of the problem.
  2. Leverage Trade Tools: Impose border pollution adjustments or pollution tariffs on imports to encourage improved pollution control abroad.
  3. Promote Clean Tech Exports: Incentivize U.S. exports of low-pollution and pollution-control technologies to countries with outdated, inefficient equipment.
  4. Pursue Targeted Diplomacy: Prioritize bilateral agreements with key polluters (e.g., U.S.-China-Mexico), ensuring that these agreements target high-impact pollutants, such as particulate matter.
  5. Integrate Metrics Into Trade Agreements: Embed foreign pollution metrics and standards into international agreements.

If implemented, measures that pursue these objectives could level the playing field for clean producers in the United States, protect public health from harmful foreign pollutants, and mitigate the threat of foreign pollution to domestic manufacturing.

Appendix

I. Relative Pollution Abroad Far Exceeds U.S. Levels

Most major economies, particularly those engaged in noncompetitive industrial practices like China, emit far higher levels of pollution than the United States relative to their economic output. For instance, compared with U.S. producers, Chinese manufacturers emit approximately four times more nitrogen oxide (NOx), six times more particulate matter (PM2.5), seven times more sulfur dioxide (SO2), and 19 times more carbon monoxide (CO) to produce the same value of goods (see Figure 1). The EPA sets limits on domestic levels of all four of these gases, classified as “criteria pollutants,” due to their harmful effects on human health and the environment.

Figure 1. Pollution intensity for the U.S., China, and India

Source: Climate Leadership Council[20]

China is the largest global polluter, accounting for about 56% of the world’s coal use.[21] In addition to releasing 32% of global greenhouse gas (GHG) emissions, China contributes a high percentage of the world’s non-GHG pollution.[22]

Poor air quality resulting from inadequate regulation of these pollutants has led to up to 2 million premature deaths per year in China.[23] In the past, enforcement of environmental standards in China has been largely left to local government officials. For example, environmental inspectors in northern China investigated 20,000 businesses in 2017 and found that 70% failed to meet standards for air pollution control.[24] Companies were emitting more than their reported quantities, operating with insufficient pollution control equipment, and operating in unauthorized locations.

India presents a comparable challenge. Unregulated industrial practices contribute to high levels of criteria pollutants in India,[25] while the country continues to rely on pollution-intensive coal to generate 70% of its electricity.[26] Compared to U.S. producers, Indian manufacturers emit approximately 7 times more nitrogen oxide (NOx), 13 times more carbon monoxide (CO), 21x more particulate matter (PM2.5), and 35 times more sulfur dioxide (SO2) to produce the same value of goods (see Figure 1).

Poor air quality in India results in 1.67 million premature deaths annually[27] and economic losses of $36.8 billion from declines in health and productivity.[28] In northern India, inspections frequently reveal factories operating with inadequate pollution controls, mirroring pollution enforcement challenges in China.[29]

Disparities in pollution levels, as showcased by China and India, not only fuel disproportionate increases in global emissions but also result in significant non-GHG pollution that is exported directly to the United States.

II. Foreign Pollution Affects U.S. Air Quality

Pollutants produced abroad infiltrate the atmosphere over the United States via long-range atmospheric transport—high-altitude winds that carry pollutants over oceans and continents alike.[30] Air pollutants can be carried thousands of miles, from the mercury emitted by coal-burning power plants abroad to the particulate matter and sulfur dioxide that steel plants emit when they do not properly dispose of waste.[31]

Although most research on long-range pollution movement was conducted in the 2000s and early 2010s, trends strongly indicate that pollution from countries like China continues to affect U.S. air quality. Chinese coal use, for example, increased by roughly 20% between 2010 and 2022.[32]

Atmospheric modeling shows that prevailing westerly winds and jet streams enable trans-Pacific movement of pollutants from Asia to America’s West Coast, while pollution from Canada and Mexico affect air quality in U.S. border states.[33] Fluctuations in wind patterns throughout the year create seasonal peaks in the spring.

Examples

  • Ozone: Ground-level ozone forms when pollutants such as nitrogen oxides (NOx) and volatile organic compounds (VOCs) react with sunlight. Models have found that ozone pollutants transported across the Pacific Ocean from Asia add an average of 5-7 parts per billion by volume (ppbv) to surface ozone levels in the Western United States and 2-5 ppbv to levels in the Eastern United States (see Figure 2).[34] For comparison, the EPA’s health-based standard for ozone levels is capped at 70 ppbv.[35] During seasonal peaks in the spring, concentrated plumes of ozone from Asia can contribute 8-15 ppbv, accounting for up to 20% of total permitted ozone levels in certain U.S. states.[36]  Roughly half of these transported ozone emissions come from China.[37]

Figure 2. Illustration of how Asian pollution increases ozone concentrations over different parts of the U.S. within a sample one-month period.

Source: Atmospheric Chemistry and Physics [38]

  • Other pollutants: Fine particles like sulfates and black carbon from Asian industrial production and biomass burning affect California, Oregon, Washington, and similar states. Trans-Pacific aerosols contribute 6%–18% of U.S. black carbon and up to 36% of particulate matter (PM₂.₅) in affected areas.[39] Asian coal plants emit mercury that circulates globally, contributing 14%–17% to U.S. mercury levels.[40] Chinese pollution also adds 8%–28% to Western U.S. levels of sulfur dioxide and 9%–14% to levels of carbon monoxide.[41]

[1] Joseph S. Shapiro and Reed Walker, “Why Is Pollution from U.S. Manufacturing Declining? The Roles of Environmental Regulation, Productivity, and Trade,” American Economic Review, 108(12): 3814-3854, December 2018. Available at: https://www.aeaweb.org/articles?id=10.1257/aer.20151272.

[2] Catrina Rorke, Scott Nystrom, and Daniel Hoenig, “America’s Carbon Advantage 2025,” Climate Leadership Council, March 2025. Available at https://clcouncil.org/report/americas-carbon-advantage-2025/.

[3] NASA Jet Propulsion Laboratory, “Nature, Chinese Pollution Offset U.S. West Ozone Gains,” August 10, 2015. Available at: https://www.jpl.nasa.gov/news/nature-chinese-pollution-offset-us-west-ozone-gains/?referrer=grok.com.

[4] Environmental Protection Agency, “Health Effects of Ozone Pollution.” Available at: https://www.epa.gov/ground-level-ozone-pollution/health-effects-ozone-pollution; Environmental Protection Agency, “Particle Pollution and Respiratory Effects.” Available at https://www.epa.gov/pmcourse/particle-pollution-and-respiratory-effects.

[5] Estimate for the annual premature deaths comes from Qiang Zhang, Xujia Jiang, et al., “Transboundary Health Impacts of Transported Global Air Pollution and International Trade,” Nature, 543(7647): 707, Figure 2a, 2017. Available at: https://www.nature.com/articles/nature21712.

[6] The estimate for annual health care costs is based on the valuation of premature deaths, productivity losses, and medical costs in “The Costs of Inaction: The Burden of Climate Change on Health,” Natural Resources Defense Council, 4, 2021. Available at: https://www.nrdc.org/sites/default/files/costs-inaction-burden-health-report.pdf. BPC multiplied NRDC’s numbers by the number of deaths attributed to foreign pollution specifically by Qiang Zhang, Xujia Jiang, et al., “Transboundary Health Impacts…,” Nature, pg. 707, Figure 2.a.

[7] Estimates for foreign-impacted nonattainment designations stem from authors’ calculations using Environmental Protection Agency, “Green Book: Nonattainment Areas for Criteria Pollutants; Clean Air Fund,” 2025. Available at: https://www.epa.gov/green-book.

[8] Environmental Protection Agency, “Health Effects of Ozone Pollution;” Available at: https:// www.epa.gov/ground-level-ozone-pollution/health-effects-ozone-pollution.

[9] Environmental Protection Agency, “Health Effects of Particulates and Black Carbon.” Available at: https://www.epa.gov/sites/default/files/2014-05/documents/health-effects.pdf.

[10] Natural Resources Defense Council, “The Costs of Inaction: The Burden of Climate Change on Health,”, 2021, Available at: https://www.nrdc.org/sites/default/files/costs-inaction-burden-health-report.pdf.

[11] See Endnote 6.

[12] Environmental Protection Agency, “Summary of the Clean Air Act,” 2025. Available at: https://www.epa.gov/laws-regulations/summary-clean-air-act.

[13] Environmental Protection Agency, “Green Book: Nonattainment Areas for Criteria Pollutants; Clean Air Fund,” 2025. Available at: https://www.epa.gov/green-book.

[14] Joseph S. Shapiro and Reed Walker, “Where is Pollution Moving? Environmental Markets and Environmental Justice,” NBER Working Paper 28389, January 2021. Available at: https://www.nber.org/papers/w28389.

[15] Ibid.

[16] “Determination of Attainment by the Attainment Date but for International Emissions for the 2015 Ozone NAAQS: PhoenixMesa Nonattainment Area,” Federal Register, 90(221): November 19, 2025. Available at: https://www.federalregister.gov/documents/2025/11/19/2025-20357/determination-of-attainment-by-the-attainment-date-but-for-international-emissions-for-the-2015.

[17] Note that there is a legal framework for factoring foreign pollution into the severity of nonattainment classification under Section 179B of the Clean Air Act. See “42 U.S.C. §7509a – International border areas,” Cornell Law School. Available at: https://www.law.cornell.edu/uscode/text/42/7509a.

[18] Environmental Protection Agency, “Cross-State Air Pollution Rule (CSAPR),” 2025. Available at: https://www.epa.gov/Cross-State-Air-Pollution.

[19] Environmental Protection Agency, “Treatment of Data Influenced by Exceptional Events; Final Rule,” Federal Register, 81(191): October 3, 2016. Available at: https://www.federalregister.gov/documents/2016/10/03/2016-22983/treatment-of-data-influenced-by-exceptional-events.

[20] Scott Nystrom, “Country-level Analysis of Traditional Air Pollution Intensity,” Climate Leadership Council, February 25, 2026. Available at: https://www.clcouncil.org/blog/pollution-intensity/.

[21] International Energy Agency, “Coal Mid-Year Update,” July 2025. Available at: https://www.iea.org/reports/coal-mid-year-update-2025.

[22] Carbon Brief, “Analysis: China’s CO2 Emissions Have Now Been Flat or Falling for 18 Months,” February 4, 2025. Available at: https://www.carbonbrief.org/analysis-chinas-co2-emissions-have-now-been-flat-or-falling-for-18-months/.

[23] Aristeidis K. Georgoulias, Jos Lelieveld, et al., “Avoided Mortality by Particulate Air Pollution Control Measures in China,” Science of the Total Environment, 2025. Available at: https://www.sciencedirect.com/science/article/pii/S0048969725022065.

[24] Xiang Bo, “Inspections find 70 pct of firms violated environmental rules,” Xinhua Net, June 11, 2017. Available at: http://www.xinhuanet.com//english/2017-06/11/c_136356860.htm.

[25] World Bank Group, “How is India Trying to Address Air Pollution?” June 5, 2024. Available at: https://www.worldbank.org/en/country/india/publication/catalyzing-clean-air-in-india.

[26] Ember, “India,” 2026. Available at: https://ember-energy.org/countries-and-regions/india/.

[27] BC News, “The human toll of air pollution in India,” Boston College2025. Available at: https://www.bc.edu/bc-web/bcnews/nation-world-society/international/air-pollution-in-inda.html. 

[28] World Bank, “How Is India Trying to Address Air Pollution?” 2024/2025, Available at: https://www.worldbank.org/en/country/india/publication/catalyzing-clean-air-in-india.

[29] Garvit Bhirani, “Air Pollution: CAQM orders closure of 16 industrial units in Rajasthan, Uttar Pradesh, Haryana over gross violations,” Mint, January 9, 2026. Available at: https:// www.livemint.com/news/india/air-pollution-caqm-orders-closure-of-16-industrial-units-in-rajasthan-uttar-pradesh-haryana-over-gross-violations-11767970582778.html.

[30] National Academy of Sciences, “Global Sources of Local Pollution: An Assessment of Long Range Transport of Key Air Pollutants To and From the United States,” 2009. Available at: https://nap.nationalacademies.org/resource/12743/global_sources_brief_final.pdf; Environmental Protection Agency, Total Maximum Daily Loads (TMDLs). Available at: https://www.epa.gov/tmdl/overview-total-maximum-daily-loads-tmdls.

[31] Meiyun Lin, Arlene M. Fiore, et al., “Transport of Asian Ozone Pollution into Surface Air over the Western United States in Spring,” Journal of Geophysical Research: Atmospheres, 117: 2012. Available at: https://agupubs.onlinelibrary.wiley.com/doi/full/10.1029/2011JD016961.

[32] Scott Nystrom, “Why is U.S. industry 3x more carbon efficient than China?” Climate Leadership Council, February 4, 2025. Available at: https://clcouncil.org/blog/why-is-u-s-industry-3x-more-carbon-efficient-than-china/.

[33] Charles L. Heald, Daniel J. Jacob, et al., “Transpacific Transport of Asian Anthropogenic Aerosols,” Journal of Geophysical Research: Atmospheres, 111: 2006/2025. Available at: https://agupubs.onlinelibrary.wiley.com/doi/full/10.1029/2005JD006847.

[34] Ppbv describes the number of pollutant molecules per billion air molecules.

[35] Environmental Protection Agency, “Ozone National Ambient Air Quality Standards (NAAQS).” Available at: https://www.epa.gov/ground-level-ozone-pollution/ozone-national-ambient-air-quality-standards-naaqs.

[36] O. R. Cooper, D. D. Parrish, et al., “Increasing springtime ozone mixing ratios in the free troposphere over western North America,” Nature. Available at: https://www.nature.com/ articles/nature08708, as cited in Meiyun Lin, Arlene M. Fiore, et al., “Transport of Asian Ozone Pollution into Surface Air over the Western United States in Spring,” Journal of Geophysical Research: Atmospheres, 117: 2012. Available at: https://agupubs.onlinelibrary.wiley.com/doi/full/10.1029/2011JD016961.

[37] NASA Jet Propulsion Laboratory, “Nature, Chinese Pollution Offset U.S. West Ozone Gains,” August 10, 2015. Available at: https://www.jpl.nasa.gov/news/nature-chinese-pollution-offset-us-west-ozone-gains.

[38] Figure is from p. 1630 of L. Zhang, D. J. Jacob, et al., “Transpacific Transport of Ozone Pollution and the Effect of Recent Asian Emission Increases on Air Quality in North America: An Integrated Analysis Using Satellite, Aircraft, Ozonesonde, and Surface Observations,” Atmospheric Chemistry and Physics, 8: 6117–6136, October 22, 2008. Available at: https://acp.copernicus.org/articles/8/6117/2008/.

[39] Colette L. Heald, Daniel J. Jacob, et al., “Transpacific Transport of Asian Anthropogenic Aerosols and Its Impact on Surface Air Quality in the United States,” Journal of Geophysical Research: Atmospheres, 111: July 22, 2006. Available at: https://agupubs.onlinelibrary.wiley.com/doi/full/10.1029/2005JD006847; OL. Hadleyet al., “TransPacific transport of black carbon and fine aerosols (D < 2.5 μm) into North America,” Journal of Geophysical Research: Atmospheres, 112: 2007. Available at: https://agupubs.onlinelibrary.wiley.com/doi/full/10.1029/2006JD007632; Zhiyuan Hu, Jianping Huang, et al., “TransPacific Transport and Evolution of Aerosols: Spatiotemporal Characteristics and Source Contributions,” Atmospheric Chemistry and Physics, 19: 12709–12727, 2019. Available at: https://acp.copernicus.org/articles/19/12709/2019; Junfeng Liu, Denise Leonore Mauzerall, and Larry W. Horowitz, “Evaluating inter-continental transport of fine aerosols: (2) Global health impact,” Atmospheric Environment, 43(28: 4339–4347, 2009. Available at: https://collaborate.princeton.edu/en/publications/evaluating-inter-continental-transport-of-fine-aerosols2-global-h/.

[40] Sarah A. Strode, Lyatt Jaeglé, et al., “TransPacific transport of mercury,” Journal of Geophysical Research: Atmospheres, 113: August 7, 2008. Available at: https://agupubs.onlinelibrary.wiley.com/doi/full/10.1029/2007JD009428; ScienceDirect, “Export of Atmospheric Mercury from Asia,” 2025. Available at: https://www.sciencedirect.com/science/article/abs/pii/S1352231005001159.

[41] David Kirby, “Made in China: Our Toxic, Imported Air Pollution,” Discover, March 17, 2011. Available at: https://www.discovermagazine.com/made-in-china-our-toxic-imported-air-pollution-3125.  

Free Training

Source link

Metal Tariff Relief: US Manufacturing Policy Guide


Current Trade Policy Challenges in US Manufacturing Supply Chains

The intersection of international trade policies and domestic manufacturing capacity has become increasingly complex in recent years, particularly affecting industries that rely heavily on imported raw materials. Trade relationships with traditional allies now face scrutiny through various tariff mechanisms, creating ripple effects throughout US supply chains. Understanding how these policy frameworks operate and their downstream impacts on consumer goods provides crucial insight into the broader economic implications of current trade strategies.

Metal tariff relief has emerged as a critical policy consideration for maintaining competitive manufacturing sectors while balancing national security concerns. Furthermore, the tension between protecting domestic production and ensuring access to essential materials highlights the complexity of modern trade policy implementation. The relationship between US tariffs and inflation demonstrates how these policies affect broader economic conditions beyond their intended targets.

Join thousands of readers who start here

Our best articles, sent straight to your inbox. You can unsubscribe anytime.

Current Tariff Framework Architecture

The United States operates multiple tariff systems that affect metal imports, each serving different policy objectives. Section 232 provisions focus on national security considerations for steel and aluminum imports, while Section 301 mechanisms target specific trading relationships. These frameworks create a complex regulatory environment where manufacturers must navigate various exclusion processes to access essential materials.

The exclusion request process involves detailed documentation requirements, extended review periods, and uncertain approval outcomes. Companies must demonstrate that domestic alternatives are unavailable or insufficient to meet their production needs. However, this administrative burden often disproportionately affects smaller manufacturers who lack the resources to manage complex regulatory submissions.

Strategic Exemptions vs. Blanket Protection

Policy makers must balance broad industry protection with targeted relief for critical supply chains. Strategic exemptions allow for nuanced approaches that consider specific manufacturing needs while maintaining overall trade policy objectives. This approach recognizes that certain industries require imported materials to maintain competitiveness and consumer affordability.

The challenge lies in creating clear criteria for exemptions that prevent abuse while ensuring legitimate manufacturing needs are met. Industries with strong national security implications or significant consumer impact often receive priority consideration in exemption processes. In addition, understanding tariffs’ investment impacts helps policymakers assess the broader economic consequences of their decisions.

Supply Chain Vulnerabilities in Food Packaging Industries

Domestic Production Capacity Decline

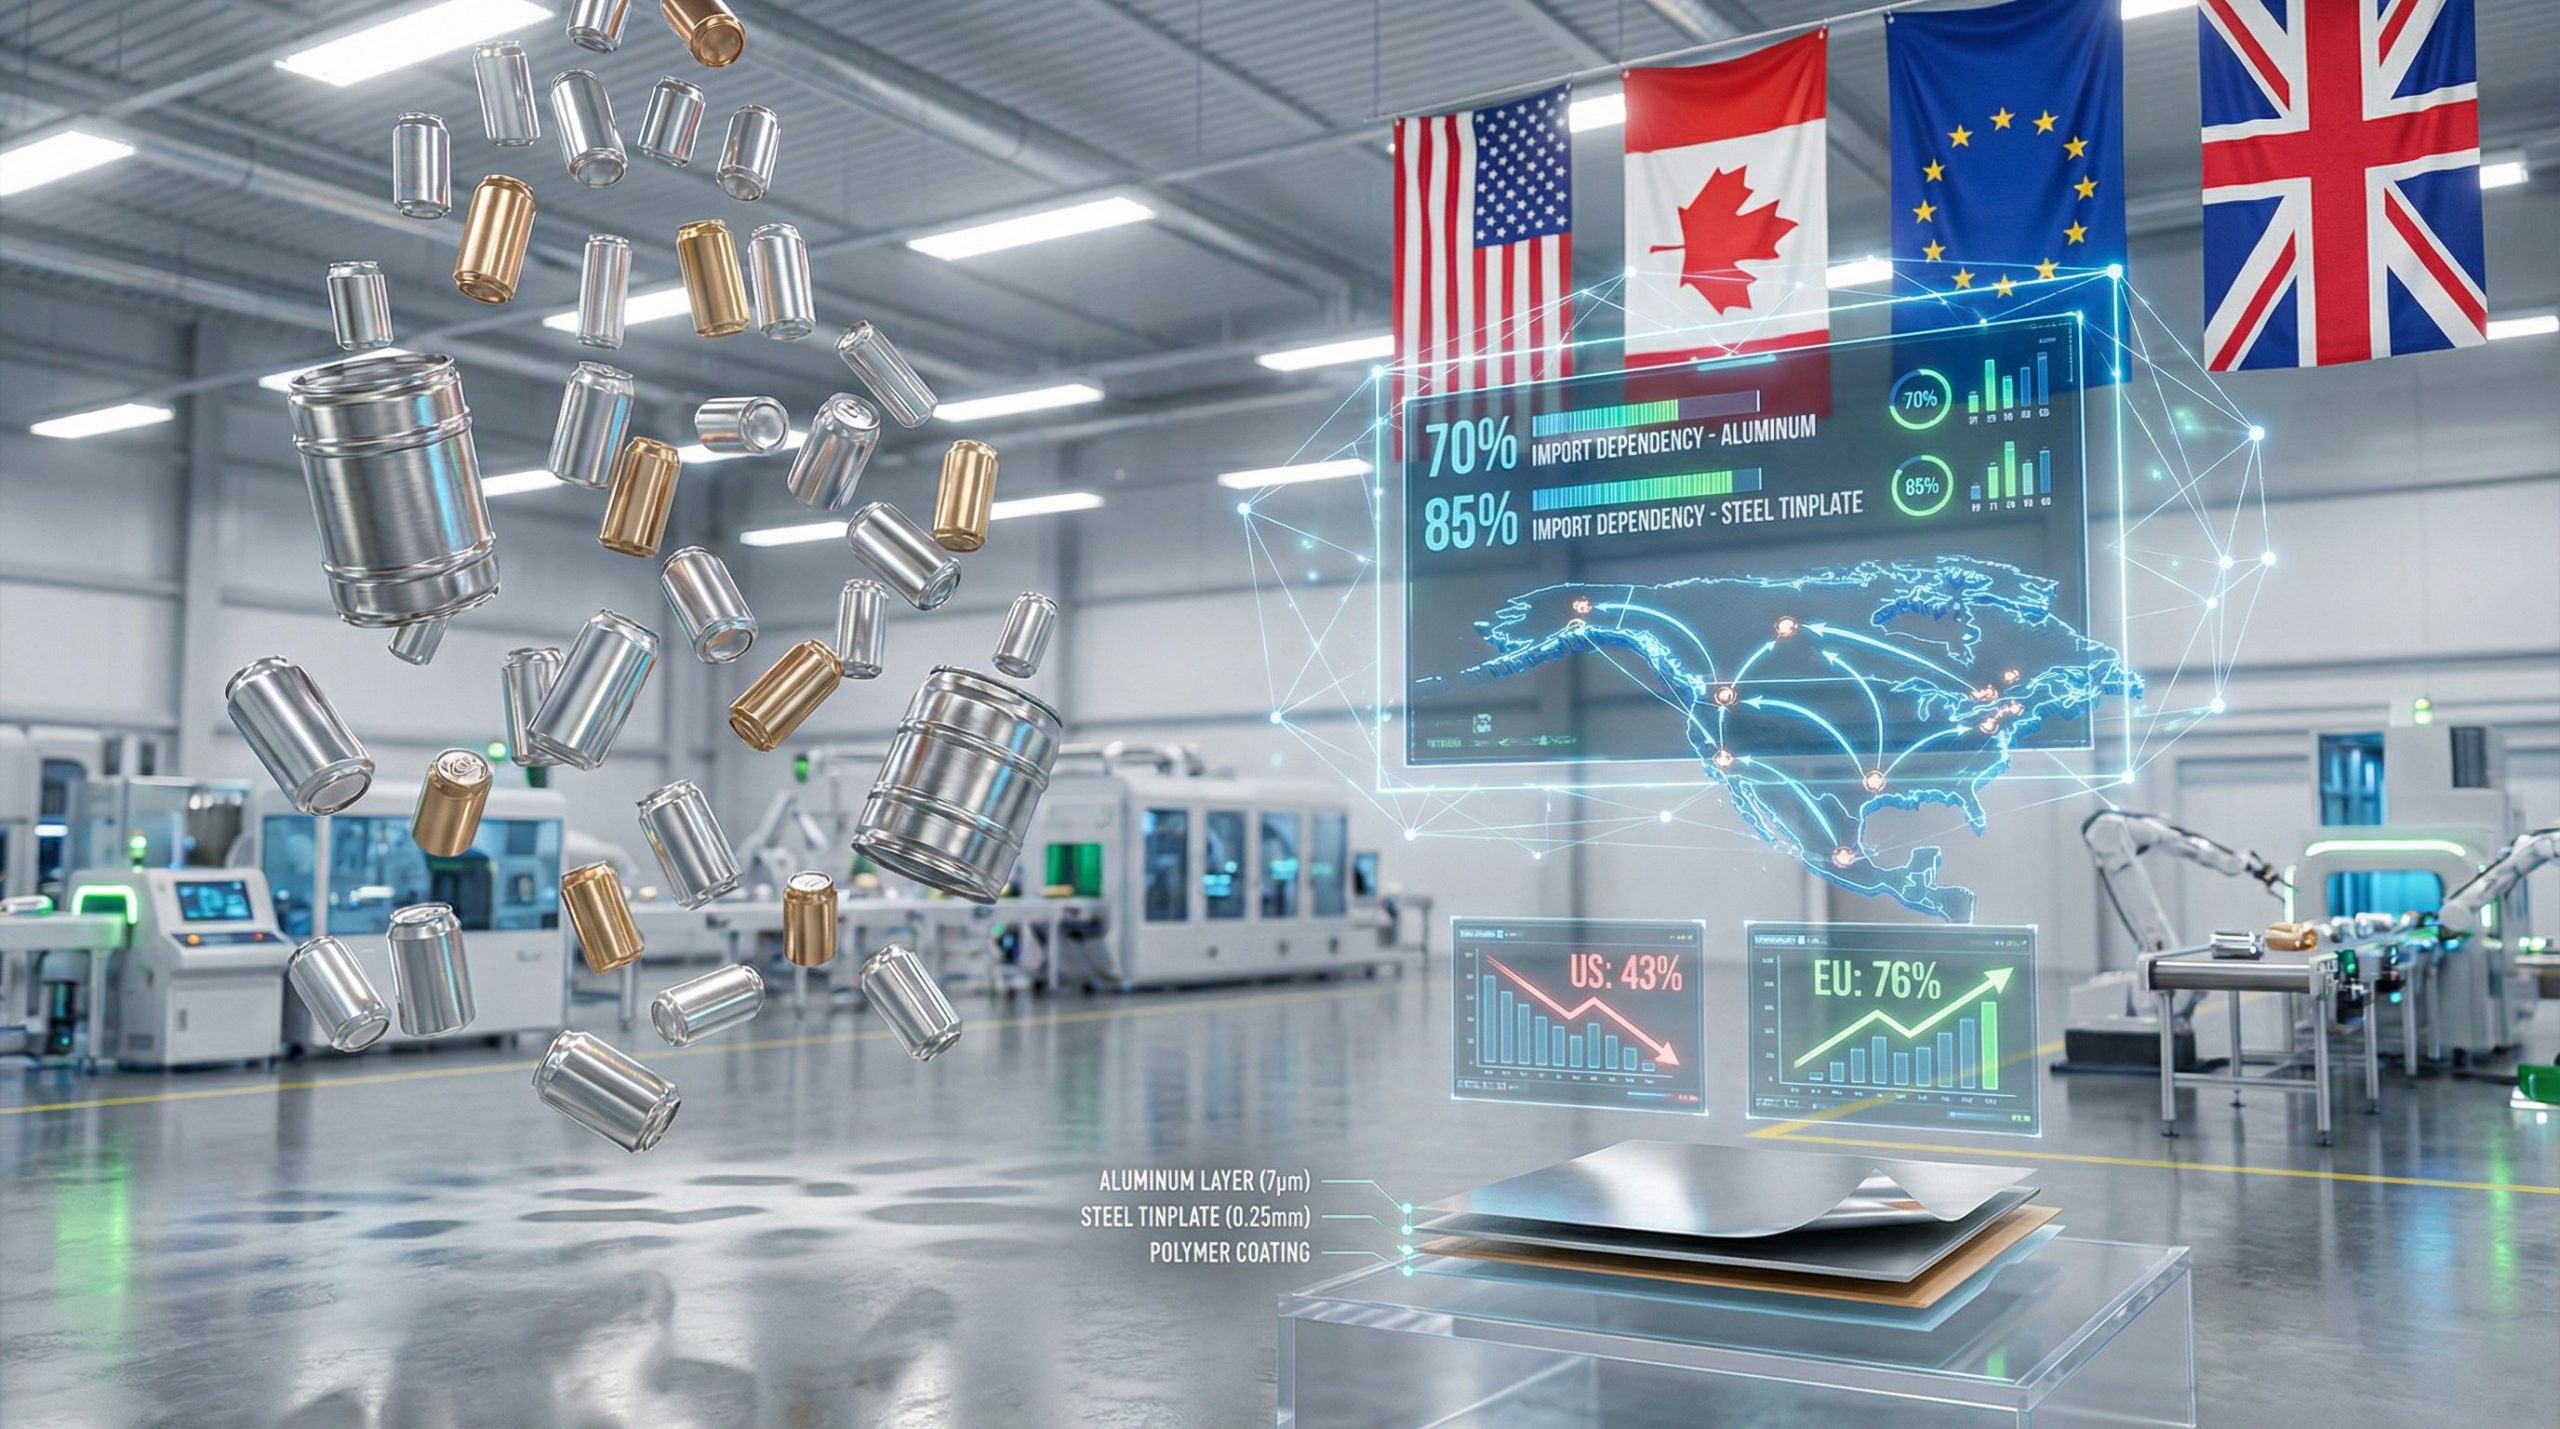
The can manufacturing sector illustrates how trade policies can affect domestic production capacity over time. According to industry data, domestic steel tinplate production has experienced dramatic consolidation, with operational lines decreasing from 12 to just 3 between 2018 and 2026. This reduction represents a fundamental shift in the industry’s production landscape and highlights the vulnerability of domestic supply chains.

The decline in domestic capacity forces manufacturers to rely increasingly on imports from traditional trading partners including Canada, the United Kingdom, and European Union nations. This dependency creates potential supply chain risks during periods of trade tension or international disruptions. Furthermore, the EU expects US to ease impact of metals tariffs in coming negotiations.

Production Metric
2018 Baseline
2026 Current
Change

Steel Tinplate Lines
12
3
-75%

Import Dependency
Moderate
High
Significant increase

Supply Chain Risk
Low
Elevated
Substantial change

Material Import Dependencies

The food packaging industry relies heavily on specialised materials that meet strict food safety standards. Aluminium for beverage cans and steel tinplate for food cans require specific metallurgical properties and certifications that limit the number of qualified suppliers globally.

These materials often come from established trading partners with proven quality systems and regulatory compliance. Disrupting these supply relationships through tariff policies can create immediate challenges for food manufacturers who need consistent material specifications to maintain product safety and quality. Consequently, US manufacturers advocate for metal tariff relief to address rising costs.

Consumer Price Impact Mechanisms

When material costs increase due to tariffs, food manufacturers face difficult decisions about price absorption versus consumer price increases. The food packaging industry operates on relatively thin margins, making it challenging to absorb significant material cost increases without affecting retail prices.

Regional variations in pricing can emerge based on proximity to remaining domestic production facilities versus import-dependent markets. This geographic disparity can create competitive advantages for manufacturers located near domestic supply sources while penalising those in import-dependent regions.

Legislative Approaches to Tariff Reform

STEWARD Act Environmental Data Enhancement

The STEWARD Act represents a comprehensive approach to improving recycling programme data collection and reporting. This legislation would require the Environmental Protection Agency to enhance its data gathering capabilities for recycling and composting programmes nationwide, creating better visibility into material flows and recovery rates.

Improved data collection would enable policy makers to make more informed decisions about material flows and identify opportunities for domestic capacity expansion. The legislation recognises that effective recycling policy requires accurate baseline data and standardised reporting mechanisms.

CIRCLE Act Infrastructure Investment Incentives

The CIRCLE Act proposes tax credit mechanisms to stimulate private investment in recycling infrastructure. By providing financial incentives for qualifying projects, this legislation aims to expand domestic processing capacity and reduce reliance on virgin material imports.

Tax credit programmes can accelerate infrastructure development by improving project economics for private investors. The challenge lies in structuring credits that generate meaningful capacity increases while ensuring public benefit from the tax expenditure. Moreover, these initiatives align with recycling transition strategies being implemented across various industries.

Industry-Specific Relief Proposals

Targeted relief for specific industries requires careful consideration of supply chain characteristics and national security implications. Food packaging materials, for example, have different risk profiles compared to general industrial applications.

Relief proposals must balance immediate industry needs with longer-term domestic capacity development goals. Temporary measures may provide necessary transition time for domestic capacity expansion while ensuring continued manufacturing competitiveness.

Global Recycling Performance Comparisons

Regional Recycling Rate Analysis

The United States significantly lags behind European nations in metal can recycling performance, with aluminium beverage cans achieving only 43% recycling rates compared to 76% in the European Union. Steel can recycling shows similar disparities, with US rates of 44% trailing European performance substantially.

Region
Aluminium Cans
Steel Cans
Policy Framework

United States
43%
44%
Voluntary programmes

European Union
76%
Not specified*
Extended producer responsibility

*Note: The 76% figure represents overall performance for EU, UK, Switzerland, Norway, and Iceland without material-specific breakdowns.

Infrastructure Investment Requirements

Achieving European-level recycling performance would require substantial infrastructure modernisation across collection, sorting, and processing systems. The investment needed extends beyond facility upgrades to include workforce development and consumer education programmes.

Collection system improvements represent a critical bottleneck in US recycling performance. Many regions lack the infrastructure density needed to capture materials efficiently, particularly in rural and suburban areas where transportation costs become prohibitive.

Processing facility modernisation involves both technology upgrades and capacity expansion. Advanced sorting systems and contamination reduction technologies could significantly improve material recovery rates and quality.

Extended Producer Responsibility vs. Voluntary Programmes

European recycling success stems largely from extended producer responsibility frameworks that create financial incentives for manufacturers to design recyclable products and support collection infrastructure. These systems internalise environmental costs into product pricing and create sustainable funding mechanisms for recycling programmes.

Voluntary programmes, while offering implementation flexibility, often struggle to achieve comprehensive coverage and consistent performance. Market-based incentives may not align with optimal environmental outcomes without regulatory frameworks to ensure participation.

Economic Impact Assessment of Current Tariff Policies

Manufacturing Sector Analysis

The Can Manufacturers Institute represents companies generating over $13 billion in annual economic activity, highlighting the significant economic scale affected by metal tariff policies. This economic impact extends beyond direct manufacturing to include suppliers, logistics providers, and supporting service industries.

Regional concentration in manufacturing corridors means that tariff impacts are geographically clustered, potentially affecting entire regional economies. Areas dependent on metal manufacturing face multiplied effects when primary industries experience cost pressures or capacity reductions. The broader implications of Trump’s tariff policies continue to influence these regional dynamics.

Employment and Workforce Considerations

Manufacturing employment in metal-intensive industries faces pressure from both automation trends and trade policy impacts. While tariffs may protect some domestic jobs in primary metal production, downstream manufacturing employment may decline due to higher input costs and reduced competitiveness.

Workforce development programmes must account for changing skill requirements as domestic production methods evolve. Investment in training and education becomes critical for maintaining competitive manufacturing capabilities.

Long-term Competitiveness Factors

Sustaining competitive manufacturing requires balancing short-term protection with long-term innovation and efficiency improvements. Metal tariff relief policies must consider how temporary measures can support transition to more sustainable competitive positions.

Technology transfer opportunities from international partnerships may be affected by trade tensions, potentially limiting access to advanced manufacturing techniques and process improvements. For instance, US–China trade impacts continue to shape global manufacturing relationships.

Section 232 Exclusion Procedures

Companies seeking relief from steel and aluminium tariffs must navigate complex exclusion request procedures with uncertain outcomes. The documentation requirements involve detailed supply chain analysis, domestic availability assessments, and economic impact projections.

Processing timelines can extend over several months, creating planning challenges for manufacturers with time-sensitive production schedules. The uncertainty around approval decisions complicates inventory management and long-term sourcing strategies.

Alternative Sourcing Documentation

Successful exclusion requests often require comprehensive demonstration that domestic alternatives are inadequate for specific applications. This documentation process involves technical specifications, quality certifications, and capacity availability assessments.

Manufacturers must maintain detailed records of sourcing attempts and supplier capabilities to support exclusion requests. This administrative burden requires dedicated resources and expertise in regulatory compliance.

Policy Development Trajectories

The evolution of metal tariff policies will likely reflect broader trade relationship developments with key allies and competitors. Changes in international agreements and bilateral relationships could significantly affect current tariff structures.

Administrative transitions may bring different approaches to balancing protection and competitiveness objectives. Industry stakeholders must prepare for potential policy shifts while advocating for stable, predictable regulatory environments.

Circular Economy Integration Opportunities

Developing domestic recycling capacity represents a potential pathway for reducing import dependencies while supporting environmental objectives. Investment in circular economy infrastructure could address both trade and sustainability policy goals simultaneously.

Metal recycling technologies continue advancing, potentially making domestic secondary production more competitive with imports. These technological improvements could support both environmental and trade policy objectives.

International Partnership Strategies

Maintaining productive trade relationships with traditional allies requires careful balance between protection and cooperation. Metal tariff relief policies should consider how trade measures affect broader strategic partnerships and security cooperation.

Multilateral approaches to trade challenges may offer more sustainable solutions than unilateral measures, particularly for industries dependent on complex international supply chains.

Enjoyed this article?

We publish high-impact stories like this a few times a week. No spam.

Strategic Recommendations for Policy Framework Development

Targeted Relief Implementation

Effective metal tariff relief requires nuanced approaches that consider specific industry characteristics and supply chain requirements. Food packaging industries, for example, have different risk profiles and consumer impact considerations compared to general industrial applications.

Policy mechanisms should provide clear criteria and predictable processes for relief requests. Transparency in decision-making helps manufacturers make informed planning decisions and reduces regulatory uncertainty.

Infrastructure Investment Coordination

Recycling infrastructure development requires coordinated investment across public and private sectors. Tax incentive programmes must align with regulatory frameworks and local development priorities to maximise effectiveness.

Regional coordination becomes important for achieving efficient collection and processing networks. Interstate cooperation may be necessary for developing economically viable recycling systems in smaller markets.

International Partnership Preservation

Trade policies should consider long-term strategic relationships with key allies and trading partners. Metal tariff relief mechanisms can demonstrate commitment to collaborative approaches while addressing domestic industry concerns.

Bilateral and multilateral engagement on trade issues helps maintain productive relationships that support broader security and economic cooperation objectives.

The complexity of metal tariff relief policies requires careful balance between competing objectives including domestic industry protection, consumer affordability, environmental sustainability, and international partnership maintenance. Success depends on developing nuanced approaches that recognise specific industry needs while supporting broader economic and strategic goals.

This analysis is based on publicly available information and industry statements. Trade policy developments continue evolving, and readers should consult current regulatory guidance for specific compliance requirements. Investment and business decisions should consider multiple factors beyond trade policy considerations.

Discovery Alert’s proprietary Discovery IQ model delivers real-time alerts on significant ASX mineral discoveries, instantly empowering subscribers to identify actionable opportunities in critical metals markets ahead of broader market awareness. Begin your 14-day free trial today to position yourself strategically as global supply chain dynamics create new investment landscapes in the mining sector.

Free Training

Source link

How Smart Policy Attracts Manufacturing Investment


Policymakers can use two basic strategies to attract manufacturing investments. These involve attractive incentives — the carrot — which include subsidies, grants and tax credits, or negative incentives — the stick — which include tariffs and threats.

Using credible data that tells a compelling story, I will explain why the carrot has been and will continue to be much more effective than the stick in attracting manufacturing investment.

The data

The St. Louis Federal Reserve publishes US Census Bureau data on actual investments in new or expanded manufacturing facilities, titled “Total Construction Spending: Manufacturing in the United States.” It is seasonally adjusted and reported monthly on an annualized basis.

During the Biden administration, manufacturing construction spending tripled from $76.5 billion in January 2021 to $230.9 billion in January 2025. This represented one of the largest industrial construction booms in US history, driven primarily by large semiconductor, battery and advanced manufacturing projects.

Due to normal megaproject investment cycles, these projects are front-loaded with capital-intensive spending on site preparation, foundation work and structural construction, using massive volumes of concrete and steel. Consequently, manufacturing construction spending peaked in June 2024 at $240.1 billion and slowed in later phases due to less capital-intensive spending on machinery, equipment and installation, much of which is recorded outside of the St. Louis Fed’s manufacturing construction spending data.

The carrot

Using subsidies, grants, loans, tax credits and state incentives, the CHIPS and Science Act signed by President Joe Biden in August 2022 attracted large amounts of capital into semiconductor manufacturing, spurring new fabrication plants and related infrastructure. It also created an entire ecosystem of suppliers, workers and innovation improving American competitiveness, and is primarily responsible for the manufacturing construction boom reflected in the St. Louis Federal Reserve data.

Stated by the Semiconductor Industry Association, enactment of the CHIPS and Science Act was a pivotal moment in recent American history, uniting government leaders from across the political spectrum to reinvigorate US semiconductor production and reinforce America’s economic strength, national security and technological competitiveness.

The carrot or positive incentives offered by the CHIPS and Science Act, combined with the Infrastructure Investment and Jobs Act, signed in November 2021, and the Inflation Reduction Act, signed in August 2022, boosted broader industrial and clean-energy facility investment. The message was clear: America is open for business, and we’re willing to invest in your success. This approach made investing in the US manufacturing sector very attractive.

The stick

Beginning with President Donald Trump’s second term through October 2025 (the latest available data), construction spending in manufacturing declined to $214.1 billion. Some of this is attributed to less capital-intensive spending in later phases, as explained above. However, the primary factor likely is trade uncertainty caused by President Trump’s on-again, off-again tariffs, delays, reversals and threats — the stick.

According to Anirban Basu, chief economist for the Associated Builders and Contractors, “With CHIPS Act-enabled megaprojects winding down and the stiff headwind of trade policy, manufacturing construction spending has fallen by nearly 10% over the past 12 months.”

There are many examples of stiff headwinds caused by erratic policies. Take South Korea, for example. On April 2, 2025, Liberation Day, President Trump announced tariffs of up to 25% on South Korea. Critics argued this was inconsistent with the United States–Korea Free Trade Agreement (KORUS FTA), which has been in force since March 15, 2012. Three months later, on July 30, 2025, the two countries announced and later finalized the Korea Strategic Trade and Investment Deal, which reduced tariffs to 15% and included the understanding that South Korea would invest $350 billion in the United States.

Two months later, on September 4, 2025, US Immigration and Customs Enforcement (ICE) raided the construction site of the South Korean-owned Hyundai Motor Group/LG Energy Solution battery plant in Ellabell, Georgia. ICE detained several hundred South Korean nationals, many of whom were engineers and technicians training American workers and installing specialized machinery. According to immigration attorney Charles Kuck, his South Korean clients were legally in the US under B-1 visitor visas or the Visa Waiver Program (ESTA).

Even though the Trump administration offered to allow the South Korean workers to remain in the United States to complete their work, most decided to leave due to the unpleasant experience of being shackled, treated like criminals and unsure if they could trust the visa process. In response, South Korean President Lee Jae Myung said, “Under the current circumstances, Korean companies will be very hesitant to make direct investments in the United States.”

The problems did not end here. In January 2026, President Trump announced that because the South Korean National Assembly had not yet passed implementing legislation for the 2025 deal, he would increase tariffs on Korean imports back up to 25%.

Uncertainty and the pause button

The chaotic tariffs and threats have caused economic uncertainty to skyrocket, costs to escalate and investors to be unable to predict what’s ahead. As a result of this and the Georgia immigration action, firms have become more cautious about committing to long-term capital projects in the United States and have hit the pause button.

Stated by Andrew Yeo, a senior fellow at the Brookings Institution, “Allies are receiving mixed signals. The South Korea case has made countries like Japan and even EU nations nervous.”

According to the American Institute of Architects’ January 2026 Consensus Construction Forecast, “Producers and investors typically have not had much clarity as to what countries, what products, or what tariff levels might be in place over the longer term. This makes decision-making difficult and often encourages inaction in supply chain sourcing and investment decisions.”

Not surprisingly, industry forecasts predict a continued decline in manufacturing construction spending.

A better approach

If the goal is to strengthen American manufacturing, US policy needs to focus more on carrots and less on sticks. The CHIPS Act demonstrates that positive incentives work. Expanding similar programs to attract capital to critical industries — advanced materials, batteries, clean energy and biotechnology — would help boost US competitiveness.

This approach is especially urgent given China’s relentless investment strategy and potential US-China hostility. The US cannot afford to cede its competitive advantages through policy uncertainty.

Importantly, strengthening relationships and working more closely with our allies to achieve our manufacturing goals would be an essential step in the right direction. America’s advanced semiconductor manufacturing depends on global supply chains. Alienating these partners through unpredictable tariffs and immigration raids undermines our own competitiveness.

The choice is clear: we can invest in our future through strategic incentives and stable partnerships or watch manufacturing investment go to more predictable shores. This may be a tall order today, but it will be necessary tomorrow.

[Kaitlyn Diana edited this piece.]

The views expressed in this article are the author’s own and do not necessarily reflect Fair Observer’s editorial policy.

Free Training

Source link

Has Trump’s tariff policy backfired, leading to a contraction in U.S. manufacturing?


The manufacturing boom promised by Trump has failed to materialize. Months after the implementation of his hallmark tariff policies, manufacturing jobs continue to decline, and industry activity has remained in prolonged contraction.

Trump once promised a ‘golden age’ for American manufacturing, but this prosperity is now receding. After years of economic intervention under both the Trump and Biden administrations, the number of manufacturing jobs in the United States has dropped to its lowest point since the end of the pandemic.

Federal data shows that in the eight months following Trump’s announcement of the ‘Liberation Day’ tariff, manufacturing jobs declined month by month, continuing a contraction trend that has seen over 200,000 jobs disappear since 2023. The index of factory activity tracked by the Institute for Supply Management remained in contraction territory for 26 consecutive months through December of last year, although a surprise rebound in new orders and production indexes in January caught analysts off guard. Manufacturing construction spending, which had surged under Biden-era funding for chips and renewable energy, fell month by month during Trump’s first nine months in office, according to estimates from the U.S. Census Bureau.

This gradual slowdown is, to some extent, a continuation of decades-long trends that shifted factory jobs overseas and accelerated the decline of Midwestern cities. In an industry where capital planning and construction cycles often span several years, reversing these trends will not happen overnight.

In November last year, the Federal Reserve significantly revised downward its estimates of total U.S. output since the pandemic when it conducted its annual revision of industrial production indicators.

“We never fully recovered from the pandemic,” said Josh Lehner, a U.S. economist at SGH Macro Advisors. Although automakers and chip manufacturers cut tens of thousands of jobs over the past year, the steady pace of layoffs across the industry suggests that job losses have been gradual.

Lehner and other economists also pointed out signs that output has stabilized and even grown slightly, though increased efficiency may limit the number of new jobs created. A White House spokesperson highlighted a modest rise in manufacturing productivity in recent quarters and noted that wage growth for workers exceeded inflation over the past year.

U.S. manufacturing jobs

U.S. manufacturing job additions

In the long run, tariffs may achieve their intended effect of enhancing the competitiveness of some manufacturers relative to overseas producers. Economists believe that lowering interest rates and deregulation could also provide support. However, in the short term, tariffs have raised costs for many companies importing raw materials and components, forcing businesses reliant on foreign parts to raise product prices or hurriedly seek alternative supplies.

The intermittent policymaking from the White House—Trump threatened new tariffs on Europe, Canada, and South Korea in recent weeks—has also led many business executives to view the past year as a ‘lost year for investment.’ The possibility that the Supreme Court might overturn some import taxes has added further uncertainty.

Meanwhile, despite the tariffs, some countries continue to expand their exports, driving down prices in the global market and making it difficult for U.S. manufacturers to compete.

“In our product portfolio, there are hardly any products that have benefited from tariffs,” said the CEO of Insteel Industries, headquartered in North Carolina.$Insteel Industries (IIIN.US)$H.O. Woltz III. With foreign steel tariffs doubling to 50% this year, Insteel has found it increasingly difficult to obtain steel from its U.S. suppliers for producing concrete infrastructure reinforcements, such as those required for the upcoming Gordie Howe Bridge connecting Detroit and Canada.$TRADELINK (00536.HK)$On the contrary, when domestic supply in the U.S. is insufficient, Insteel sometimes has no choice but to turn to importing tariffed steel from places like Algeria and India.

“Our growth today could be undermined by a lack of available (domestic) raw materials,” Woltz said.

In the trucking industry, a multi-year slump following the pandemic hit metal component manufacturers such as NN. The company, headquartered in Charlotte, North Carolina, and operating 23 plants across six countries, has cut its U.S. workforce in recent years to compete with low-cost factories overseas while addressing slowing demand for electric vehicles. CEO Harold Bevis believes tariffs will ultimately benefit NN by curbing competition from rivals in precision components like steering systems and audiovisual controls. However, import duties have driven up costs for steel and aluminum, while surging market prices for gold and silver—used in some of NN’s products—have added further pressure.

This squeezes the company’s ability to invest in new potentially profitable areas such as data centers and electrical equipment. “So you get hit,” Bevis said. NN is attempting to offset the costs by raising prices in subsequent orders. Bevis noted that NN’s business has accelerated amid Ford and General Motors’ push for localized sourcing, following multibillion-dollar asset write-downs on their EV businesses. However, when evaluating locations for expanding production for the auto sector, Bevis cautioned that places like Michigan and Massachusetts remain less attractive compared to Mexico, where many products can still enter the U.S. duty-free under trade agreements.

Trump has also taken other measures to try to revitalize manufacturing. He pressured trading partners like Japan and South Korea into agreements promising to invest tens of billions of dollars in the U.S.$Apple (AAPL.US)$ 、$Taiwan Semiconductor (TSM.US)$and$AstraZeneca (AZN.US)$Companies have announced large-scale projects that could create thousands of manufacturing jobs. Government officials stated that the long-term vision is achieving industrial self-sufficiency. However, these investments often span several years, leaving the short-term outlook for manufacturing uncertain. “I don’t know when all this money will start to pay off,” Trump told The Wall Street Journal in December last year.

Analysts pointed out that new investments might focus on areas that fascinate Wall Street, such as robotic tools and artificial intelligence components, meaning the likelihood of a surge in permanent factory jobs is low. After years of inflation and high borrowing costs, some sectors of the economy remain lagging, impacting certain types of manufacturing.$Qualcomm (QCOM.US)$After experiencing years of inflation and high borrowing costs, certain segments of the economy continue to lag behind, affecting specific types of manufacturing.

“If people aren’t buying homes, they won’t buy furniture,” said Meganne Wecker, CEO of Skyline Furniture Manufacturing, a family-owned business founded in 1946 located outside Chicago. Skyline ventured early into e-commerce and began sourcing metal materials domestically in 2018. However, tariffs have impacted hardwood imports from Vietnam and textiles from India and China, leading to price increases.

Wecker is more concerned about the impact of tariffs not directly on Skyline but on suppliers and retailers. “The entire industry feels somewhat fragile,” she said of the furniture sector, adding that tariff uncertainties have dampened prospects for new domestic capacity investment. “I don’t know anyone who feels confident enough to make an investment that might only last a few years.”

Some investors believe that interest rate cuts and stimulative fiscal policies should help accelerate economic growth this year. “The biggest overall factor determining how well manufacturing performs is how well our economy performs. There’s no escaping that,” said Scott Paul, president of the Alliance for American Manufacturing, which supports tariffs on steel and many products. “It’s too early to tell what the new normal will be because we’ve just come out of that roller-coaster period.”

Editor/Doris

Free Training

Source link