Mexico, The United States Saw Numerous Manufacturing Job Losses


Mexico’s Ministry of Economy reports that Mexico and the United States lost thousands of manufacturing jobs during the past year. While the historical discourse regarding nearshoring in Mexico has focused primarily on the volume of incoming investment the nation could secure, the narrative is shifting toward a more critical inquiry: the country’s capacity to maintain long-term employment levels.

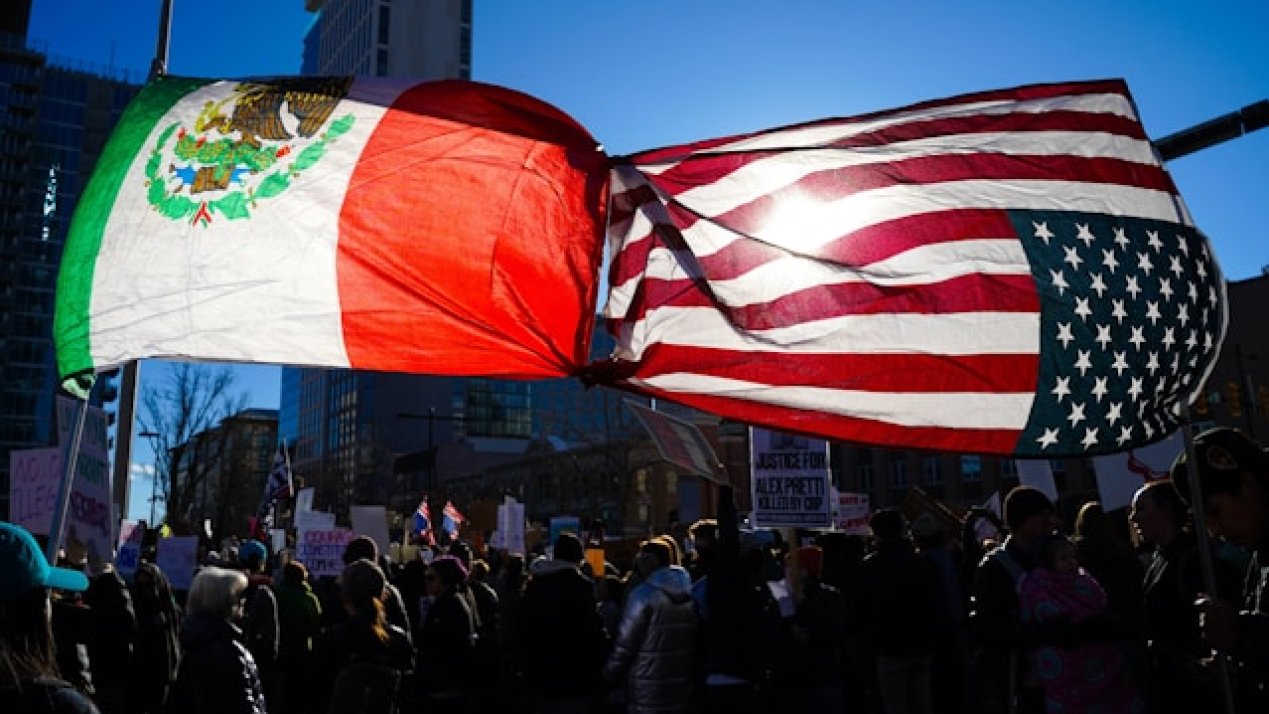
Recent data from Mexico’s Ministry of Economy reveals that Mexico and the United States lost more than 213,000 manufacturing jobs between February 2025 and February 2026, with the largest declines occurring in highly integrated sectors such as transportation equipment, plastics, rubber and machinery. The losses were concentrated in industries most exposed to recent tariff measures and trade uncertainty, highlighting the degree to which both countries now operate as a single manufacturing ecosystem. 

The impact was particularly severe in transportation equipment manufacturing, which lost nearly 65,000 jobs across Mexico and the United States in a single year, according to data cited by Mexico’s Ministry of Economy. The sector’s losses illustrate how trade disruptions increasingly affect not only production flows but also workforce stability across North America’s industrial ecosystem. 

The narrative often centers on tariffs, the underlying reality points to a fundamental shift redefining the competitiveness and labor landscape of Mexico. 

From Talent Availability to Workforce Resilience 

The first phase of nearshoring was defined by the relocation of production. The second focused on securing the talent needed to support industrial expansion. The next phase will be defined by workforce resilience: the ability to preserve critical skills, maintain productivity and adapt labor capacity during periods of economic, geopolitical, and regulatory disruption.

Mexico’s manufacturing success is increasingly tied to regional dynamics beyond its control. As the Ministry of Economy argued in its submission to US trade authorities, employment declines occurred almost simultaneously on both sides of the border, reflecting the deep integration of North American supply chains. Industries such as automotive, aerospace, electronics, and advanced manufacturing no longer operate as isolated national sectors but as interconnected production networks.


Historically, Mexico competed on labor costs. More recently, it competed on geographic proximity and access to the US market. Going forward, competitive advantage will increasingly depend on the resilience of its workforce ecosystem.

This shift is part of a broader global dialogue. The OECD highlights that geopolitical friction, regulatory changes, and economic instability are forcing governments and corporations to reconsider their supply chain strategies. Consequently, the focus is moving away from simple efficiency and toward resilience, prioritizing the capacity to withstand shocks while maintaining long-term productivity and expansion.

Within the Mexican landscape, the development of a resilient workforce is becoming the essential human capital equivalent to achieving supply chain security.

The challenge is particularly relevant as the country seeks to convert nearshoring momentum into sustainable industrial growth. Mexico continues to attract manufacturing investment, yet workforce vulnerabilities are becoming more visible. Talent shortages in engineering, digital technologies, and advanced manufacturing are already constraining industrial expansion and limiting the country’s ability to fully capitalize on nearshoring opportunities.


Mexico has successfully positioned itself as one of North America’s most attractive manufacturing destinations. However, attracting investment is not the same as protecting workforce capacity. If skilled workers exit key sectors during periods of uncertainty, rebuilding those capabilities can take years. The loss is not merely employment; it is accumulated knowledge, technical expertise, and future productivity. 

Workforce Stability as a Competitive Asset 

As a result, workforce strategy is becoming inseparable from business strategy. The core of corporate and national strategy is increasingly defined by workforce stability. For CEOs, the focus has shifted from the continuity of nearshoring to the preservation of access to essential talent amid periods of instability. Simultaneously, CHROs are finding that effective workforce planning now requires a scope beyond simple recruitment, prioritizing reskilling, internal mobility, and the protection of organizational capabilities to navigate volatility.

From an investment perspective, the resilience of the labor market is becoming a primary metric for evaluating long-term operational consistency. Geographies that demonstrate the ability to maintain talent ecosystems throughout various economic cycles will likely command greater interest for capital allocation. Policymakers face a parallel imperative; while industrial policies can bring physical facilities, maintaining a competitive edge necessitates deep, ongoing investments in technical education, workforce development, and retention strategies.

Looking ahead, the ultimate legacy of the nearshoring era in Mexico may not be measured by investment totals, but by the successful cultivation of a workforce capable of enduring global uncertainty. The future of Mexico’s competitiveness depends not just on manufacturing locations, but on the capacity to safeguard, modify, and enhance the human capital that drives the industrial sector.

Free Training

Source link

Ralph Lauren Invests in Domestic Fashion as U.S. Manufacturing Job Market Shrinks


Ralph Lauren and the Council of Fashion Designers of America is widening its financial commitment to domestic apparel production as new economic data underscore just how fragile American fashion manufacturing has become.

This week, the CFDA announced two new grant programs aimed at stabilizing and modernizing U.S.-based fashion manufacturing, extending its support well beyond New York City for the first time. The move comes as fresh analysis from Deloitte shows that apparel and textile manufacturing remain among the fastest-declining segments of the U.S. industrial economy, even as policymakers push to reshore production.

The first initiative, the CFDA x NY Forward Grant Fund, is a city-focused effort developed with funding from the New York State Department of State and Ralph Lauren Corp. It will provide partially matching grants to designers and manufacturers operating in New York City’s Garment District, an area that has steadily lost factories and skilled labor over the past two decades.

The second program, the U.S. Fashion Manufacturing Fund, represents a broader national expansion. Also created with Ralph Lauren as a founding partner, the new fund will operate from 2027 through 2029 and support manufacturers across key apparel-producing regions including California, New Jersey, North Carolina, South Carolina, Texas, and Florida. The program is structured to cover 80 percent of eligible investments, with recipients contributing the remaining 20 percent, and is designed to help manufacturers upgrade machinery, adopt advanced software, and invest in workforce training.

Rather than attempting to recreate the labor-intensive apparel sector that once defined American manufacturing, the CFDA is directing capital toward higher-value, technology-enabled production that can survive within a dramatically changed global economy.

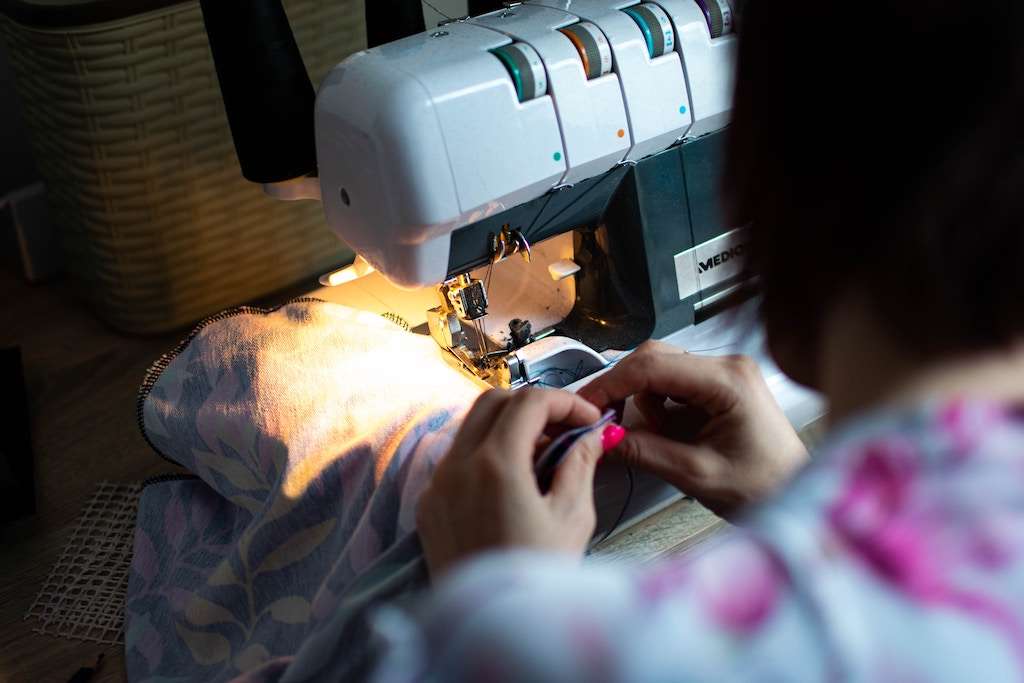
Hands at a sewing machine.Tomáš Petz

“Strengthening American manufacturing to ensure designers have local partners has long been at the core of CFDA’s mission,” Steven Kolb, chief executive officer and president of the CFDA, said in a statement. “We are proud to extend our decade-plus work with Ralph Lauren Corp. and expand to a national level while also continuing our local NYC investments alongside our first-ever partnership with the New York State Department of State.”

Ralph Lauren Corp. has been a central financial backer of the CFDA’s manufacturing efforts since 2013, when the organization launched its Fashion Manufacturing Initiative in partnership with the New York City Economic Development Corp. and industry executive Andrew Rosen. To date, Ralph Lauren has contributed $2 million as the initiative’s premier underwriter, enabling grants to 54 factories and supporting more than 2,000 jobs.

“Our expanded partnership with the CFDA reflects Ralph Lauren’s enduring commitment to advancing innovation and supporting American fashion,” said Katie Ioanilli, chief global impact and communications officer at Ralph Lauren Corp. “This is not only an investment in our industry — it’s an investment in a vital part of American culture that we share with the world.”

The renewed focus on modernization and training arrives as long-term economic trends continue to weigh heavily on apparel production. According to Deloitte’s Economics Insider series, real gross value added in U.S. manufacturing has grown at an average annual rate of 1.5 percent since 2000, compared with 2.1 percent growth across the broader economy. Manufacturing’s share of U.S. economic output stood at 9.4 percent in the second quarter of 2025, down from 15.1 percent 25 years earlier.

Within that contraction, apparel and textiles have been hit particularly hard. Deloitte data show that output in textile mills and textile product manufacturing has declined by an average of 2.9 percent per year since 2000, while apparel, leather, and allied products have fallen by an average of 2.2 percent annually. Employment losses have been even steeper, with apparel payrolls shrinking at an average rate of 6.8 percent per year over the same period.

By contrast, capital-intensive manufacturing sectors such as computer and electronic products have posted strong output growth, reinforcing a reality that CFDA leaders appear to be acknowledging: future domestic fashion manufacturing will depend less on scale and more on specialization, automation, and advanced skills.

The structure of the new grant programs mirrors that shift. Both funds are explicitly designed to help companies modernize equipment, expand technical services, and train workers in advanced production methods rather than increase headcount alone. The CFDA x NY Forward Grant Fund will distribute two rounds of funding in 2026 and 2027, with one manufacturer in each round also receiving the Ralph Lauren Manufacturing Award, which covers the full grant amount in recognition of innovation.

Woman in long coat.Ralph Lauren

New York State remains a focal point. In 2024, the state’s fashion industry was responsible for approximately $25 billion in wages, with New York City accounting for roughly $20 billion annually. Statewide, fashion employs about 315,000 people, including 204,000 jobs based in the city.

Ralph Lauren has also continued to anchor portions of its own production domestically, particularly through its role as Official Outfitter of Team USA. The company manufactures parade ceremony uniforms in the United States, including the opening and closing ceremony looks for the 2026 Milano Cortina Winter Olympic Games, work that has supported multiple American factories.

When asked about the potential for expanding U.S. production further, the company said, “We continue to explore and build additional opportunities to manufacture our products in the U.S. We value the wide range of production solutions that U.S. manufacturers can offer, from heritage craftsmanship to high-tech manufacturing like 3D printing. However, increasing domestic manufacturing is a complex process that requires ongoing collaboration across our sector, from how we collectively source raw materials to increasing existing domestic factory capacity to talent availability.”

The company added, “Working with factories across the country, we produce hundreds of thousands of products across all of our brands in the U.S.”

Deloitte’s analysis suggests that this kind of selective, high-value domestic production is likely to define the sector’s future. While tariffs and trade policy have renewed political interest in reshoring, the firm notes that manufacturing growth now hinges more on skilled labor, automation, and productivity than on sheer employment. As of September 2025, U.S. manufacturing payrolls totaled 12.7 million workers, down from 17.2 million in 2000, even as productivity has risen sharply.

Related on Ethos:

Free Training

Source link