NeoVolta Announces Strategic U.S. Battery Cell Supply and BESS Manufacturing Collaboration with SK On


Five-Year Agreement Secures 9 GWh of U.S.-Manufactured LFP Cell Supply for NeoVolta Power

Additional 9 GWh Cell Supply and Pack Purchase Arrangement, Under Which SK On Will Purchase Energy Storage Packs from NeoVolta Power From 2027 through 2031, Expanding Total Collaboration to 18 GWh

SAN DIEGO, Aug. 31, 2026 (GLOBE NEWSWIRE) — NeoVolta Inc. (NASDAQ: NEOV) (“NeoVolta” or the “Company”), a U.S.-based energy technology company delivering scalable energy storage solutions, today announced that its majority-owned subsidiary, NeoVolta Power, LLC (“NeoVolta Power”), has entered into a five-year strategic supply and manufacturing collaboration with SK On (“SK On”).

The collaboration begins with a signed agreement for SK On to supply 9 gigawatt-hours (“GWh”) of U.S.-manufactured lithium iron phosphate (“LFP”) battery cells to NeoVolta Power from 2027 through 2031. The agreement also establishes a framework for broader collaboration in which SK On will supply an additional 9 GWh of LFP cells to NeoVolta Power from 2027 through 2031, and NeoVolta Power will produce energy storage packs for purchase by SK On. Together, the initial cell-supply agreement and broader pack-manufacturing collaboration are expected to support up to 18 GWh of combined activity between the companies.

Key highlights

Get the latest news


delivered to your inbox

Sign up for The Manila Times newsletters

By signing up with an email address, I acknowledge that I have read and agree to the Terms of Service and Privacy Policy.

  • Long-term U.S. cell supply: The signed five-year agreement provides for 9 GWh of U.S.-manufactured LFP cell supply from SK On from 2027 through 2031, supporting NeoVolta Power’s Pendergrass production expansion.
  • Broader pack purchase collaboration: The parties have established a framework under which SK On will provide an additional 9 GWh of LFP cells, NeoVolta Power will produce energy storage packs to be purchased by SK On from 2027 through 2031.
  • Strategic manufacturing opportunity: The collaboration establishes SK On as a strategic supply chain partner and customer for NeoVolta Power’s domestic BESS manufacturing platform as demand for reliable, scalable power infrastructure grows across utility, commercial, industrial, AI data-center markets.
  • Capacity expansion potential: The scale and multi-year nature of the relationship support NeoVolta Power’s evaluation of additional production capacity at Pendergrass, including a second production line designed around pouch-format LFP cells.
  • Domestic supply-chain position: The collaboration advances NeoVolta Power’s strategy to pair U.S.-manufactured LFP cells with domestic BESS manufacturing for commercial, industrial and utility-scale BESS applications.

Strategic Collaboration

“This collaboration represents an important milestone in NeoVolta’s expansion into large-scale energy storage and the continued buildout of our U.S. manufacturing platform,” said Ardes Johnson, Chief Executive Officer of NeoVolta. “The initial agreement secures long-term access to U.S.-manufactured LFP cells for our Pendergrass production expansion, while the broader collaboration positions NeoVolta Power to manufacture energy storage packs for SK On. Together, these initiatives reinforce our strategy to build a domestic energy storage platform designed to meet growing demand for reliable, high-performance BESS solutions.”

The signed agreement establishes SK On as the primary cell supplier for NeoVolta Power’s LFP pouch-cell-based BESS products. The broader collaboration will leverage NeoVolta Power’s domestic manufacturing capabilities, with SK On supplying additional LFP cells for incorporation into battery energy storage packs designed and manufactured by NeoVolta Power and purchased by SK On.

“This partnership strengthens SK On’s position in the U.S. BESS market and brings together SK On’s U.S.-made LFP battery technology with NeoVolta Power’s growing energy storage manufacturing capabilities,” said Daejin Choi, Head of ESS Business at SK On. “We view NeoVolta Power as a strategic partner as we expand our presence in the U.S. energy storage market. By combining our respective capabilities, we will pursue new commercial opportunities and deliver competitive BESS solutions that meet evolving market needs.”

Domestic Manufacturing Platform

NeoVolta Power’s Pendergrass, Georgia facility is designed to manufacture BESS products for commercial, industrial and utility-scale applications. By pairing U.S.-manufactured LFP cells with U.S.-based battery BESS manufacturing, the Company believes its platform is positioned to serve customers seeking reliable and domestic content BESS solutions.

The Company’s initial Pendergrass production line remains on track to advance through commissioning and production-ramp activities. The multi-year strategic collaboration with SK On is expected to accelerate NeoVolta Power’s expansion from its initial Pendergrass production line to a two-line manufacturing platform targeting up to 8 GWh of annual BESS production capacity in 2028.

About NeoVolta

NeoVolta is an innovator in energy storage solutions dedicated to advancing reliable, high-performance power infrastructure for residential, commercial, and utility applications. With a focus on scalable technology, domestic manufacturing, and strategic partnerships, NeoVolta is positioned to support the accelerating transition toward resilient energy systems.

For more information, visit www.neovolta.com.

About SK On

SK On is a global leading battery & trading company committed to technological innovation for a better, sustainable future.

SK On aims to accelerate the green energy transition by leveraging its global production base and R&D capabilities, as well as its manufacturing and quality management know-how.

Headquartered in Seoul, South Korea, SK On has a worldwide presence with battery plants currently operating or in construction across the United States, Europe, and Asia.

For more information, visit: http://eng.sk-on.com/

Forward-Looking Statements

This press release contains forward-looking statements within the meaning of applicable federal securities laws. Forward-looking statements include, among other things, statements regarding anticipated battery-cell supply, future battery-pack purchases, the implementation of future order documents, production and delivery schedules, future manufacturing capacity, the potential establishment and timing of additional production lines, domestic-content and supply-chain characteristics, the availability or applicability of tax incentives and credits, customer demand, market opportunities, and the anticipated benefits and future opportunities associated with the relationship between NeoVolta Power and SK On.

Forward-looking statements are based on current expectations and assumptions and are subject to risks and uncertainties that could cause actual results to differ materially from those expressed or implied. These risks and uncertainties include, among others, risks related to the parties’ ability to finalize and implement future order documents and commercial terms; satisfy technical and product-specification requirements; execute production ramps; obtain financing; source materials; meet regulatory or tax-credit requirements; respond to changes in tariffs or raw-material prices; and other risks described in NeoVolta’s filings with the U.S. Securities and Exchange Commission. Readers are cautioned not to place undue reliance on forward-looking statements, which speak only as of the date made. NeoVolta undertakes no obligation to update these statements except as required by law.

Contacts

NEOV Investors

Bryan Baritot

Alliance Advisors IR

[email protected]  

NEOV Media

Email: [email protected]

Phone: 800-364-5464

Free Training

Source link

Forge Nano Breaks Ground on “America’s Battery Gigafactory” to Strengthen U.S. Defense Supply Chains


  • DOE-backed facility will expand to nearly 315,000 square feet, create more than 250 jobs and scale domestic battery manufacturing capacity to up to 3 GWh annually
  • Samsung SDI partnership brings strategic investment, manufacturing expertise and commercial support to Forge Nano’s U.S. battery manufacturing platform
  • Senator Ted Budd, Representative Deborah Ross, Morrisville Mayor TJ Cawley and Assistant Secretary of the Department of Energy Audrey Robertson joined Forge Nano to mark the company’s next phase of U.S. manufacturing growth

DENVER and MORRISVILLE, N.C., Aug. 19, 2026 (GLOBE NEWSWIRE) — Forge Nano, Inc., a leading U.S.-based semiconductor equipment and advanced materials company pioneering Atomic Layer Deposition (“ALD”) technology for artificial intelligence (“AI”)-era chip manufacturing and defense battery applications, which has signed an agreement to merge with Archimedes Tech SPAC Partners II Co. (“Archimedes II”) (NASDAQ: ATII), today celebrated the groundbreaking of a major expansion of its lithium-ion battery manufacturing facility in Morrisville, North Carolina.

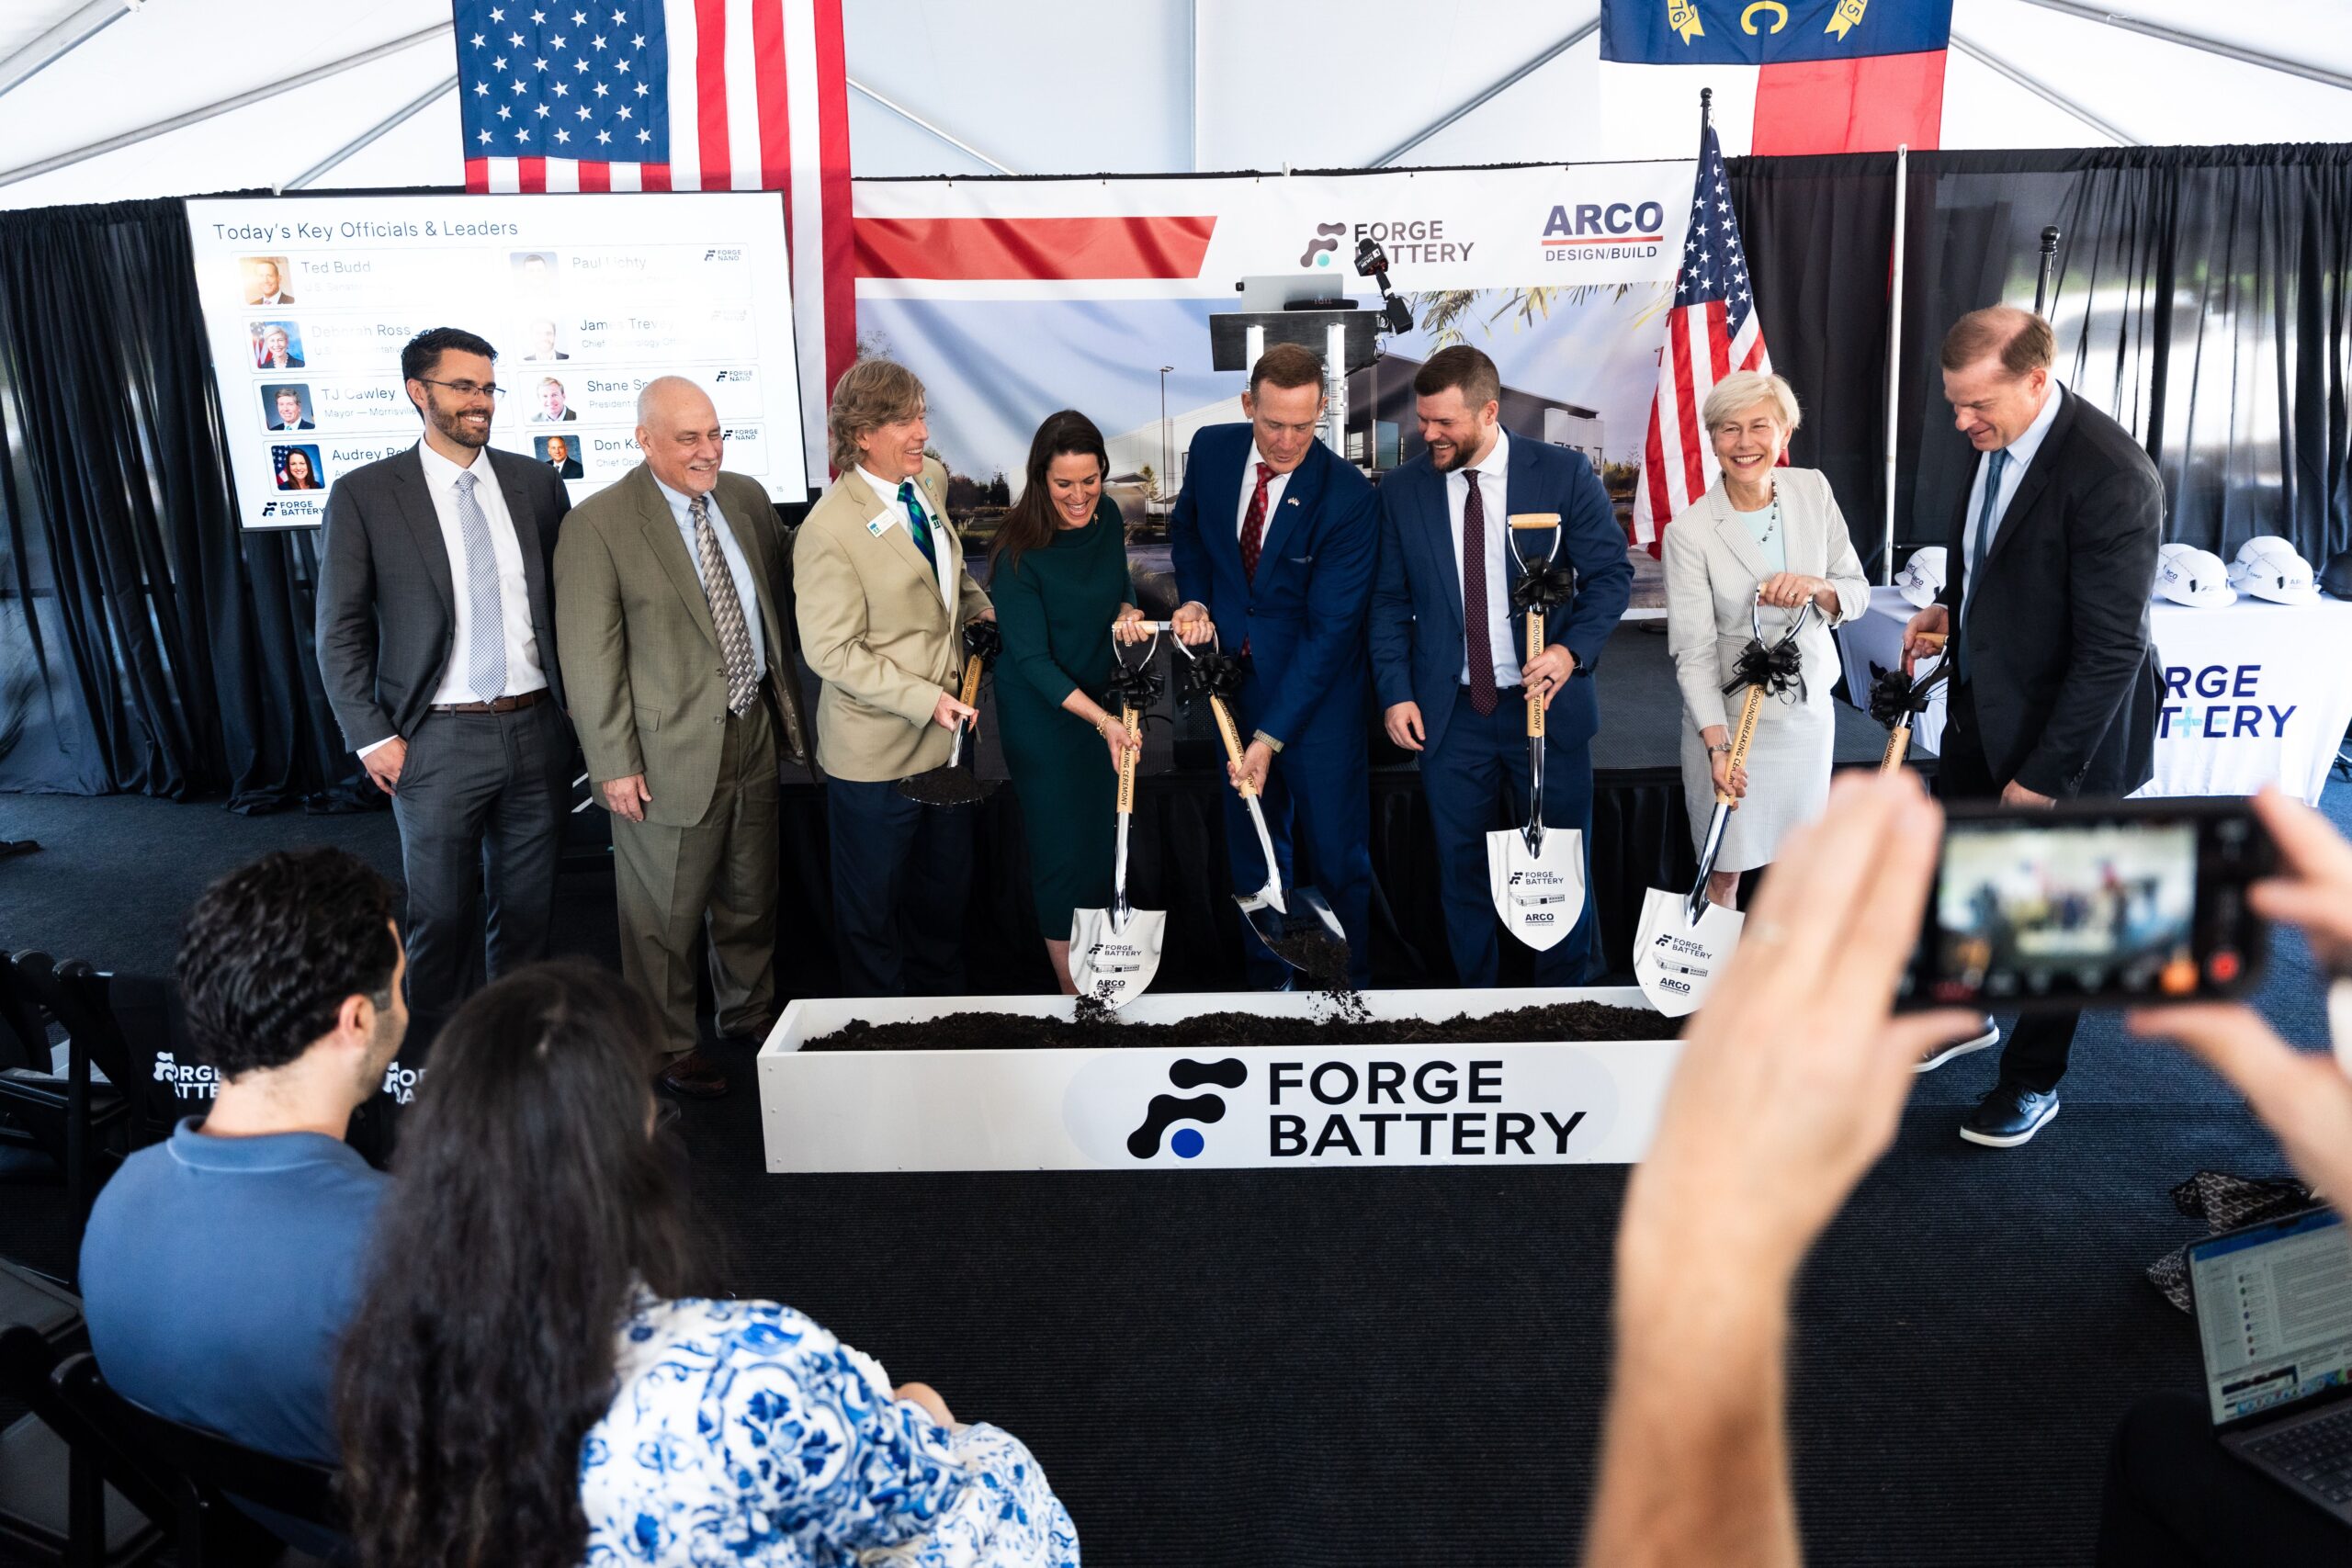
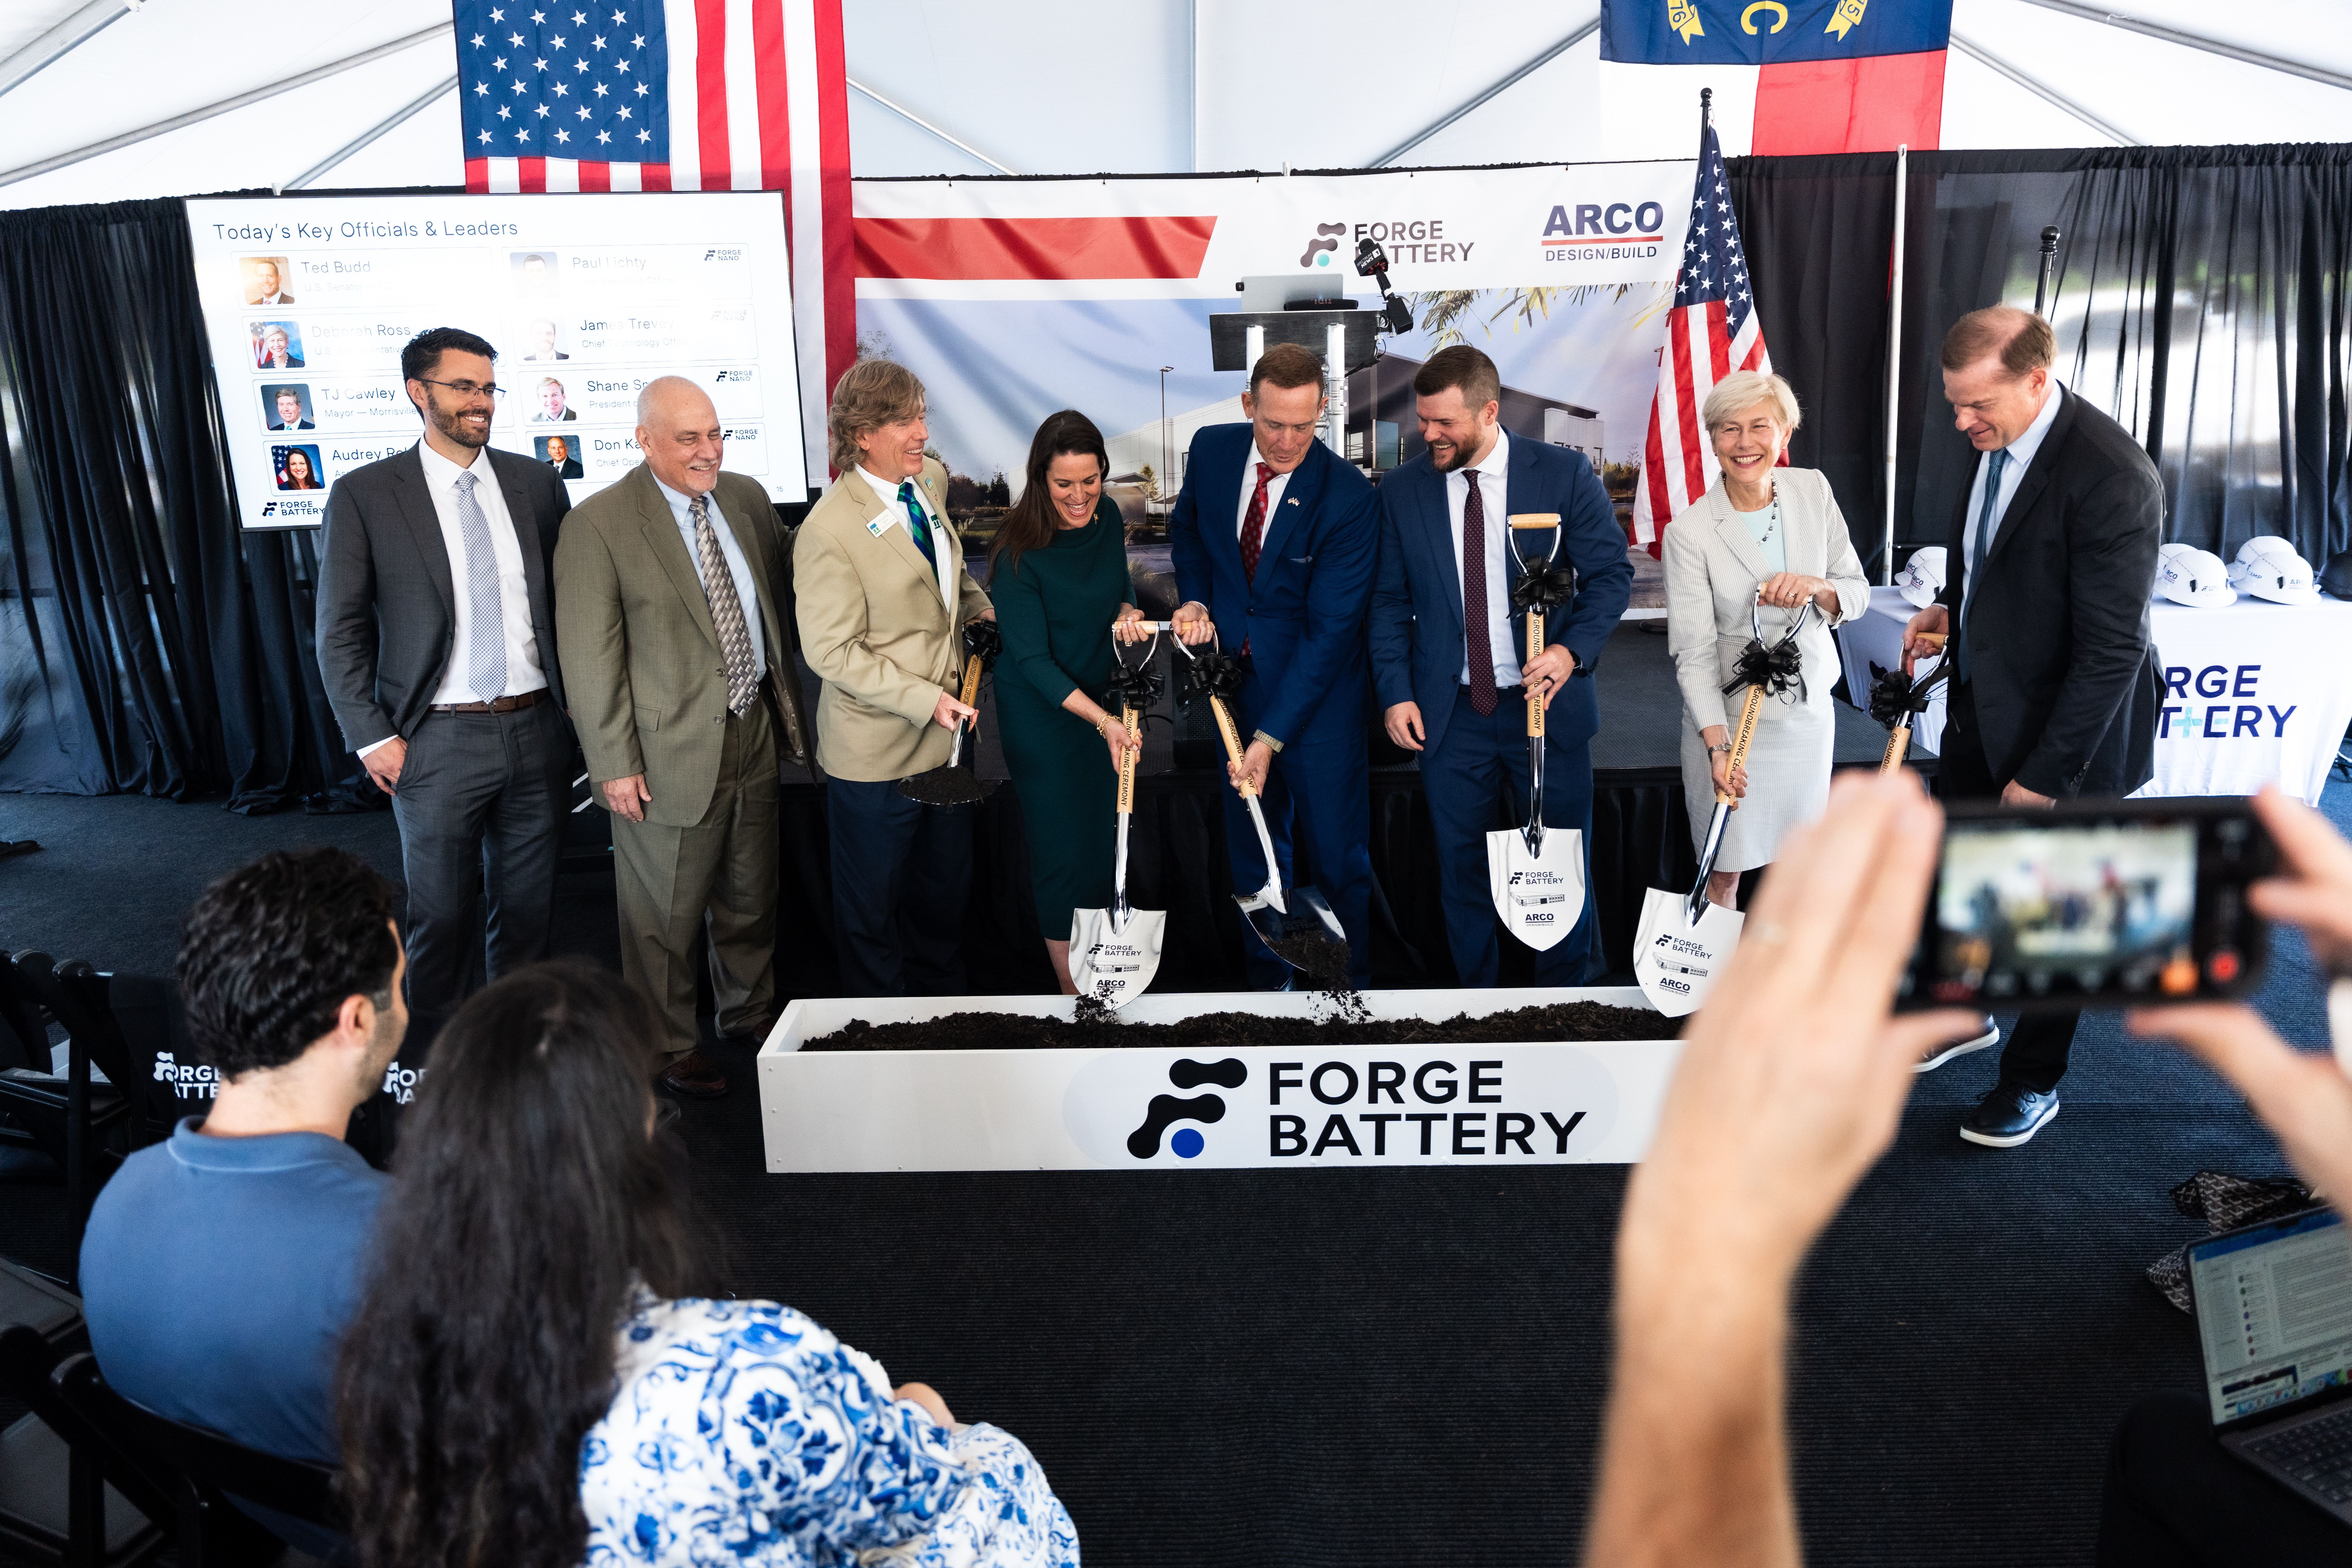
Forge Nano executive leadership team breaks ground on its Morrisville, NC lithium-ion battery manufacturing facility alongside North Carolina Senator Ted Budd, U.S. Representative Deborah Ross, Mayor of Morrisville TJ Cawley and the Assistant Secretary of the Department of Energy Audrey Robertson.

Forge Nano executive leadership team breaks ground on its Morrisville, NC lithium-ion battery manufacturing facility alongside North Carolina Senator Ted Budd, U.S. Representative Deborah Ross, Mayor of Morrisville TJ Cawley and the Assistant Secretary of the Department of Energy Audrey Robertson.

U.S. Senator Ted Budd, U.S. Representative Deborah Ross, Morrisville Mayor TJ Cawley and Assistant Secretary of the Department of Energy Audrey Robertson joined Forge Nano CEO Paul Lichty, employees, strategic partners and community leaders at the facility to mark the milestone and highlight the importance of expanding domestic battery manufacturing capacity for defense, aerospace and other critical U.S. markets.

The expansion will transform Forge Nano’s existing 100,000-square-foot Morrisville operation into a manufacturing campus approaching 315,000 square feet, create more than 250 jobs in North Carolina and establish approximately 3 gigawatt-hours (“GWh”) of annual battery cell manufacturing capacity at full production.

The facility is designed to address one of the most significant vulnerabilities facing the U.S. battery industry: the nation’s dependence on foreign-controlled supply chains for batteries used in applications critical to national security. Forge Nano’s Gigafactory is intended to establish a secure, U.S.-based manufacturing hub capable of supplying advanced lithium-ion batteries at scale.

“Today’s groundbreaking marks an important step toward building a battery supply chain in America,” said Paul Lichty, CEO of Forge Nano. “We’re combining Forge Nano’s technology with world-class manufacturing expertise, federal support and North Carolina’s growing advanced manufacturing ecosystem to bring critical battery production to the United States. America’s Battery Gigafactory will give defense, aerospace and commercial customers access to advanced battery cells manufactured here at home, at the scale needed to compete globally.”

The project is financed by up to $100 million in non-dilutive funding from the U.S. Department of Energy and reflects a collaborative effort among Forge Nano, federal and state partners and strategic industry collaborators to strengthen America’s domestic battery supply chain.

“Maintaining America’s technological edge requires strategic investment in our national security and commercial interests. Forge Nano’s new Morrisville facility will strengthen U.S. battery manufacturing capabilities—advancing American leadership in critical technologies, expanding domestic production, and helping us compete with China. North Carolina’s strong workforce and business climate make it an ideal place to grow this cutting-edge industry. This partnership will strengthen our domestic manufacturing base, create new opportunities for American workers, and keep North Carolina at the forefront of innovation,” said Senator Budd.

“North Carolina’s Research Triangle has long been a center for innovation, and investments like Forge Nano’s are helping translate that progress into advanced manufacturing and good-paying jobs here at home,” said Congresswoman Deborah Ross. “Expanding domestic battery production will drive economic growth, create jobs, support our clean energy transition, and strengthen America’s technology supply chain. I was proud to play a small role in bringing this expansion to life by passing the Bipartisan Infrastructure Law. I look forward to seeing how Morrisville and the Triangle continue leading the next generation of American manufacturing.”

“These batteries will not only serve commercial markets, but also the defense and aerospace applications on which our military depends,” said Assistant Secretary of Energy Audrey Robertson. “That is exactly the kind of manufacturing capacity our country needs. We need to build critical technologies in America. We need to support our armed forces with secure supply chains. And American companies should be able to compete and win in the industries that will define the decades ahead.”

Building Domestic Battery Capacity at Scale

Expansion construction is expected to begin imminently, with manufacturing equipment scheduled to be delivered over the next 2 years. Production at the facility is expected to begin in 2028.

At full production, 3 GWh represents approximately 150 million battery cells per year. Depending on customer demand and product mix, that capacity could support approximately 10–20 million drone batteries, 34,000 electric military vehicles, 6 million BB-2590 radio batteries, 900 6T (Type 2) batteries, or approximately 275 energy storage system containers annually.

The timing of the expansion is expected to align with new National Defense Authorization Act (“NDAA”) battery sourcing requirements taking effect in 2028, further increasing the need for secure domestic sources of advanced battery cells for defense applications.

Samsung SDI Partnership Supports U.S. Reshoring

A central component of Forge Nano’s U.S. battery manufacturing strategy is its strategic partnership with Samsung SDI, one of the world’s leading battery manufacturers.

Samsung SDI is supporting Forge Nano in establishing and beginning operations at the Morrisville facility, providing operational and manufacturing expertise for high-throughput battery production. Once the Gigafactory is operational, Forge Nano expects to manufacture Samsung SDI battery cells alongside Forge Nano’s existing cell products in North Carolina.

Samsung SDI has also entered into a conditional procurement agreement to purchase cells manufactured at the Gigafactory beginning in 2028, while Forge Nano is a contract manufacturer and an authorized distributor of Samsung SDI battery cells in the U.S. market.

The companies are also working to advance the incorporation of Forge Nano’s proprietary Atomic Armor® technology into future Samsung SDI battery products.

Samsung SDI further strengthened the partnership in July through a $20 million strategic investment in Forge Nano, including $10 million in Forge Nano’s Series D financing and $10 million in the company’s PIPE financing associated with its planned public listing.

Investing in North Carolina’s Advanced Manufacturing Workforce

Forge Nano selected North Carolina for the expansion based on the state’s growing advanced manufacturing ecosystem, its pipeline of skilled workers from universities, community colleges and technical programs, competitive state and local incentives and its strong support for companies investing in advanced U.S. manufacturing.

The Morrisville location also positions Forge Nano within the Research Triangle’s deep technical and engineering talent base and provides a strong logistical position for transporting battery cells to defense, aerospace, industrial and other customers.

As the Gigafactory ramps toward full production, Forge Nano expects the facility to create more than 250 jobs across advanced manufacturing, engineering, operations and technical roles.

The project represents a significant investment in both domestic battery manufacturing capacity and the workforce needed to sustain that capacity over the long term.

ABOUT FORGE NANO

Forge Nano is a leading U.S. based semiconductor equipment and advanced materials company pioneering Atomic Layer Deposition (“ALD”) technology for AI-era chip manufacturing and defense battery applications via its platform technology, Atomic Armor. Atomic Armor is a scalable, adaptable nano-scale coating system that strengthens America’s most critical systems – at the atomic level. The superior surface coatings produced by Forge Nano’s Atomic Armor process allow partners to unlock peak performance. Learn more at https://www.forgenano.com.
  
Contacts:

Media Contact
Will McKenna
Brand Communications Director, Forge Nano
wmckenna@forgenano.com

Investor Relations Contact
Bryan Baritot
Alliance Advisors IR
ForgeNanoIR@allianceadvisors.com

A photo accompanying this announcement is available at https://www.globenewswire.com/NewsRoom/AttachmentNg/42a740fd-7057-45f8-a33e-e3320da62ea0

Primary Logo

Free Training

Source link

Enphase Energy Expands U.S. Manufacturing for Solar, Battery and AI Data Center Power Electronics


Enphase Energy has reaffirmed its commitment to designing and manufacturing critical power electronics in the United States, expanding domestic production across residential and commercial solar, battery energy storage systems (BESS), and next-generation power infrastructure for artificial intelligence (AI) data centers.

Growatt

The company said it currently manufactures its IQ® Microinverters and IQ® Batteries at facilities in South Carolina and Texas, and plans to manufacture its upcoming IQ® Solid-State Transformer (IQ® SST) platform for AI data centers in the United States.

According to Enphase, the move supports U.S. energy security, strengthens domestic supply chains, and addresses the increasing importance of secure power electronics as electricity demand rises from electrification and the rapid growth of AI data centers.

The company noted that its U.S.-manufactured IQ Microinverters and IQ Batteries, identified with a “DOM” suffix, can help eligible solar and storage projects meet domestic sourcing requirements and qualify for U.S. domestic content tax incentives. Select products also comply with Buy American Act and Build America, Buy America requirements, while certain products may qualify as Foreign Entity of Concern (FEOC)-compliant for rooftop solar and distributed battery energy storage applications.

Enphase also plans to manufacture the power electronics for its forthcoming IQ® Bidirectional EV Charger in the United States, further expanding its domestic clean energy product portfolio.

The company’s upcoming IQ SST platform is designed for AI data centers and other high-power applications. Based on gallium nitride (GaN) technology, the platform will convert medium-voltage alternating current (AC) directly into 800 V direct current (DC) required by modern AI computing infrastructure through a modular architecture featuring distributed control, software intelligence, and built-in redundancy.

Enphase estimates that a 1 GW AI data center would require approximately 250,000 IQ SST power modules, excluding redundancy, while 10 GW of deployments could require around 2.5 million modules, highlighting the significant scale of future demand.

The company said its manufacturing experience provides a strong foundation for scaling the platform, having shipped approximately 89.4 million microinverters globally, including 5.5 million units manufactured in the United States during 2025.

While expanding U.S. manufacturing capabilities, Enphase emphasized that it remains committed to serving international markets, including Europe, Australia, India, and other regions, where it will continue developing products tailored to local grid requirements, regulations, and customer needs.

Discover more from SolarQuarter

Subscribe to get the latest posts sent to your email.

Free Training

Source link

Factorial And Sk On Explore Collaboration On Solid-State Battery Manufacturing


U.S.-based battery developer Factorial Energy and South Korean battery manufacturer SK On plan to collaborate on solid-state battery technology. The goal is to evaluate whether and how SK On’s existing manufacturing facilities could be used to produce solid-state batteries. The specific terms of the collaboration are expected to be defined in future agreements. The partnership will focus on the technical evaluation of Factorial’s FEST solid-state battery technology.

According to the companies, the collaboration will examine the manufacturing requirements for solid-state batteries and assess whether existing lithium-ion battery production lines are suitable for the technology. Factorial aims to pursue a capital-light approach by leveraging existing manufacturing infrastructure rather than building new production facilities.

SK On has an annual global production capacity of more than 200 GWh, including approximately 100 GWh in the United States. Its U.S. manufacturing footprint includes facilities in Commerce, Georgia, as well as operations in Tennessee.

The collaboration will initially focus on technical feasibility and manufacturing requirements. Whether it will lead to commercial-scale production remains uncertain. According to Factorial, this is the company’s first manufacturing-focused partnership with a global battery producer. The companies also plan to explore potential applications for solid-state batteries in mobility and other high-performance markets.

Source:https://factorialenergy.com/press-releases/factorial-and-sk-on-sign-mou-to-explore-solid-state-battery-manufacturing/

Free Training

Source link

Stryten’s C&D Trojan Deal Expands U.S. Battery Manufacturing


Stryten Energy has agreed to acquire C&D Technologies and Trojan Battery Company in a deal that would increase its U.S. manufacturing capacity and extend its reach across transportation, industrial and backup-power markets.

The companies announced the definitive agreement on July 13, 2026. Financial terms were not disclosed. The transaction is expected to close in the third quarter of 2026, subject to regulatory approvals and customary closing conditions.

Stryten President and CEO Mike Judd is expected to lead the combined business.

Deal Adds Manufacturing Capacity and New End Markets

Following the acquisition, Stryten expects to operate 15 battery and component manufacturing facilities in the United States, with a combined workforce of approximately 3,700 employees.

The larger production network could give the company more control over manufacturing, component sourcing and supply-chain planning. That may be particularly relevant as customers in infrastructure, defense and transportation place greater emphasis on domestic production and supply availability.

Stryten also plans to increase its capacity for absorbent glass mat batteries. AGM batteries are used in start-stop and hybrid vehicles, telecommunications equipment, data centers and other applications that require reliable backup power.

The transaction would also broaden Stryten’s customer base.

C&D Technologies supplies stationary battery systems for data centers, broadband networks, telecommunications providers, utilities and other critical infrastructure operators. Trojan Battery focuses on deep-cycle products used in golf carts, low-speed electric vehicles, aerial work platforms, floor-care equipment, recreational vehicles and marine applications.

Combining these operations would give Stryten exposure to a wider mix of transportation, motive-power and standby-power demand. Growth in data center construction, warehouse automation, hybrid vehicles and network infrastructure is creating additional demand for batteries, although purchasing decisions in these markets remain heavily influenced by reliability, cost and product availability.

Integration Will Determine the Deal’s Long-Term Impact

The acquisition would also expand Stryten’s international operations. C&D Trojan has manufacturing facilities in Mexico and China, research and development activities in the United States, and commercial offices across Europe and Asia.

That footprint could help the combined company support multinational customers and respond more directly to regional demand. It would also add operational complexity across manufacturing sites, product categories and distribution networks.

Stryten has presented the transaction as an opportunity to speed up product development and serve more applications with both advanced lead and lithium battery technologies. The practical results, however, will depend on how effectively the company integrates the acquired plants, supply chains, brands and sales operations.

Customers and competitors are likely to monitor any changes to product availability, pricing, distributor relationships and investment priorities after the deal closes.

The acquisition also increases Stryten’s exposure to military, government and mission-critical infrastructure customers. A larger domestic manufacturing base could support those markets, but regulatory approval, integration costs and execution risks remain important factors.

Free Training

Source link

Bmw Group Has Opened Electric Vehicle And Battery Manufacturing Facilities In South Carolina


BMW Group has opened expanded vehicle and battery manufacturing facilities in Spartanburg and Woodruff, South Carolina. The company, which assembles BMW vehicles and produces BMW X models, invested $1.7 billion in its South Carolina operations and said its business activities in the U.S. support more than 120,000 jobs nationwide.

The investment included the expansion of Plant Spartanburg and the construction of Plant Woodruff, creating the foundation for assembling fully electric BMW vehicles in South Carolina. BMW confirmed that the BMW iX5 will be the first fully electric BMW assembled in the United States, with production scheduled to begin at Plant Spartanburg before the end of 2026.

Plant Spartanburg assembled 412,799 BMW X models in 2025, marking the seventh time the facility exceeded 400,000 units of annual production. Since 1994, the plant has assembled more than 7.3 million BMW vehicles, with approximately half of its current production exported to nearly 120 countries.

The new BMW X5 assembled at Plant Spartanburg will become the first vehicle offered with five drivetrain technologies, including internal combustion, battery electric, plug-in hybrid electric, diesel, and soon, fuel cell electric powered by hydrogen. Plant Spartanburg will also become the first facility in BMW Group’s global production network capable of assembling a single vehicle with five different drivetrain technologies on one assembly line.

BMW said the facilities implement the principles of its BMW iFACTORY production concept through smart automation, end-to-end data integration and virtual planning. The plants use digital twins and 3D virtual simulations to optimize processes, while artificial intelligence supports self-correcting robotics, vision-based quality controls, and the AIQX platform, which uses sensors and camera systems to automate quality processes and provide real-time feedback to employees.

Plant Spartanburg is also deploying humanoid robots from Figure AI to support workers in physically demanding and repetitive tasks. At Plant Woodruff, the company is implementing a “Cell-to-Pack” manufacturing approach that assembles battery cells directly into housings without cell coating and cell module production processes.

In a recent quote, Milan Nedeljković, chairman of the board of management, BMW AG, said, “When we announced our investment plans for South Carolina in 2022, we made a clear commitment to the future of the BMW Group in the United States. Today, we are delivering on that commitment. The completion of our investments in Plant Spartanburg and Plant Woodruff demonstrates our confidence in the United States and reinforces South Carolina’s role at the center of BMW Group’s global operations.”

In a recent quote, Dr. Robert Engelhorn, president & CEO, BMW Manufacturing Co., said, “From highly efficient combustion engines and plug-in hybrid systems to battery-electric and future hydrogen-powered vehicles, Plant Spartanburg will be able to assemble a broad range of drivetrain technologies for customers in the U.S. and around the world.”

AmbioPharm to spend $119 million on South Carolina expansionThe peptide manufacturer plans to hire for 202 new jobs at the site.

Red Metals to build new $70 million copper factory in South CarolinaThe company expects to make 45 new jobs there.

USA Rare Earth to build new $1.2 billion magnet plant in South CarolinaThe factory will produce neodymium-iron-boron magnets for use in electrolysis and industry.

Suniva to open new South Carolina solar cell factoryThe $350 million plant is expected to create 564 new jobs.

George Utz. Inc. to spend $40 million on new South Carolina factoryThe Sumter County site will be home to 50 new jobs.

Free Training

Source link

U.S. Battery Manufacturing Construction Hits $45 Billion Amid Energy Storage Shift


U.S. Battery Manufacturing Construction Reaches $45B as Automakers Shift Toward Energy Storage

Battery manufacturing construction activity across the United States has reached unprecedented levels, with approximately $45 billion worth of projects currently under construction as automakers and energy companies pivot toward energy-storage technology.

Courtesy: photo by Julia on Pexels

According to new data released by Industrial Info Resources (IIR), the U.S. has roughly $63 billion in active and planned battery-manufacturing projects underway, with the majority of spending tied to facilities already being built.

The construction boom reflects a significant shift in strategy among automotive manufacturers and battery suppliers as demand growth for fully electric vehicles slows and companies increasingly focus on battery energy storage systems, or BESS.

“Rollbacks on energy transition funding — including the expiration of the federal $7,500 consumer EV tax credit — and slower-than-expected market adoption — are leading domestic automakers to shift production from full EVs, leaving some U.S. battery-manufacturing capacity underutilized,” the report stated.

Industry analysts say the transition is also being fueled by growing electricity demand from data centers and renewable energy infrastructure.

Automakers Reconfigure Facilities for Energy Storage Production

Major automakers including Ford and General Motors are investing billions to convert or expand facilities capable of producing lithium-iron-phosphate batteries for energy-storage applications.

Ford recently launched its new Ford Energy division and is investing approximately $2 billion to convert a former EV battery plant in Glendale, Kentucky, into a commercial BESS manufacturing facility. The plant is expected to produce at least 20 gigawatt-hours annually and begin operations in 2027.

Another Ford battery project under construction in Marshall, Michigan, is expected to begin production later this year and will focus on smaller residential battery units.

General Motors and Samsung SDI are also constructing a $3.5 billion battery facility in Indiana designed to support both EV and energy-storage battery production. Construction is expected to conclude by the end of 2027.

Meanwhile, GM’s Ultium Cells joint venture with LG Energy Solution is retooling its Spring Hill, Tennessee, facility to shift manufacturing toward lithium-iron-phosphate battery cells for energy storage.

Battery-storage technology is becoming increasingly important for utilities and data centers seeking alternatives to diesel-powered backup systems during grid disruptions.

Suppliers Expand U.S. Battery Investments

Battery manufacturers and suppliers are continuing to invest heavily in U.S. production capacity tied to Tesla and hybrid vehicle demand.

LG Energy Solution recently signed a deal to provide Tesla with $4.3 billion worth of lithium-iron-phosphate battery cells from its Lansing, Michigan, facility for use in energy-storage systems. The agreement is driving plans for a multibillion-dollar retooling and expansion of the plant.

Panasonic is also moving forward with a $4 billion expansion of its De Soto, Kansas, facility near Kansas City to increase production of battery cells for Tesla electric vehicles. Full-scale production is expected to begin in 2027.

Toyota is simultaneously expanding battery production at its Liberty, North Carolina, campus, the company’s only battery plant outside Japan. The project includes a new building with two production lines and eight additional lines dedicated to plug-in hybrid vehicles.

Industrial Info Resources said the rapid expansion of battery manufacturing construction demonstrates how energy storage is becoming a critical component of the nation’s evolving power infrastructure and industrial economy.

The report also highlights how data center growth and grid reliability concerns are reshaping investment priorities across the automotive and manufacturing sectors.

Originally reported by Danny Levin, Deputy Editor for IIR News Intelligence (Sugar Land, Texas) in Industrial Info. Com.

Free Training

Source link

Kelly leads 52 Republicans in rejecting Chinese auto, battery manufacturing in U.S.


U.S. Rep. Mike Kelly (R-PA) recently led 52 of his Republican colleagues in urging the Trump administration against making any trade decisions that would allow Chinese automotive and battery companies to manufacture their products in the United States.

“The U.S. auto industry is reaching a critical inflection point, as global dynamics and shifts in policy create opportunities for heavily subsidized Chinese automakers to gain momentum using non-market tactics,” wrote Rep. Kelly and the lawmakers in an April 30 letter sent to U.S. Treasury Secretary Scott Bessent, U.S. Commerce Secretary Howard Lutnick, and U.S. Trade Ambassador Jamieson Greer.

“If Chinese automotive companies were granted access to manufacture and sell vehicles and batteries in the U.S., we risk decimating U.S. manufacturing, eroding global market share for U.S. auto companies, and leaving consumers and businesses exposed to serious cybersecurity and surveillance threats,” they wrote. “This is not a winning strategy.”

In their letter, which was sent in advance of President Trump’s meeting with Chinese President Xi Jinping on trade matters between the U.S. and China, the members pointed out that Chinese automotive companies have recently accelerated investment in North America and flooded global markets with the long-term goal of dominating market share and controlling automotive manufacturing and supply chains globally. 

Chinese automakers are also heavily subsidized by the Chinese government, creating an unlevel playing field for American automakers, according to their letter.

“We must be clear-eyed about China’s goals in expanding their automotive footprint across the globe. China’s intent is not fair competition, as evident by their actions in other critical sectors,” the members wrote. “They have drastically inflated supply in their domestic auto market through unfair government subsidies and other benefits intended to artificially prop up companies, forcing them to export and expand to foreign markets at below-market prices. 

“China’s goal is not to compete in the U.S. automotive market, but instead to hollow it out and ultimately limit consumer choice to Chinese brands,” they added. “Allowing Chinese automotive and battery companies to manufacture in the U.S. would jeopardize our national security.”

As negotiations with China continue to develop, wrote the members, they urged the administration to reject any attempts by China to establish vehicle and battery manufacturing facilities stateside or in the broader North American market.

Among the lawmakers who joined Rep. Kelly in signing the letter were U.S. Reps. Carol Miller (R-WV), Michael Rulli (R-OH), Troy Balderson (R-OH), Bob Latta (R-OH), John Joyce (R-PA), Brian Fitzpatrick (R-PA), Kat Cammack (R-FL), Ron Estes (R-KS), Andy Barr (R-KY), John Moolenaar (R-MI), Vern Buchanan (R-FL), Ashley Hinson (R-IA), Erin Houchin (R-IN), Buddy Carter (R-GA), Bill Huizenga (R-MI), Darin LaHood (R-IL), Laurel Lee (R-FL), Blake Moore (R-UT), Kevin Hern (R-OK), Pete Stauber (R-MN), Mike Carey (R-OH), and Rudy Yakym (R-IN).

Post navigation


Free Training

Source link

Taiwanese Battery Manufacturer Selects Liberal for New U.S. Facility


TOPEKA – The Kansas Department of Commerce today announced Apogee Power, a Taiwan-based energy technology and advanced battery manufacturer, has selected Liberal as the location for its new U.S. manufacturing and assembly facility. The company will invest almost $16 million over the next three to five years and create 80 new jobs.

“In Kansas, we have a strong advanced battery ecosystem, talented workforce and central location that companies from around the world are eagerly looking to access,” Lieutenant Governor and Secretary of Commerce David Toland said. “Apogee’s decision to expand their work into Liberal highlights the strength of our rural communities and Kansas’ ability to compete on a global scale.”

The facility, located in Liberal’s industrial corridor, will support the assembly, testing and distribution of Apogee’s lithium iron phosphate (LFP) battery systems and related energy storage technologies for commercial, industrial and grid-scale applications across the United States. The company anticipates hiring 30 employees in the initial phase — with additional positions coming online as production ramps up.

Apogee is currently preparing the Liberal facility for production and expects to begin operations this summer. The facility represents Apogee’s first U.S. manufacturing presence and reflects their long-term commitment to serving customers from a centralized and cost-competitive location.

Apogee Power CEO Wen Lin, Apogee Energy CEO George Shen and other stakeholders were in Topeka recently to discuss the company’s investment and their desire to recruit additional suppliers from Taiwan to the Liberal area and other possible locations in Kansas. This followed a trade mission to Taiwan in September 2025, when Lieutenant Governor and Secretary of Commerce David Toland and other state and local officials visited Apogee Power’s headquarters in Taipei to meet their team and finalize the project details.

“Establishing a U.S. manufacturing footprint is a critical step in Apogee’s global growth strategy,” Apogee Power CEO Wen Lin said. “Liberal offers the infrastructure, workforce and community partnership we were looking for — along with a strong understanding of energy-intensive manufacturing. This location allows us to serve U.S. customers more efficiently while building a durable, long-term presence in the American market.”

Local leaders emphasized the collaborative approach that helped secure the project.

“We’re excited to welcome Apogee to Liberal,” Seward County Development Corporation Executive Director Eli Svaty said. “This investment builds on our region’s strengths in energy, logistics and advanced manufacturing. It also signals that global technology companies see value in smaller, execution-focused communities that can move quickly and deliver.”

Free Training

Source link

US Battery Manufacturing Expansion Surges Ahead


The modern energy storage sector operates through complex production networks where manufacturing capacity development frequently outpaces immediate market absorption. This phenomenon reflects broader industrial scaling patterns where initial overcapacity serves as infrastructure foundation for future demand expansion. Understanding these capacity-demand imbalances provides insight into strategic positioning within rapidly evolving technology markets.

Current U.S. battery manufacturing expansion demonstrates this dynamic through unprecedented facility construction rates and investment flows. Manufacturing infrastructure development now exceeds traditional forecasting models, creating strategic opportunities for industry participants while reshaping global supply chain architectures.

Analyzing Manufacturing Capacity Growth Trajectories

Battery manufacturing infrastructure in the United States has undergone dramatic transformation since 2024, with production capabilities expanding from minimal grid storage capacity to comprehensive domestic supply sufficiency. Industry data reveals systematic capacity building across multiple technology platforms and geographic regions.

Grid Storage Production Capacity Evolution:

• 2024 baseline: 70 GWh annual production capacity across limited facility networks

• 2025 expansion: 145 GWh capacity through foreign investment integration

• 2026 projections: 280 GWh capacity representing 300% growth over two years

• 2027 targets: 421.5 GWh projected capacity with mature supply chain networks

This expansion timeline represents one of the fastest manufacturing scale-ups in modern industrial history. The Centre on Global Energy Policy documented cost reduction mechanisms driving this growth, noting production cost decreases of up to 30 percent through federal incentive structures.

Manufacturing facility diversity has expanded from single-cell suppliers to comprehensive production ecosystems. Current supplier networks include 10 module assembly operations and projected expansion to 11 suppliers by 2027, indicating market maturation beyond initial foreign investment phases.

Regional Manufacturing Distribution:

Geographic Region
Primary Facilities
Investment Value
Technology Focus

Great Lakes Corridor
Michigan, Ohio operations
$15+ billion
LFP battery cells

Southeast Hub
Georgia, Tennessee plants
$20+ billion
Module assembly

Southwest Expansion
Texas, Arizona facilities
$8+ billion
System integration

Furthermore, grid storage manufacturing differs fundamentally from electric vehicle battery production through chemistry selection, form factor requirements, and cycle life optimization. Lithium iron phosphate (LFP) chemistry dominates stationary storage applications due to enhanced safety profiles and extended operational lifespans compared to traditional lithium-ion formulations used in transportation applications.

When big ASX news breaks, our subscribers know first

Federal Policy Architecture and Investment Incentives

Manufacturing investment decisions respond directly to policy framework structures that reduce operational costs while providing market access advantages. The Inflation Reduction Act created competitive positioning for domestic manufacturing through multiple incentive mechanisms.

Cost Reduction Framework Analysis:

• Manufacturing tax credits: Direct production cost reduction averaging 30%

• Local content requirements: Driving foreign manufacturers toward domestic operations

• Supply chain incentives: Encouraging component sourcing diversification

• System integration benefits: Favoring vertically integrated manufacturing approaches

Investment data from S&P Global indicates the United States imported over $100 billion in batteries and components since 2021, with approximately 50% sourced from Chinese suppliers. This import dependency created strategic vulnerabilities that federal policy mechanisms aim to address through domestic capacity building.

Korean manufacturing companies responded most aggressively to these incentive structures, committing approximately $20 billion toward U.S. battery manufacturing expansion between 2025 and 2029. Benchmark Minerals projects Korean producers will contribute over 40% of domestic capacity growth during this period.

Tariff Strategy Implementation

Current tariff policies create protective mechanisms for domestic manufacturers while maintaining supply chain relationships with essential material suppliers. However, the broader trump tariffs impact demonstrates how trade policy complexity emerges from geographic concentration of critical materials processing.

Trade policy complexity emerges from geographic concentration of critical materials processing. Chinese suppliers control approximately 85% of graphite processing, 60% of lithium processing, and 75% of cathode material production, creating strategic supply chain chokepoints despite domestic manufacturing growth.

Leading Manufacturing Scale-Up Companies

LG Energy Solution Strategic Pivot

LG Energy Solution executed the most significant facility transformation in the sector through its Holland, Michigan operation conversion from electric vehicle to grid storage production. The company invested $1.4 billion to establish dedicated lithium iron phosphate production lines with 16.5 GWh current capacity.

This strategic pivot reflects market condition adaptation as electric vehicle demand growth slowed while grid storage requirements accelerated. LG projects capacity expansion to 50 GWh by end-2026, representing 200% growth within 18 months.

Facility Conversion Process:

• Technology transfer: Adapting EV battery lines for stationary storage chemistry

• Equipment modification: Retrofitting assembly systems for different form factors

• Workforce retraining: Developing expertise in grid storage applications

• Quality control systems: Implementing cycle life testing protocols

Korean Investment Leadership

Samsung SDI and SK Innovation complement LG’s expansion through coordinated facility development across multiple states. Combined Korean investment exceeds $20 billion, establishing comprehensive supply chain networks from raw material processing through finished system assembly.

Geographic distribution strategies focus on transportation cost minimisation and workforce availability. Tennessee, Georgia, and Michigan emerged as preferred locations due to existing automotive manufacturing expertise and logistical infrastructure.

Domestic Manufacturing Champions

Tesla Energy operates the largest single-site battery manufacturing facility in California with 40 GWh annual Megapack production capacity. The company’s vertical integration strategy encompasses battery cells, module assembly, and complete system manufacturing under unified operational control.

In addition, Stryten Energy pursues multi-chemistry diversification across lead-acid, lithium-ion, and vanadium redox flow battery technologies. The company operates 11 existing facilities with planned 10 GW capacity addition across military, grid storage, and transportation market segments.

Supply Chain Dependency Analysis

Critical Material Import Vulnerabilities

Despite domestic manufacturing expansion, essential component dependencies persist across multiple supply chain stages. International Energy Agency analysis identifies production capacity and technical expertise concentration in Asian markets as primary supply security risks.

Material Category
Primary Suppliers
Dependency Level
Alternative Sources

Active materials
China (75%)
High
Korea, Japan limited

Precursor chemicals
China (80%)
Critical
Australia, Chile emerging

Processing equipment
China, Korea (70%)
High
European alternatives

Quality control systems
Korea, Japan (60%)
Medium
Domestic development

Raw material processing represents the most significant supply chain vulnerability. Graphite processing remains 85% concentrated in Chinese facilities, while cathode material production shows similar geographic concentration patterns.

This vulnerability underscores the importance of critical minerals energy security considerations that influence manufacturing expansion decisions.

Midstream Manufacturing Gaps

Active material production capabilities require substantial technology transfer and equipment investment to establish domestic alternatives. Current domestic facilities focus primarily on final assembly operations rather than chemical processing stages.

Korea and Japan offer the only significant alternative supplier bases for essential components, but capacity limitations restrict their ability to substitute for Chinese supply chains completely. This creates strategic dependencies despite domestic final assembly capabilities.

Supply Chain Resilience Strategies:

• Inventory management: Maintaining strategic material stockpiles

• Supplier diversification: Developing alternative source relationships

• Technology licensing: Acquiring processing expertise through partnerships

• Vertical integration: Establishing domestic chemical processing capabilities

Technical Manufacturing Challenges

Production Scaling Complexities

Rapid facility expansion creates multiple technical challenges from equipment installation through workforce development. Manufacturing quality control systems require extensive optimisation during capacity ramp phases.

Grid storage applications demand different performance characteristics than electric vehicle batteries, necessitating specialised production processes. Cycle life optimisation becomes paramount for stationary applications where batteries may operate for 20+ years with daily charging cycles.

Technology Transfer Difficulties

Adapting Asian manufacturing processes to American operational environments requires substantial modification of equipment, procedures, and quality control systems. Korean and Japanese production methodologies developed for different labour markets and regulatory frameworks.

Key Technical Challenges:

• Yield optimisation: Achieving target production rates during startup phases

• Quality consistency: Maintaining performance specifications across production volumes

• Process automation: Integrating robotic systems with manual operations

• Material handling: Managing hazardous chemical processing safely

Consequently, workforce development represents a critical bottleneck as battery manufacturing requires specialised technical skills unavailable in traditional automotive or electronics manufacturing. Training programmes require 6-12 months for technician certification in electrochemical processing operations.

Market Demand and Capacity Balance

Supply-Demand Projections

Current manufacturing expansion trajectories suggest domestic production capacity will exceed demand requirements by 2026. This overcapacity scenario creates both opportunities for export market development and risks of industry consolidation.

Energy storage demand growth of 21% annually supports continued capacity expansion, driven primarily by renewable energy integration requirements and data centre backup power needs. However, production capacity growth exceeds 50% annually, creating potential oversupply conditions.

2026 Market Dynamics Analysis:

• Domestic production capacity: 280 GWh annually

• Projected U.S. demand: 200 GWh combined grid and transportation

• Export potential: 40 GWh available for international markets

• Market concentration: 10-12 major suppliers competing for market share

Regional manufacturing clusters enable transportation cost optimisation and supply chain coordination. The Southeast corridor development creates comprehensive ecosystem from raw material processing through finished system delivery.

Demand Growth Drivers

Data centre expansion represents the fastest-growing battery storage market segment as artificial intelligence and cloud computing requirements drive backup power needs. These applications require different battery specifications than traditional grid storage installations.

Furthermore, renewable energy integration continues as the primary demand driver, but growth rates may moderate as grid infrastructure adapts to higher renewable penetration levels. This creates uncertainty for long-term capacity planning.

The next major ASX story will hit our subscribers first

Geopolitical Manufacturing Implications

China Relationship Management

Maintaining supplier relationships with Chinese material producers while developing domestic manufacturing creates complex diplomatic and commercial challenges. Tariff policies must balance protective measures with supply chain continuity.

Chinese companies retain control over critical processing technologies and raw material access despite American manufacturing expansion. This creates ongoing strategic vulnerabilities that policy mechanisms alone cannot eliminate.

Interestingly, the chinese battery recycling breakthrough offers potential collaboration opportunities that could benefit American manufacturing sustainability goals.

International Partnership Development

Korean technology transfer represents the most successful international collaboration model, combining foreign expertise with domestic manufacturing capacity. This partnership approach enables rapid technology acquisition while building domestic capabilities.

Japanese collaboration focuses on advanced materials and precision manufacturing equipment, complementing Korean strengths in battery chemistry and production processes. European partnerships emphasise recycling and circular economy technologies.

Strategic Competition Dynamics:

• Technology leadership: Competing for next-generation battery innovations

• Market access: Securing international customer relationships

• Supply chain control: Developing alternative material sourcing networks

• Manufacturing cost: Achieving competitive production economics

Investment Patterns and Market Evolution

Project Development Timeline

Major facility investments require 2-3 years from announcement to production startup, creating predictable capacity addition schedules. Current project pipelines suggest continued expansion through 2028-2029 before growth rates moderate.

Significant Facility Investments:

Company
Location
Investment
Capacity
Timeline

Toyota-Panasonic
Liberty, NC
$14 billion
75 GWh
2025-2027

LG Energy Solution
Holland, MI
$1.4 billion
50 GWh
2025-2026

AESC
Tennessee
$2.8 billion
30 GWh
2026-2027

Samsung SDI
Multiple states
$5 billion
45 GWh
2025-2028

Cancelled Projects Analysis

Financial constraints and market uncertainty resulted in approximately $8 billion in cancelled investments, including KorePower Arizona ($1.2 billion) and Freyr Georgia ($2.6 billion) projects. These cancellations reflect more realistic demand forecasting and financing challenges.

Project cancellations concentrated amongst smaller companies lacking established customer relationships or proven manufacturing expertise. Larger corporations with automotive industry partnerships demonstrated greater project completion rates.

Financial Market Assessment

Manufacturing investment patterns reveal preference for companies with proven production expertise and established customer relationships. Financial markets increasingly scrutinise demand projections and competitive positioning before committing development capital.

Equity valuations reflect manufacturing capacity expansion but discount future profitability due to competitive pressures and potential oversupply scenarios. Debt financing requires demonstrated customer contracts and operational cash flow projections.

Technology Evolution and Manufacturing Adaptation

Next-Generation Technology Development

Solid-state battery development threatens current lithium-ion manufacturing investments through superior energy density and safety characteristics. However, manufacturing complexity and cost structures delay commercial deployment until 2030 or later.

Alternative chemistry development includes sodium-ion and iron-air storage systems targeting different market segments than traditional lithium-ion applications. These technologies require different manufacturing equipment and processes.

Manufacturing Process Innovation

Automation advancement reduces labour costs while improving quality consistency, particularly important for achieving competitive production economics. Robotic systems handle hazardous materials processing and precision assembly operations.

Energy efficiency improvements lower production carbon footprints, increasingly important for regulatory compliance and customer requirements. Manufacturing facilities integrate renewable energy sources to minimise operational emissions.

Moreover, american battery recycling initiatives complement manufacturing expansion by providing sustainable material sourcing options.

Technology Differentiation Strategies:

• Cycle life optimisation: Extending battery operational lifespans

• Energy density improvements: Reducing system footprint requirements

• Safety enhancements: Minimising fire and thermal runaway risks

• Cost reduction: Achieving competitive pricing through scale economies

Modular facility design enables rapid capacity adjustments based on market demand fluctuations. This flexibility becomes increasingly important as demand forecasting uncertainty persists across different application segments.

Industry Structure and Consolidation Dynamics

Overcapacity Scenario Planning

Potential industry consolidation by 2027-2028 reflects manufacturing capacity exceeding demand absorption rates. Smaller producers lacking scale economies or customer relationships face greatest financial pressure during market adjustment periods.

Market share concentration amongst 3-5 major producers appears likely as competitive pressures eliminate marginal operations. Korean companies and established American manufacturers demonstrate strongest competitive positioning.

This trend aligns with broader industry consolidation dynamics affecting resource-intensive manufacturing sectors.

Competitive Differentiation Requirements

Technology advancement becomes essential for maintaining market position as basic manufacturing capabilities commoditise. Companies invest heavily in research and development to create sustainable competitive advantages.

Vertical integration strategies provide cost advantages and supply chain control but require substantial capital investment. Companies must balance integration benefits against financial requirements and operational complexity.

Export Market Development

North American integration through Canadian and Mexican partnerships creates natural export opportunities for excess production capacity. Trade agreements facilitate cross-border manufacturing and distribution networks.

Global competitiveness requires achieving cost parity with Asian manufacturers while maintaining quality and delivery advantages. American manufacturers leverage proximity to customers and supply chain responsiveness as competitive factors.

The U.S. battery manufacturing expansion represents a fundamental restructuring of global energy storage supply chains, transforming America from import-dependent to potentially export-capable within five years. However, persistent dependencies on Asian supply chains for critical materials and continued manufacturing cost challenges suggest ongoing strategic vulnerabilities.

Success in this transformation requires maintaining technological competitiveness while developing alternative supply sources and adapting to evolving demand patterns. The US battery manufacturing capacity industry’s rapid expansion creates both unprecedented opportunities for energy independence and significant risks from potential overcapacity scenarios that could reshape competitive dynamics across the entire sector.

Want to capitalise on the next energy storage breakthrough?

Discovery Alert’s proprietary Discovery IQ model delivers real-time alerts on significant ASX mineral discoveries, including critical battery materials like lithium, graphite, and rare earth elements powering the global energy transition. Begin your 14-day free trial at Discovery Alert today and position yourself ahead of the market as energy storage demand creates unprecedented opportunities for strategic mineral discoveries.

Free Training

Source link