
ES Foundry backs PERC amid US PV manufacturing shift to n-type
ES Foundry CEO Alex Zhu tells PV Tech Premium that the company’s strategy is centred on delivering commercially bankable US-made cells today, even as it prepares to transition from crystalline bifacial p-type passivated emitter rear contact (PERC) to a next-generation n-type technology.
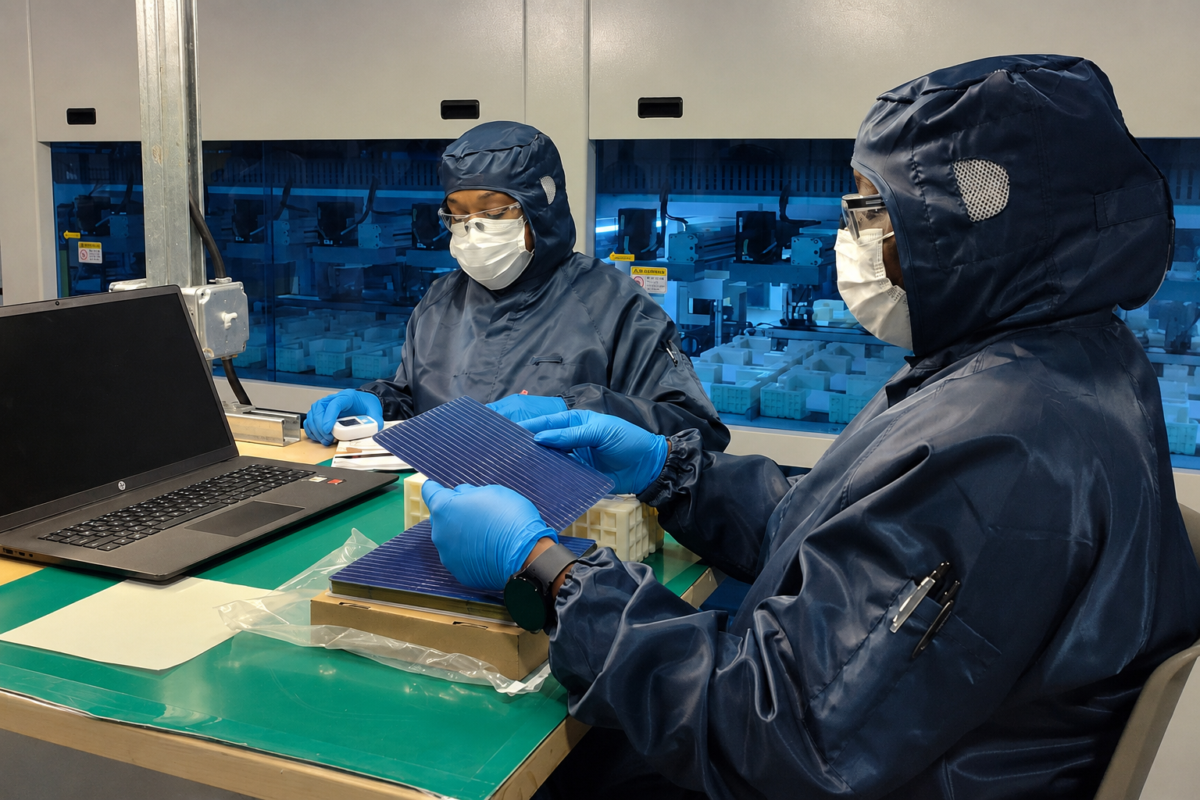
The company recently completed a 2GW expansion of its solar cell manufacturing capacity in Greenwood, South Carolina, taking its total capacity to 3GW as it seeks to establish itself as one of the few large-scale crystalline silicon cell manufacturers producing and shipping product in the US.
Es Foundry began operations with its first 1GW of capacity in 2025. According to Zhu, the company expects to have the expanded capacity fully ramped by October.
For him, however, the significance of the expansion extends beyond the headline capacity figure. He argues that ES Foundry’s differentiation lies in having moved from announcements to actual production.
“In terms of actual production, we are the largest crystalline solar cell manufacturer in the US,” Zhu tells PV Tech Premium.
He contrasts this approach with what he describes as a US solar manufacturing landscape characterised by numerous large announcements, some of which have not translated into operating capacity.
That focus on delivering product is also central to ES Foundry’s technology strategy.
Why PERC? And what comes next?
Last year, energy market analyst Clean Energy Associates (CEA) said PERC solar PV technology was “all but obsolete” in Europe, with n-type tunnel oxide passivated contact (TOPCon), heterojunction (HJT) and back contact (BC) technologies having almost entirely displaced it in “many international markets”, driven by China’s manufacturing scale, lower prices and higher efficiency.
Yet while much of the global industry has moved on, US cell manufacturer ES Foundry is taking a different approach, betting on PERC as the foundation of its domestic manufacturing strategy — for now.
Zhu acknowledges that PERC does not offer the same efficiency potential as newer cell technologies. But he argues that efficiency is only one part of the equation for a new US manufacturing operation.
“The reason we chose PERC is that it is very reliable and has a robust process window,” he notes.
For ES Foundry, that maturity provides two important advantages. The first is bankability. Financial institutions and customers are already familiar with PERC, while some newer technologies have a shorter track record in commercial manufacturing.
“The whole banking industry are familiar with PERC,” Zhu says. “Whereas some of the new technologies in US have not been fully tested.”
The second advantage is manufacturing. The US is rebuilding a solar manufacturing workforce after years in which much of the global cell production base migrated to Asia. Zhu says the shortage of experienced engineers, operators and technicians makes manufacturing a mature technology with a relatively forgiving process window particularly valuable.
“Using PERC as a starting point is very good for us to train the local labour force without cause a significant loss of efficiency or reliability.”
PERC is therefore the starting point rather than the destination. Zhu says ES Foundry will eventually move from p-type to n-type technology, but the company has not yet decided which specific n-type architecture it will adopt.
“We will move to n-type technology. However, we haven’t decided which n-type technology we will go with because this depends on multiple things like IP issues, the supply chain, and equipment availability.”
For ES Foundry, the choice of technology is also an IP decision. Recent TOPCon disputes involving First Solar, JinkoSolar, Trina Solar, Maxeon and Canadian Solar underline the litigation risks facing manufacturers adopting the technology in the US.
Section 232 creates a two-sided effect
Earlier this month, US President Donald Trump introduced a 15% tariff on imports of polysilicon and its derivatives, alongside minimum import prices, under Section 232, with the measures set to take effect on 4 December 2026.
Experts, who recently spoke with PV Tech Premium, said the Section 232 measures could support established US manufacturers and upstream investment, but raise solar costs, weaken demand and potentially deter new capacity, a tension echoed by Zhu. He says the measures on polysilicon and related upstream materials will significantly increase ES Foundry’s wafer costs.
“Our current wafer cost is, for example, from 4 cents to 7 cents imported from overseas. And after that, our cost will increase to like 15 cents plus 2 cents tariffs. That’s a significant increase in our cost. And of course, that will eventually increase our price to ship to our customers. Anytime you increase the price, a customer will not like it, and your demand will reduce,” the CEO emphasises.
Having said that, Zhu says the higher cost of imported wafers could ultimately be offset by stronger demand for domestic-content modules as the price gap with imported products narrows.
For ES Foundry, therefore, Section 232 presents a balancing act: higher input costs on one side, but potentially stronger demand for its US-made cells on the other.
Zhu says domestic-content modules can benefit from an additional 10% investment tax credit, potentially reducing the overall cost of a solar project even where the domestic-content module itself carries a higher upfront price.
“Even a domestic content module by itself is more expensive, but when you’re calculating into the whole formula, the total project cost will reduce,” he says.
Zhu also points to the rapid growth of solar projects associated with AI data centres as another source of demand.
“We see so many more project developers selling their projects to support the growth of AI data centres. At the same time, those customers also require domestic content because that will reduce the overall costs.”
The opportunity extends beyond cells. As domestic-content requirements increase, Zhu expects module manufacturers and their suppliers to look increasingly at other components, including junction boxes, EVA, ribbons and frames, to maximise the domestic contribution of their products.
The One Big Beautiful Bill Act (OBBBA) and evolving trade measures are therefore becoming important parts of the commercial landscape in which ES Foundry operates.
Building the US cell supply chain and the workforce to support it
For ES Foundry, scaling US cell manufacturing goes beyond adding capacity: the company still faces gaps in both its upstream supply chain and local workforce.
The company currently sources Chinese and non-Chinese polysilicon, with wafers produced in Southeast Asia, while US-made P-type wafers are not yet part of its supply chain.
For now, however, the company is focused on ramping its cell operations rather than pursuing backward integration into wafer manufacturing or forward integration into modules.
The workforce presents another challenge. Zhu says ES Foundry is training locally but continues to see a significant skills gap, prompting partnerships with MIT’s Initiative for New Manufacturing and a local community college in Greenwood.
“We’re doing a lot of training to train our local force, but there’s a significant gap,” he says. The training programme is intended to accelerate the development of workers capable of supporting both the current factory and future manufacturing expansion.
In the near term, ES Foundry appears confident that demand will support its existing 3GW annual nameplate capacity, with off-take agreements extending through 2028.
Zhu acknowledges that higher interest rates and interconnection delays could weigh on US solar demand, but says customers can shift delayed projects elsewhere.
“Most of our customers have multiple projects on hand, so even if some are delayed, they can easily shift to other projects.”
For ES Foundry, the immediate priority is therefore clear: establish reliable cell production while building the supply chain and workforce needed for its next phase of growth.