3 U.S. Manufacturing Stocks Tied To Tariff Driven Onshoring】【。


With a fresh US–Canada trade clash pushing tariffs higher and rattling cross border supply chains, investors face a new map of potential winners and losers. Sudden shifts in costs and sourcing can reshape where production happens and which companies keep pricing power. This article walks through three stocks from our U.S. Onshoring and Domestic Manufacturing Beneficiaries screener that appear well positioned for this moment.

The stocks highlighted below are just a starting sample, and the full screen surfaced 7 more companies with equally detailed domestic manufacturing narratives that are not covered here. If you want to move beyond the short list and start sizing up reshoring beneficiaries for yourself, head straight into the U.S. Onshoring and Domestic Manufacturing Beneficiaries screener to identify, filter and analyze the setups that best fit your own conviction.

SunCoke Energy (SXC)

SunCoke Energy is a coke producer tightly linked to U.S. steelmaking, which puts it squarely in the onshoring and domestic manufacturing story as tariffs push buyers toward tariff-insulated inputs. The business is heavily weighted to Domestic Coke, which generated about US$1.5b of revenue, with Industrial Services adding roughly US$356 million and smaller contributions from Corporate and Other and intersegment eliminations. With a market cap of about US$822 million, SunCoke Energy is a mid-cap stock that gives investors focused exposure to the U.S. steel supply chain rather than a broad metals basket.

For investors looking at how a prolonged US-Canada trade clash could reshape North American steel supply chains, SunCoke Energy offers a direct way to study those shifts. The company supplies coke and logistics services that support domestic blast furnaces, and it has been expanding into industrial services that can help smooth revenue. At the same time, it carries meaningful leverage, relies on a handful of large steel customers and pays a dividend that has raised questions around long term cover. That combination of tariff tailwinds, earnings guidance and balance sheet and customer concentration risk is why this stock may warrant a closer look before deciding where it fits in a portfolio.

SunCoke Energy’s tariff‑shielded position in the U.S. steel chain could be more powerful than the headline story suggests, yet its leverage and customer reliance raise real questions. Get the full picture in the 3 key rewards and 2 important warning signs (2 are major!)

NYSE:SXC Revenue & Expenses Breakdown as at Aug 2026NYSE:SXC Revenue & Expenses Breakdown as at Aug 2026

Build your own tariff beneficiaries shortlist

SunCoke Energy and the two other stocks in this list all came from a single Simply Wall St screener, but the real edge comes when you shape the filters yourself. Use our flexible Screener to mix valuation, growth, balance sheet, risk and dividend filters to suit your style, or tap into our curated Investing Ideas for ready made stock shortlists.

Aebi Schmidt Holding (AEBI)

Aebi Schmidt Holding manufactures specialized vehicles and equipment for airports, municipalities, commercial fleets and agriculture, which fits the onshoring theme through its North American production footprint and focus on workhorse infrastructure gear. The company generates about US$1.4b of revenue from North America and roughly US$576 million from Europe and the rest of the world, giving it meaningful exposure to U.S. demand for domestically produced equipment. With a market cap of about US$956 million, Aebi Schmidt Holding sits in mid cap territory where individual contracts and capacity decisions can materially influence the story.

Investors watching tariff driven reshoring should have Aebi Schmidt Holding on the radar because it brings a large, visible backlog, growing North American operations and a recent beat on Q2 2026 revenue and earnings into a sector where U.S. made fleet and airport equipment may gain share. The company is working through cost inflation and relies on external borrowings, so thin margins and leverage keep execution risk on the table even as management pursues efficiency programs and integration synergies. That mix of potential earnings upside tied to higher utilization and municipal and airport demand, alongside balance sheet and profitability questions, is exactly where deeper research can matter most.

Aebi Schmidt Holding’s backlog and North American footprint could be masking a much bigger earnings story. Get the full context in the 3 key rewards and 2 important warning signs (1 is major!) and see what the latest contracts might really signal

NasdaqGS:AEBI Revenue & Expenses Breakdown as at Aug 2026NasdaqGS:AEBI Revenue & Expenses Breakdown as at Aug 2026

Meritor (MTOR)

Meritor is a long established Michigan based manufacturer of axles, brakes and driveline components for medium and heavy duty trucks, trailers, military vehicles and buses, with growing electric drive systems that tie it directly into the U.S. auto and machinery supply chain story as companies look to source more content domestically. The stock has a market cap of about US$2.6b, which puts it in a bracket where contract wins, product mix and capital allocation decisions can still meaningfully influence long term value for shareholders.

Investors watching the US–Canada trade clash and the push for more U.S. made vehicle content should have Meritor on the radar. The company supplies core hardware that truck and machinery makers struggle to swap out quickly, and it is investing in electric drive systems that align with longer term freight and bus electrification. At the same time, high leverage and limited cash flow cover for debt mean any ramp up in North American production needs to be funded carefully, which keeps execution risk front and center. The balance of improving profitability, potential for a valuation rerating and a balance sheet that demands respect is exactly why a closer look at Meritor could be time well spent.

Meritor’s shift into electric drive systems could be masking a very different earnings path. Scan the 3 key rewards and 1 important major warning sign to see how the balance sheet risk and potential upside really line up.
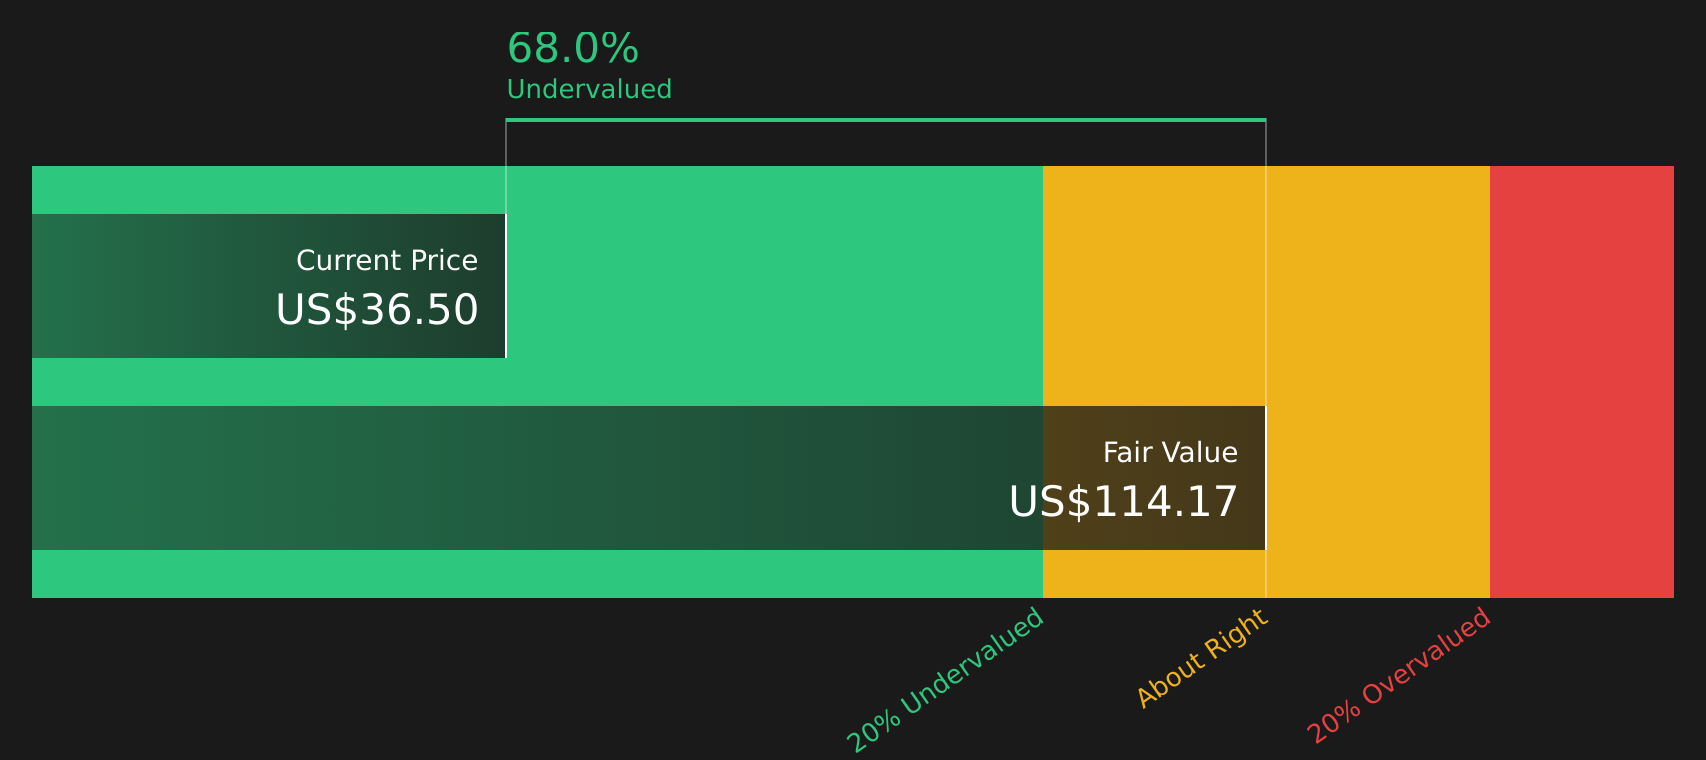
MTOR Discounted Cash Flow as at Aug 2026MTOR Discounted Cash Flow as at Aug 2026

Seeking Curiosity In Fresh Alternatives

Fresh stock ideas can move quickly when momentum builds and pricing gaps close. Consider identifying potential breakouts while they are still under the radar.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: Manage All Your Stock Portfolios in One Place

We’ve created the ultimate portfolio companion for stock investors, and it’s free.

• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks

Try a Demo Portfolio for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

U.S. Manufacturing Onshoring Stocks For Investors Watching Tariff Driven Factory Spending


With Washington now applying 50% tariffs on US$20b of Canadian imports and Ottawa preparing dollar-for-dollar retaliation, the long talked about shift toward onshoring suddenly feels more real. This disruption to steel, autos, lumber, and other cross border flows could reshape where factories sit and where capital goes. This article walks through 3 stocks exposed to this news and why they may matter for your watchlist.

The three stocks below are just a starting sample, since the full screen surfaced 29 more industrials and materials companies with onshoring related narratives that are not covered here but may be worth a closer look. To identify and analyze the ideas that best fit your own approach, head straight into the U.S. Manufacturing Onshoring Beneficiaries (Industrial & Materials) screener.

MYR Group (MYRG)

Overview: MYR Group is a US based electrical contractor that builds and maintains high voltage lines, substations, and complex wiring for utilities, factories, data centers, transport systems, and other large infrastructure projects, with operations largely tied to domestic spending on power grids and industrial facilities. As manufacturers bring more production onshore and plants are upgraded, MYR Group’s role wiring those facilities and reinforcing the surrounding grid places it close to the physical work behind the onshoring trend.

Operations: MYR Group generates about US$2.1b from Transmission & Distribution projects and about US$1.9b from Commercial & Industrial work, giving it two sizeable revenue pillars across utility and industrial customers.

Market Cap: US$5.0b

MYR Group offers exposure to the nuts and bolts of onshoring, wiring up new US factories, data centers, and grid upgrades while carrying a sizeable backlog of multi year utility contracts that add visibility to future work. The company has been focusing on higher margin projects such as battery storage and data centers, which supports improving profitability. At the same time, rising labor costs, lumpy commercial and industrial backlog, and heavier spending to win bigger jobs could pressure margins if demand slows. For investors tracking supply chain reshoring, this mix of opportunity and execution risk makes MYR Group an electrical contractor worth a closer look.

MYR Group’s push into higher margin data center and battery projects could be masking a very different risk reward profile than its utility backlog suggests. Get the full picture in the 5 key rewards and 1 important warning sign

NasdaqGS:MYRG Revenue & Expenses Breakdown as at Aug 2026NasdaqGS:MYRG Revenue & Expenses Breakdown as at Aug 2026

Build your own industrial onshoring shortlist

MYR Group and the two other stocks in this article all came from a single screen, but the real value comes from shaping a process that fits you. Use our flexible Screener to mix filters like valuation, balance sheet strength, and risks, or tap into ready made themes through our Investing Ideas.

Granite Construction (GVA)

Overview: Granite Construction is a U.S. infrastructure contractor and materials producer that builds and rehabilitates roads, bridges, rail lines, airports, dams, industrial sites, and energy projects, while also supplying aggregates and asphalt that feed its own jobs and third party customers. That mix ties Granite directly to the onshoring theme as manufacturers, logistics hubs, data centers, and energy projects require more domestic transport links, industrial sites, and construction materials.

Operations: Granite generates about US$4.1b from its Construction segment and about US$1.2b from Materials, offset by around US$0.4b of intersegment eliminations where it supplies its own projects.

Market Cap: US$5.4b

Granite Construction offers exposure to U.S. onshoring from the ground up, literally pouring the roads, industrial pads, data center sites, and energy infrastructure that support more domestic production. The company is focusing on this demand with a growing backlog, materials integration that can help with cost control, and acquisitions that expand its reach in high growth regions. At the same time, Granite is working toward sustained profitability and carries meaningful debt, so execution on new projects and further deals needs to be tight. For investors tracking onshoring, this combination of infrastructure exposure, materials scale, and balance sheet risk makes Granite a stock to watch closely.

Granite Construction’s growing backlog and materials scale could be masking a very different risk reward mix than many investors assume. Get the full story in the 4 key rewards and 2 important warning signs

NYSE:GVA Revenue & Expenses Breakdown as at Aug 2026NYSE:GVA Revenue & Expenses Breakdown as at Aug 2026

EMCOR Group (EME)

Overview: EMCOR Group is a U.S. based electrical and mechanical contractor that designs, installs, and services the critical systems that keep factories, data centers, and other industrial facilities running. This ties it directly to onshoring related builds and upgrades as production shifts onshore from Canada. Alongside this manufacturing work, EMCOR also provides broad facility services such as maintenance, energy retrofits, and industrial turnaround work across sectors like healthcare and refining.

Operations: EMCOR generates most of its revenue from U.S. Mechanical Construction and Facilities Services at about US$8.2b and U.S. Electrical Construction and Facilities Services at about US$5.8b. It also sees additional contributions from U.S. Building Services at about US$3.2b and U.S. Industrial Services at about US$1.4b.

Market Cap: US$34.7b

For investors tracking U.S. manufacturing onshoring, EMCOR Group provides a mix of electrical and mechanical project work on data centers, high end factories, and industrial sites. This is supported by facility services that can add recurring earnings. Management has highlighted a large and diversified backlog linked to data centers, healthcare, and manufacturing, along with a history of using acquisitions and prefabrication to pursue higher efficiency and margins. At the same time, the company notes risks around labor shortages, industrial cycle swings, and the need to absorb tariff related cost changes, while working to build contractual protections and pricing discipline. For investors seeking exposure to onshoring driven factory work, with both quality metrics and execution risks to consider, EMCOR may warrant closer attention.

EMCOR’s mix of high-spec factory and data center work, combined with recurring services, suggests a story that many investors may only be half seeing. Get the full context in the analysis report for EMCOR Group

NYSE:EME Revenue & Expenses Breakdown as at Aug 2026NYSE:EME Revenue & Expenses Breakdown as at Aug 2026

Seeking Alternatives Before The Crowd

Fresh stock stories can move from quiet to breakout fast. Use this momentum while it matters, before they get fully caught by the crowd. Get in early.

  • Chase durable income ideas with a curated 12 dividend fortresses that aim to keep portfolios supported even when prices are jumping or dropping elsewhere.
  • Track tomorrow’s automation leaders through a targeted 37 robotics and automation stocks that focuses on businesses building the machines, sensors, and software behind rising efficiency trends.
  • Position ahead of infrastructure momentum with a focused 39 power grid technology and infrastructure stocks that highlights companies gearing equipment and services toward grid upgrades while they remain under the radar for now.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

Valuation is complex, but we’re here to simplify it.

Discover if EMCOR Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.

Access Free Analysis

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

BlueLinx Stock and 2 U.S. Manufacturing Picks for Tariff Driven Price Power


Tariffs are back in the headlines, and for U.S. manufacturing stocks that can mean real shifts in costs, pricing power, and investor expectations. With the Trump administration’s new 10 to 12.5% global tariffs and fresh legal challenges testing how long these rules might last, some domestically focused producers may find themselves better positioned than import heavy rivals. This article looks at 3 U.S. manufacturing stocks from our screener that appear closely exposed to the latest tariff news, explaining how the policy and court risk could influence their margins, cash flows, and appeal for investors trying to position around these trade shocks.

BlueLinx Holdings (BXC)

Overview: BlueLinx Holdings is a U.S. based distributor of residential and commercial building products, supplying everything from engineered wood, siding and millwork to structural lumber and panels to large home centers, pro dealers and local contractors through warehouse, reload and direct sales.

Operations: BlueLinx generates all of its approximately US$3.0b in revenue from wholesale building products in the United States.

Market Cap: US$455m

Investors looking at tariff sensitive manufacturing stocks may find BlueLinx Holdings interesting because its largely domestic footprint can limit exposure to import cost shocks while still benefitting if tariffs lift pricing for imported competitors. The company is pushing harder into higher margin specialty categories and multifamily projects, but recent results show that margins and profitability remain under pressure, with a recent quarterly net loss and a history of losses over several years. The stock trades on a low P/S multiple versus peers, yet depends on a strong earnings improvement story and carries funding risk through external borrowing. The central question is whether the mix shift and tariff backdrop are enough to change the trajectory.

BlueLinx Holdings looks like a tariff era wildcard, with a domestic revenue base, a low P/S multiple and a push into specialty products that many investors may be underestimating, so it is worth reviewing the 3 key rewards and 1 important warning sign

NYSE:BXC P/S Ratio as at Jul 2026NYSE:BXC P/S Ratio as at Jul 2026

Matrix Service (MTRX)

Overview: Matrix Service is an engineering and construction company that builds and maintains critical energy and industrial infrastructure, including storage tanks, LNG and hydrogen facilities, substations and power projects, and specialized industrial plants across the U.S., Canada, and select international markets.

Operations: Matrix Service generates most of its roughly US$847.8m in revenue from Storage and Terminal Solutions (US$420.0m), with additional contributions from Utility and Power Infrastructure (US$282.9m) and Process and Industrial Facilities (US$144.9m), largely in the United States.

Market Cap: US$347.2m

Matrix Service stands out in the current tariff cycle because it supports U.S. based infrastructure projects and has contract structures that management says help shield it from sudden cost swings. A US$7b project pipeline and a recent shift toward higher margin electrical and storage work frame a potential return to more consistent profitability. At the same time, the company is still working through losses, relies on external borrowing, faces execution risks on large multi year projects, and is handling a CFO transition. Together, these factors help explain why the stock trades well below some cash flow and fair value estimates. For investors, the question is whether operational restructuring and the tariff tailwind are enough to offset these financing and execution risks.

Matrix Service’s US$7b project pipeline and shift toward higher margin work could be masking a deeper story about risk and reward, so it is worth reading the 4 key rewards and 1 important warning sign

NasdaqGS:MTRX Revenue & Expenses Breakdown as at Jul 2026NasdaqGS:MTRX Revenue & Expenses Breakdown as at Jul 2026

Generac Holdings (GNRC)

Overview: Generac Holdings is an energy technology company that makes backup generators, home energy storage, and other power equipment for households, businesses, and data centers, along with smart home and energy management products that help customers monitor and control their power use.

Operations: Generac generates most of its roughly US$4.3b in revenue in the United States, with about US$3.6b from the domestic market and around US$803m from international customers.

Market Cap: US$11.9b

Generac Holdings is attracting attention because it sits at the crossroads of U.S. manufacturing and the global push for reliable power, from home standby generators to large data center backup systems, while producing largely in the U.S. in a tariff heavy world. Earnings are forecast to grow, yet the stock trades on a rich P/E and relies fully on external borrowing, so the balance sheet and execution on big data center contracts matter. Recent margin gains and upgraded EBITDA guidance indicate that the business is scaling its higher value segments. However, exposure to residential solar headwinds, outage driven demand swings, and tariff sensitive supply chains means this is not a simple story.

Generac Holdings is leaning into higher value power and data center projects, yet a rich P/E and full reliance on borrowing raise big questions about how the story plays out next. It is worth scanning the analyst forecasts for Generac Holdings

NYSE:GNRC P/E Ratio as at Jul 2026NYSE:GNRC P/E Ratio as at Jul 2026

The three stocks covered here are just a starting point, and the full U.S. Domestic Manufacturing Stocks screener surfaced 41 more companies with equally compelling tariff, supply chain and domestic production stories that could be worth your attention. It makes sense to review the U.S. Domestic Manufacturing Stocks screener. Use Simply Wall St to identify, filter and analyze the exact catalysts and narratives that matter to you so you can focus on U.S. manufacturing opportunities that best fit your own investment approach.

Take Control of Your Investment Journey

If Generac Holdings or any of these companies sound like a great opportunity, register for FREE with Simply Wall St and add your companies to a Watchlist to monitor the share price against the fair value the ideal entry point.
Once you’ve made your move, manage your holdings with our Portfolio Command Center that filters out the noise to deliver only the most critical, actionable updates.
Throughout your journey, our Community allows you to filter the best ideas from thousands of investor perspectives.
By uncovering hidden catalysts and risks early, you’ll accelerate your decision-making and stay one step ahead of the market.

Seeking Alternatives Beyond Tariff Plays

Fresh ideas move first, and by the time the crowd spots the breakout, the best entry points can be gone. Scan these curated lists while it still matters and consider acting while conditions remain favorable.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: Manage All Your Stock Portfolios in One Place

We’ve created the ultimate portfolio companion for stock investors, and it’s free.

• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks

Try a Demo Portfolio for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

Dorman Stock And 2 U.S. Manufacturing Picks for a Tariff Driven Supply Chain Shift


Potential U.S. tariffs on Canadian goods and tighter rules on forced labour are putting a spotlight on where companies source and build their products. For investors, that creates both risk and opportunity, as supply chains tied to Canada could face higher costs while more U.S. domestic manufacturing becomes relatively more attractive. This article looks at how that backdrop connects to three stocks from a U.S. Domestic Manufacturing Stocks screener that appear exposed to this news. You will see how each company might be positioned, and why some investors may see reasons to pay closer attention now.

ZJK Industrial (ZJK)

Overview: ZJK Industrial is a Shenzhen based manufacturer of precision fasteners and metal parts, supplying screws, bolts, CNC machined parts, SMT and PVD products used in sectors such as new energy vehicles, smartphones, wearables, drones and 5G equipment across China, the U.S. and other markets.

Operations: ZJK Industrial generates about US$56.1 million in revenue from metal fasteners and related products, with most sales coming from China (US$32.45 million), followed by Taiwan (US$16.48 million) and smaller contributions from Singapore, America and other regions.

Market Cap: US$124.1 million

Investors looking at U.S. focused manufacturing themes may find ZJK Industrial interesting because it combines exposure to end markets such as AI servers, industrial robotics and EVs with a relatively low P/E of 12.2x and an 18.2% net margin. Earnings growth has been very strong recently, and recent product launches in higher value fasteners for automated production lines indicate demand for more precise components. At the same time, volatility, high non cash earnings and an inexperienced board underline that this is not a low risk stock. With the company currently underperforming the broader U.S. market despite strong recent financials, the gap between its potential and its current share price story is what may catch investors’ attention.

Strong recent earnings, an 18.2% net margin and a 12.2x P/E suggest ZJK Industrial might not be priced for its full story yet. The 4 key rewards and 2 important warning signs (1 is major!) could reveal what the current share price might be missing.

NasdaqCM:ZJK P/E Ratio as at Jul 2026NasdaqCM:ZJK P/E Ratio as at Jul 2026

Dorman Products (DORM)

Overview: Dorman Products supplies replacement and upgrade auto parts for cars, trucks and specialty vehicles, selling everything from engine and undercar components to electronics and hardware through major aftermarket retailers, distributors and dealers in the U.S. and abroad.

Operations: Dorman Products generates about US$1.71b of revenue from Light Duty parts, US$238.7m from Heavy Duty and US$205.7m from Specialty Vehicle products, with roughly US$1.99b of total sales coming from the United States and US$160.5m from other markets.

Market Cap: US$4.17b

Dorman Products sits at the intersection of an aging U.S. vehicle fleet, recurring demand for essential replacement parts and a global trade system where tariffs can reshape cost and competitive pressures. The company’s focus on aftermarket parts that drivers need to keep vehicles on the road, plus a pipeline of higher margin proprietary parts, helps support earnings quality even as net margins and ROE are modest and last year’s earnings declined 11.3%. Recent debt refinancing and share buybacks suggest management is confident about cash flow, yet reliance on external borrowing and ongoing tariff uncertainty remain important watchpoints. With potential U.S. tariffs lifting the relative appeal of domestically focused suppliers, the key consideration is how much of that potential is already reflected in Dorman’s share price story.

Dorman Products appears to be a steady operator whose earnings dip, modest margins and recent refinancing may be masking something more interesting in its story. The analysis report for Dorman Products could show what the tariff and cash flow puzzle is really pointing to next.

DORM Discounted Cash Flow as at Jul 2026DORM Discounted Cash Flow as at Jul 2026

TriMas (TRS)

Overview: TriMas is a U.S. based manufacturer that supplies dispensing and closure packaging, as well as steel gas cylinders, to consumer, industrial, aerospace and defense customers worldwide through brands such as Rieke, Rapak and Norris Cylinder.

Operations: TriMas generates most of its revenue from Packaging at about US$547.1 million, with Specialty Products contributing around US$114.4 million.

Market Cap: US$1.50b

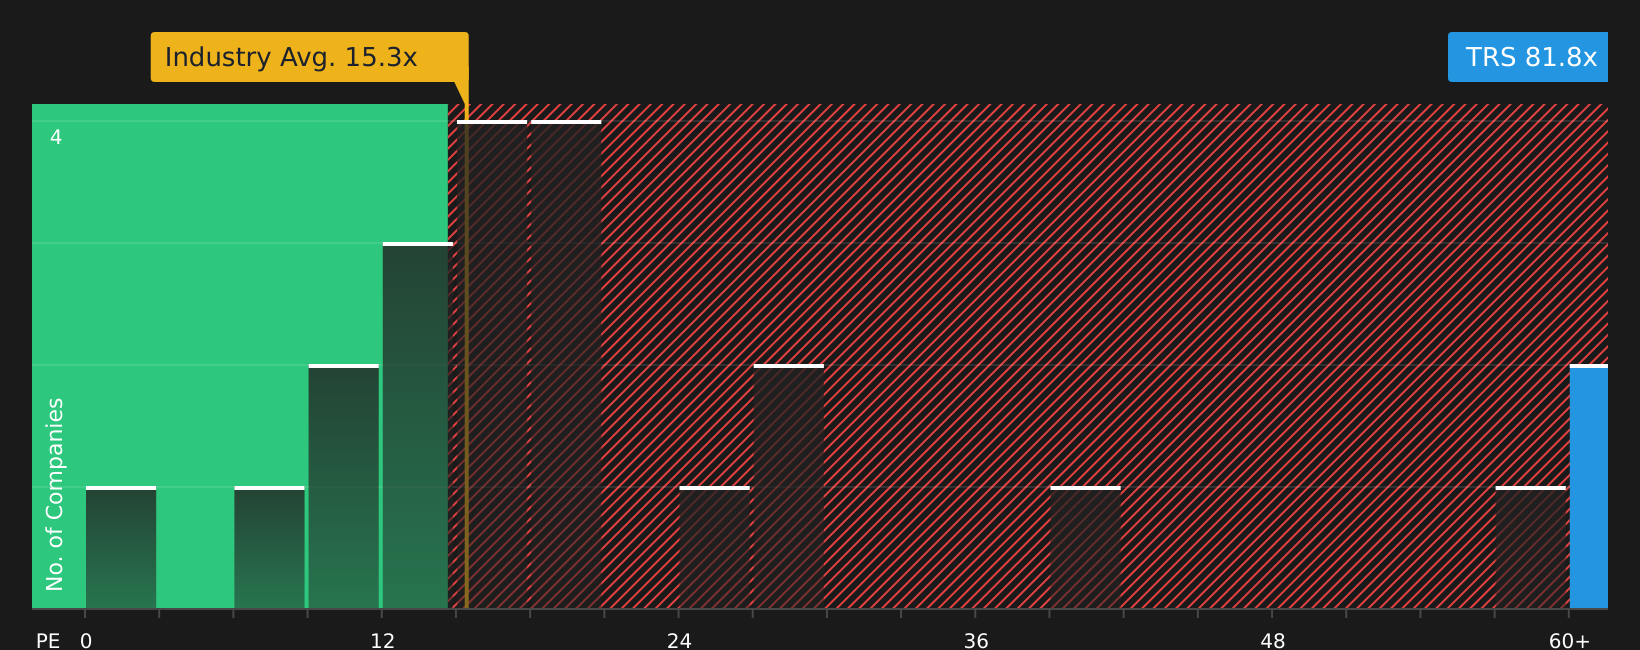
TriMas stands out in this U.S. Domestic Manufacturing Stocks screener because it links a largely U.S. oriented industrial footprint to packaging and gas cylinder products that are used across everyday consumer and industrial applications. This comes at a time when tariffs on imported goods and forced labour rules are pushing buyers to reassess where and how they source. The company is working on margin improvement through automation and integration of past acquisitions, is running an active buyback and dividend program, and management is already repositioning supply chains to limit tariff exposure. At the same time, a very high P/E, reliance on external borrowing and exposure to changing tariff policies and cyclical end markets mean investors need to look closely at what is driving the recent earnings jump and whether today’s valuation fully reflects the risks in the story.

TriMas’ high P/E, active buybacks and repositioned supply chains suggest that the current valuation story may be missing a key angle. The 3 key rewards and 2 important warning signs could surface the one risk reward twist that really matters next.

NasdaqGS:TRS P/E Ratio as at Jul 2026NasdaqGS:TRS P/E Ratio as at Jul 2026

The three stocks in this article are just a starting point, and the full U.S. Domestic Manufacturing Stocks screener surfaces 32 more U.S. focused manufacturers that may have equally compelling stories tied to tariffs, supply chains and domestic production. Use Simply Wall St to identify and analyze the specific catalysts, financial traits and risk profiles that matter to you so you can focus on the highest conviction ideas in this theme.

Take Control of Your Investment Journey

If Dorman Products or any of these companies sound like a great opportunity, register for FREE with Simply Wall St and add your companies to a Watchlist to monitor the share price against the fair value the ideal entry point.
Once you’ve made your move, manage your holdings with our Portfolio Command Center that filters out the noise to deliver only the most critical, actionable updates.
Throughout your journey, our Community allows you to filter the best ideas from thousands of investor perspectives.
By uncovering hidden catalysts and risks early, you’ll accelerate your decision-making and stay one step ahead of the market.

Seeking Alternatives Before Everyone Else?

Fresh stock ideas can gain momentum quickly, and the best entry points often get caught by early movers. Tap into under the radar opportunities before the crowd and act now.

  • Spot potential early breakouts in smaller companies with solid balance sheets by scanning the curated 18 high quality undiscovered gems while they are still flying under most investors’ radars.
  • Position ahead of possible shifts in energy and infrastructure by tracking curated 89 nuclear energy infrastructure stocks that could move as sentiment changes, while the best entries are still on offer.
  • Ride long term compounding income by reviewing a hand picked 9 dividend fortresses list that focuses on consistency and resilience before yields start dropping toward the crowd’s favorites.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: Manage All Your Stock Portfolios in One Place

We’ve created the ultimate portfolio companion for stock investors, and it’s free.

• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks

Try a Demo Portfolio for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

Tariff Driven U.S. Manufacturing Stocks Retail Investors Are Researching Now


Tariffs are back at the top of the agenda, and this time the focus is on imports tied to forced labor concerns. With the U.S. proposing duties of up to 12.5% on goods from 60 economies, domestically focused manufacturers have fresh attention from investors looking for companies less exposed to complex global supply chains. This article examines how the new tariff proposal could influence sentiment around U.S. Domestic Manufacturing stocks and highlights 3 stocks from our screener that appear positioned to be positively exposed to this policy shift.

EnerSys (ENS)

Overview: EnerSys is a US-based manufacturer of industrial batteries and stored energy systems that power telecom networks, data centers, factories, warehouses, trucks and defense applications worldwide through its Network & Infrastructure, Industrial Mobility and Precision Power segments.

Operations: EnerSys generates most of its roughly US$3.8b in revenue from Energy Systems (US$1.7b), Motive Power (US$1.4b) and Specialty solutions (US$665.1m), with a little over US$2.4b coming from US customers and about US$1.4b from foreign markets.

Market Cap: US$8.3b

For investors tracking the shift toward U.S. domestic manufacturing, EnerSys stands out as a large home-grown supplier of industrial batteries that already produces largely in region for region. It also has an internal tariff task force focused on keeping a roughly 22% U.S. sourcing exposure under control. Growth in data centers, electrified warehouses and defense programs is feeding demand for its lithium and lead-acid solutions. At the same time, cost programs and acquisitions are aimed at lifting margins, even though recent profit margins have eased and organic growth has been patchy. External borrowing raises funding risk, and a lithium cell factory remains on hold, so EnerSys offers a mix of structural tailwinds and execution questions that rewards closer inspection.

EnerSys could be an underappreciated way to play reshoring, with data centers and defense quietly reshaping its story, while margins and sourcing still raise questions. Get the full picture in the analysis report for EnerSys

NYSE:ENS Revenue & Expenses Breakdown as at Jun 2026NYSE:ENS Revenue & Expenses Breakdown as at Jun 2026

Crocs (CROX)

Overview: Crocs designs, makes, and sells casual footwear and accessories for men, women, and kids under the Crocs and HEYDUDE brands, offering clogs, sandals, sneakers, boots, and bags through wholesalers, its own stores, outlets, and online channels worldwide.

Operations: Crocs generates most of its roughly US$4.0b in revenue from the Crocs brand at about US$3.3b, with the HEYDUDE brand contributing around US$693.2m.

Market Cap: US$5.9b

For investors watching tariff headlines, Crocs is an interesting case because management has already been planning around higher duties, talking openly about potential annual cash costs of US$45m to US$130m while shifting sourcing and cutting at least US$50m in expenses. At the same time, the core Crocs brand is leaning into direct to consumer growth, social commerce like TikTok Shop, and international expansion. The HEYDUDE turnaround and high debt levels keep risk firmly on the table. Recent analyst upgrades and buyback activity illustrate how divided views are on the stock, which is why the full story on margins, tariffs, and brand momentum deserves a closer look before any decisions.

Crocs’ tariff playbook, cost cuts, and brand push are all moving at once, yet the market debate is still intense. See how those threads fit together in the analysis report for Crocs

NasdaqGS:CROX Revenue & Expenses Breakdown as at Jun 2026NasdaqGS:CROX Revenue & Expenses Breakdown as at Jun 2026

Amprius Technologies (AMPX)

Overview: Amprius Technologies develops and sells high energy density lithium ion batteries using silicon anode technology, primarily for aviation uses such as drones and high altitude platforms where lighter weight and longer flight times are critical.

Operations: Amprius Technologies generates about US$90.3m in revenue from its Battery Business, with roughly US$62.8m from EMEA customers, US$15.9m from North America, and US$11.5m from Asia Pacific.

Market Cap: US$1.8b

Amprius Technologies sits at the intersection of advanced battery tech, defense and drone adoption, and now potential tariff tailwinds as customers look for trusted suppliers. Its silicon anode batteries are already gaining traction in high value aviation and defense projects, and management has been expanding manufacturing capacity while keeping a global footprint that is less exposed to import duties. At the same time, the company is still loss making, trades on a rich sales multiple, and relies on external funding and fresh equity, so execution on scaling and margins really matters. For investors watching how U.S. tariff policy and domestic manufacturing priorities might reshape high end battery supply chains, this combination of opportunity and execution risk may make Amprius a candidate for further research.

Amprius Technologies focuses on high energy batteries, but the core issue is how its growth ambitions compare with its funding needs and scaling risk. See how that balance looks in the analysis report for Amprius Technologies

NYSE:AMPX Earnings & Revenue Growth as at Jun 2026NYSE:AMPX Earnings & Revenue Growth as at Jun 2026

The three stocks in this article are only a starting point. Our full U.S. Domestic Manufacturing U.S. Domestic Manufacturing screener surfaces 16 more companies that pair domestic footprints with equally compelling business narratives. Use Simply Wall St to identify, filter, and analyze the specific catalysts and stories that matter to you, so you can focus on the highest conviction ideas in this theme.

Take Control of Your Investment Journey

If Amprius Technologies or any of these companies sound like a great opportunity, register for FREE with Simply Wall St and add your companies to a Watchlist to monitor the share price against the fair value the ideal entry point.
Once you’ve made your move, manage your holdings with our Portfolio Command Center that filters out the noise to deliver only the most critical, actionable updates.
Throughout your journey, our Community allows you to filter the best ideas from thousands of investor perspectives.
By uncovering hidden catalysts and risks early, you’ll accelerate your decision-making and stay one step ahead of the market.

Seeking Alternatives Before The Crowd Moves

Fresh stock stories can move from quiet buildup to full breakout before anyone notices. Once momentum is strong, entry points can quickly become less attractive, so careful research in advance is important.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

Valuation is complex, but we’re here to simplify it.

Discover if EnerSys might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.

Access Free Analysis

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link