Tariffs on Canadian goods could reshape races in five battleground states


Trump’s escalating trade war with Canada could raise costs for businesses and consumers in key battleground states before voters head to the polls.

President Donald Trump’s escalating trade war with Canada is raising fresh concerns in battleground states ahead of the November midterms.

The U.S. and Canada have imposed tariffs on billions of dollars’ worth of goods, while Washington has also banned nearly $1 billion in Canadian imports, including alcohol, dairy products and motorcycles.

The latest measures took effect Sept. 29 as negotiations remain unresolved.

Trump says the tariffs will bring manufacturing back to the United States and protect American industries. But businesses could cut production, consumers could face higher prices and manufacturers could delay investments.

A FRESH MIDTERM HEADACHE FOR THE GOP JUST HIT A NATIONAL RECORD

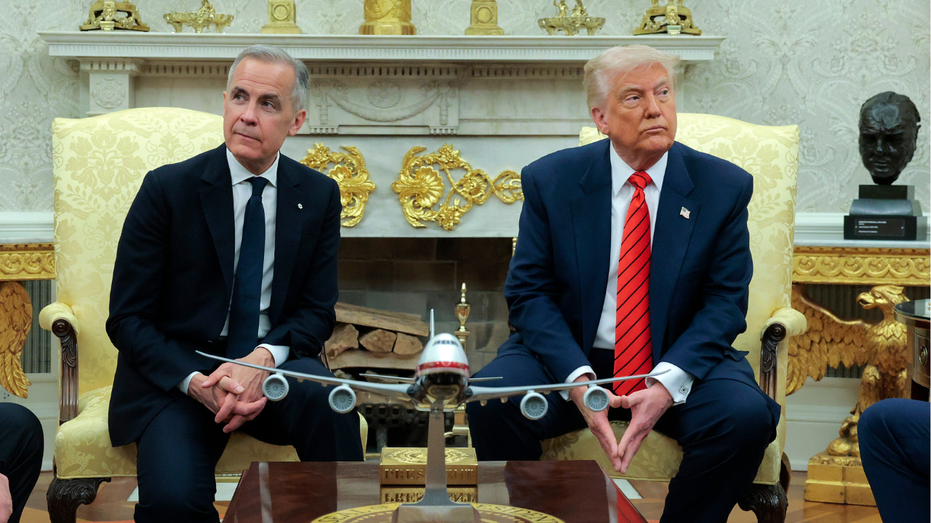
President Donald Trump meets with Canadian Prime Minister Mark Carney in the Oval Office.

The trade fight has escalated under Trump and Canadian Prime Minister Mark Carney, with negotiations breaking down and both countries imposing new measures targeting each other’s goods. (Getty Images)

“The cost of living, cost of goods, cost of doing business is such an important factor for Americans who are going to be casting a ballot,” David Clement, policy director of the Consumer Choice Center, told Fox News Digital.

Clement identified Ohio, Illinois, Michigan, Pennsylvania and Wisconsin as among the states most exposed to Canadian retaliation because of their manufacturing, agricultural and cross-border supply chains.

“American manufacturers or American businesses who rely on Canadian inputs are going to start to feel the pain right in the lead up to going to the ballot box,” he said.

The trade fight has escalated since Canada’s retaliatory tariffs took effect in September. At a recent G20 trade ministers meeting, U.S. Trade Representative Jamieson Greer acknowledged that key issues remain unresolved.

Ohio

Ohio is among the states most vulnerable to Canadian retaliation, with roughly $2.3 billion in exports exposed, according to Clement.

The state’s machinery, transportation, minerals and metals industries depend heavily on Canadian buyers and cross-border supply chains. Tariffs could make Ohio goods more expensive and reduce demand for products made by the state’s manufacturers.

Michigan

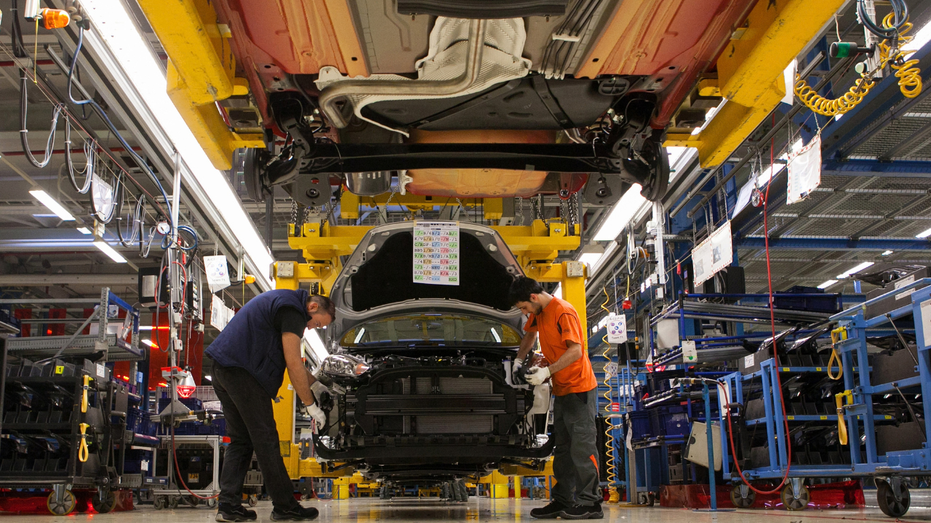
Men are seen working on a car at a Ford factory.

Michigan’s auto industry faces heightened uncertainty as tariffs threaten the deeply integrated supply chain connecting the state with Canada. (Krisztian Bocsi/Bloomberg/Getty Images)

Michigan may face the clearest risk because of its deeply integrated auto industry and close ties to neighboring Ontario.

Auto parts can cross the U.S.-Canada border multiple times before a vehicle is completed, meaning tariffs can increase costs at each stage of production.

A MUST-WIN MIDTERM STATE IS THE REAL LOSER OF TRUMP’S CANADA TRADE WAR

“Most Americans don’t know that a single component on a U.S.-assembled vehicle can cross the border upwards of eight times before it’s actually completed,” Clement said.

The stakes could rise further if the administration moves ahead with a possible 50% tariff on Canadian auto exports beginning Jan. 1 if the countries fail to reach an agreement.

Pennsylvania

Pennsylvania could have just under $1.8 billion in exports exposed, including machinery and equipment, according to Clement.

The state’s manufacturers depend on Canada as a major customer, while many also rely on Canadian inputs. That creates a double burden if tariffs make materials more expensive and finished products harder to sell.

Illinois

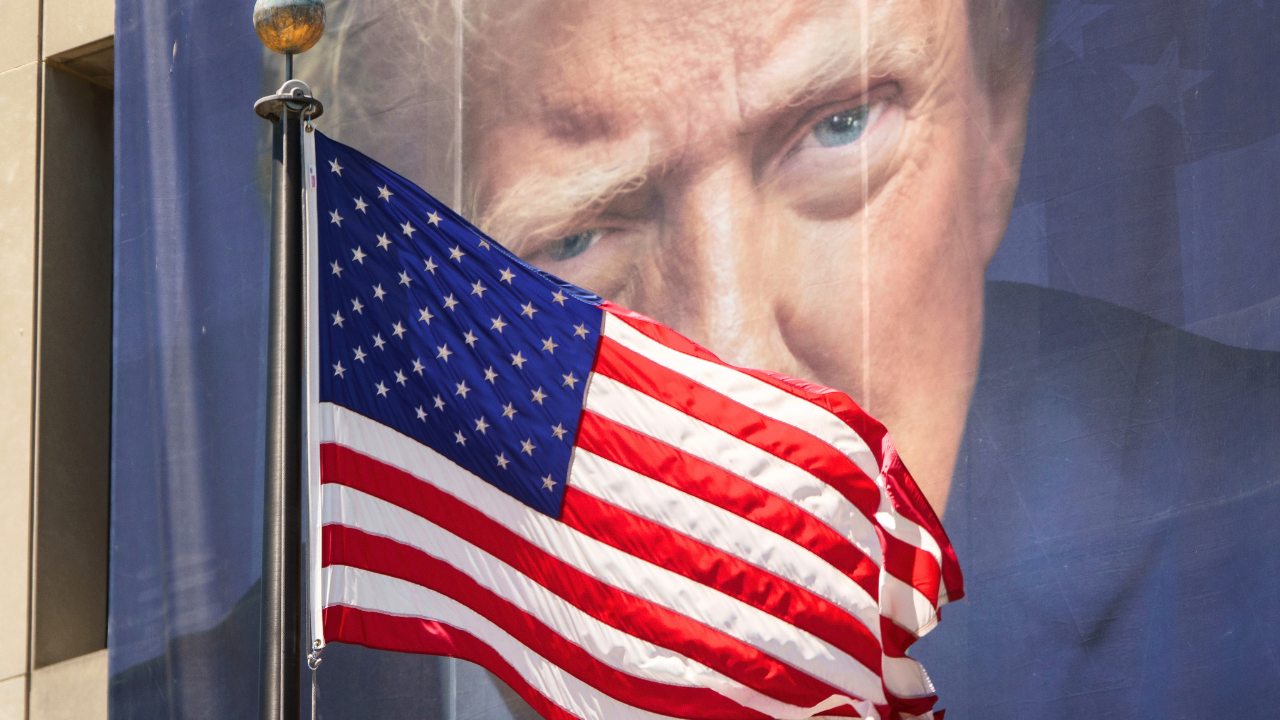
A banner with a portrait of U.S. President Donald Trump is displayed on the front U.S. Department of Labor Frances Perkins Building on May 30, 2026.

President Donald Trump has defended the tariffs as a way to protect American industries and bring manufacturing back to the United States. (Getty Images)

Illinois faces exposure across manufacturing, agriculture and transportation.

Its businesses sell machinery, food products and chemicals to Canada, while companies across the Midwest rely on Canadian materials and components. Tariffs could make those exports less competitive and eventually push higher production costs onto consumers.

Wisconsin

Wisconsin’s economy is closely linked to Canada through agriculture, manufacturing and food production.

The state exports dairy products, machinery and agricultural equipment. Canadian tariffs could make those goods more expensive and give Canadian buyers an incentive to seek alternatives.

Wisconsin farmers and manufacturers are particularly vulnerable because many operate on narrow margins and depend on predictable access to Canadian customers.

CLICK HERE TO GET FOX BUSINESS ON THE GO

Even if Democrats make gains in November, Clement said a change in congressional control would not necessarily end the tariffs because presidents have broad authority over trade policy.

But as the dispute continues, its impact on prices, jobs and businesses could become a decisive issue in the states that determine control of Congress.

Free Training

Source link

Some Canadian manufacturers move to U.S. to survive tariffs


One day last December, Julian Reusing pulled his managers into a virtual meeting to lay bare an uncomfortable truth. 

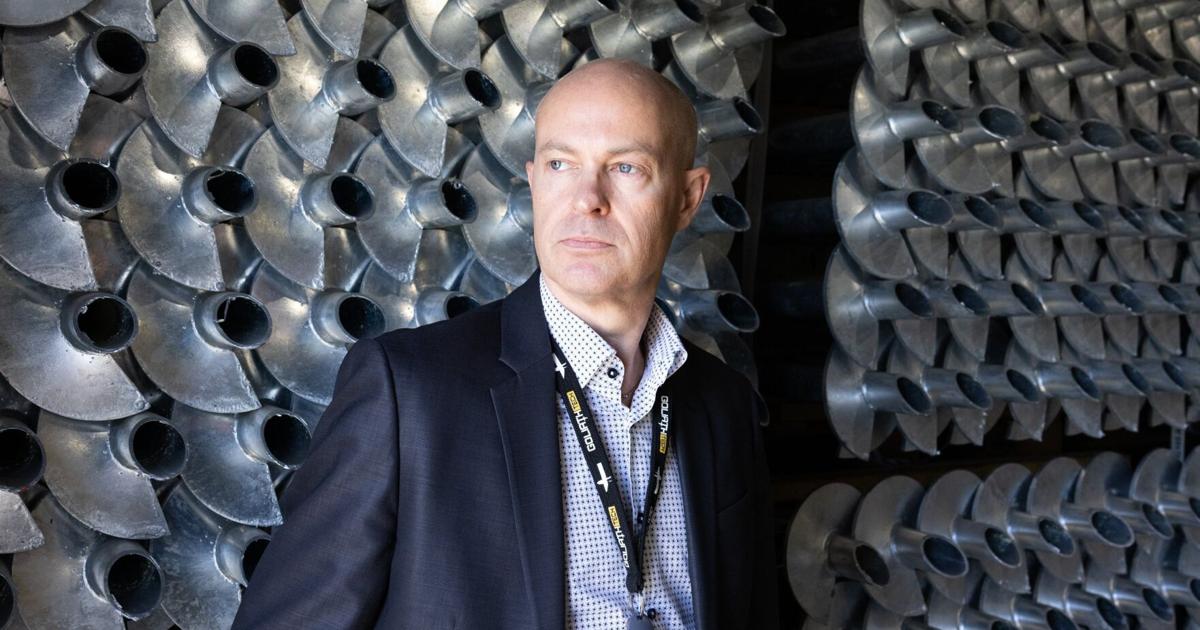
His Quebec company, GoliathTech, a manufacturer of helical screw piles that operates on a franchise model, was getting battered by U.S. tariffs and running out of ways to keep its head above water.

Since the steel tariffs came into effect last March, the company has paid about $3.7 million in tariffs that it has split with its U.S. franchisees.

Reusing, 56, was eager to open a factory south of the border, but he was cash-strapped. Just days earlier, RBC had turned down financing for the company’s European franchise expansion.

Reusing appealed to his own employees for money.

There have been few moments in Canadian history when small and mid-sized manufacturers have faced such pressure. Insurmountable trade barriers with the U.S. have appeared overnight for some companies, suddenly cutting off their largest export market and forcing an urgent need to pivot.

The fight to survive can feel lonely, business owners told the Star. Several said the country’s support falls far short of what they need: the tariff relief programs don’t go far enough and structural threats to Canadian manufacturing competitiveness are making it difficult to replace lost U.S. business.


Julian Reusing.JPG

Over the past two years, GoliathTech’s Julien Reusing approached multiple Canadian government agencies and banks for financing, but was repeatedly turned down. He found his own investors to raise $2.4 million.


Luckily, GoliathTech did not go under that winter. 

Instead, following that pivotal meeting in December, the company raised $900,000 through an equity sale to six of its employees, alongside $1.5 million from a private investor. Reusing opened a small factory in Ohio in March after 10 months of planning in an effort to bypass most U.S. tariffs. He also added 19 European and British franchisees, expanding the firm’s global network to 190 locations as part of a broader restructuring.

“Without a shadow of a doubt, we would be a non-existent company right now if we didn’t make that move,” said Reusing, explaining why he chose to move some production south. “It’s impossible for a company to survive where for every hundred dollars you ship, you have to give fifty dollars to the government.”

Headquartered in Magog, Que., the 13-year-old company is turning a profit for the first time in three years — a turnaround that resulted from Reusing’s own scrambling, with little help from the Canadian government or financial institutions at home.

Many company owners are not nearly as fortunate, and he says Canada needs to do more before more of them are pushed to the brink.

“The government needs to come up with some programs that would teach people how to deal with this, not just offer money,” he said. “I don’t think everybody knows how to deal with a massive revolution.”

Why $7.5 billion in loans isn’t enough

It’s rare to find a clothing company that makes all of its products in Canada — about 95 per cent of the apparel sold here is manufactured outside the country.

When the 50-per-cent U.S. tariffs hit in August, Amit Thakkar feared they could spell the end of his Brampton textile company, Roopa Knitting Mills, which makes fabric for T-shirts, sweatshirts and leggings now caught in the tariff net.

Across the three Canadian clothing businesses he owns, Thakkar employs 120 people, with 50 to 70 per cent of sales destined for the U.S.

His disappointment only grew when Ottawa rolled out a $7.5-billion package to aid tariff-stricken businesses, the majority of which came in the form of loans. 

“If you want to know my honest truth, I think those are all bulls—t,” Thakkar said. “The Canadian government wants to give us loans, but we don’t have customers anymore.”

To Thakkar, the situation is reminiscent of a problem that emerged during the pandemic, when businesses took on emergency debt that some are still struggling to repay years later.

Thakkar says he believes the best way to save his business is for Ottawa to return counter-tariff revenue to companies affected by the trade war, giving them cash to cover tariff costs or lost sales.


GoliathTech 1.JPG

Julien Reusing considers himself lucky to have had the resources and experience to reshape GoliathTech. Many other businesses, he fears, do not have the same room to manoeuvre. 


“If this is like the same in six months,” said Thakkar, “we’re going to be talking about shutting down or moving to the U.S.,” adding that there just isn’t enough buy-in for Canadian-made clothes from the government or domestic consumers.

Before Reusing raised money on his own to restructure his business, he went to the Business Development Bank of Canada (BDC), which launched its Pivot to Grow program last March, offering up to $5 million in loans to help businesses stay afloat and break into new markets.

It seemed like a perfect fit for Reusing’s strategy, but he was denied financing because the business had reported losses in the past two years.

“I’ve spoken with the BDC, Investissement Québec, many different government entities, and we’ve had zero money from the government,” he said. “I lost faith.”

Reusing found investors on his own. 

Dennis Darby, president of Canadian Manufacturers and Exporters, said he is in constant contact with Ottawa to discuss the eligibility and access issues manufacturers are running into. The recent tariff-relief programs are well-intentioned, he said, but their success depends on execution and the speed of approvals.


Tube_laseer_cutter.JPG

A tube laser cutter in action at GoliathTech manufacturing.


“For these smaller manufacturers getting access to that funding, it can’t take six months,” he said.

Companies need more support at home

When Jack Dell’Accio set out to expand Essentia Organic Mattress in 2023, he faced a choice: scale up the company’s factory in Laval, Que., or open a second plant. He chose the latter, investing in a facility in Florida that opened last October.

Mattresses are not subject to the tariffs, and the move was driven purely by logistics costs, particularly the high shipping rates in Canada.

“I have no issues building in Canada all of our raw materials, but it’s our distribution of finished product that has challenges in Canada,” said Dell’Accio, whose company generates about 70 per cent of its sales in the U.S.

The Florida plant has cut Essentia’s shipping costs by about one-third, he said. It also brought an unexpected advantage: with no state personal income tax in Florida, Dell’Accio said Essentia can attract highly skilled engineers with lower salaries than it would need to offer in Quebec.

Alex Greco, senior director of manufacturing and value chains at the Canadian Chamber of Commerce, said tariffs are only one part of the equation when Canadian companies look south, alongside factors such as taxes, regulation, financing and supply chain proximity to customers.


GoliathTech 3.JPG

GoliathTech plate laser operator Stéphane Roy, removes helixes after they’ve been cut.


Canada needs to create a more attractive, business-friendly environment for domestic and foreign investment, so that it can reduce the risk of losing businesses to the U.S., he said.

“We can’t be like psychologists with the president of the United States, but we can control our own competitiveness,” said Greco. 

For Reusing, the solution starts with Canadian financial institutions doing more to back manufacturers.

After the tariffs took effect last March, Reusing approached RBC several times for financing to expand his European franchise network. It was not until December, he said, that his account manager told him the bank was no longer lending against European receivables and inventory.

“It was the ultimate blow because we’ve been with RBC for seven years, very solid, great relationship.”

When asked whether the bank pulled back from corporate financing in Europe, RBC said in a statement that it is unable to comment on individual clients for privacy reasons, but “that financing decisions are made on a client-by-client basis.”

“We see significant opportunity in Europe and are expanding our financing capacity in that market, while also continuing to support clients with cross-border financing needs,” the bank said.


GoliathTech 2.JPG

GoliathTech tube laser technician Josée Roy, who’s worked for nine years at company, arranges tubes. 


Reusing then turned to other Canadian banks, only to be told they would not lend to a company that was “losing money.” He eventually approached a U.S. bank, and the first one he tried agreed to back him.

Last week brought some uplifting news for Canada’s capital markets, as Ottawa unveiled a “productivity mega deduction” as part of its push to attract $1 trillion in new investment over five years.

The measure expands the range of capital assets eligible for businesses to immediately deduct in their first year of use and makes the incentive permanent.

“It’s hard to predict what the future holds for investments in Canada, but this is a policy change that absolutely provides a much stronger incentive for companies to invest in Canada,” said Trevor Tombe, an economics professor at the University of Calgary.

Mutual assured economic destruction

While tariffs have not directly affected Essentia Organic Mattress, they have brought some “social negativity” from Canadian customers when they learn the company operates a factory in the U.S., said Dell’Accio.


GoliathTech 4.JPG

GoliathTech laser cutting supervisor since 2020, Patrick Montmigny, prepares a machine for cutting new plates.


Dell’Accio said opening a plant across the border does not mean scaling back production in Canada, where the company still makes all of its raw materials. If anything, he said, the Florida operation gives Essentia a hedge against any future escalation in trade tensions.

“We’re a Canadian success story that exists in both markets and sometimes it feels that we’re forced to choose sides,” said Dell’Accio. “We can’t. We have a commitment and a customer base in both countries.”

Jim Stanford, economist and director of the Centre for Future Work, said there is no evidence of a migration of jobs to the United States from Canada or elsewhere. But what the data do show, he said, is that tariffs have taken a toll on manufacturing workforces on both sides of the border.

“In terms of Donald Trump’s trade war, this is a case of mutual assured destruction,” he said.

Between January 2025 and August 2026, Canadian manufacturing employment fell by 27,600, from 1.875 million to 1.847 million while the U.S. manufacturing workforce shrank by 35,000. Both countries, however, have seen a modest rebound in those numbers in recent months.

Since the new 50 per cent tariffs took effect, Northern Cables, which has manufactured commercial and industrial power cable with aluminum and copper conductors in Brockville and Prescott, Ont., for 30 years, has had to shut off its cross-border shipping.

Shelley Bacon, the company’s chief executive, said half of the company’s sales go to the U.S. and leadership will have to consider establishing a facility south of the border should the tariffs remain in place to the end of the year.

The Star, simplified

Breaking news, interactive polls, video, and voice notes. Star stories you’ll want to share, delivered where you’re already chatting. Follow the Star on WhatsApp.

Yet that offers no easy workaround, he said. Building an American operation from the ground up represents a massive capital undertaking. 

“If they have trade rules that say you can’t ship product into the country and you have a good customer base and wants to buy from you, you really don’t have a lot of choice here,” he said.

Northern Cables has not laid off any of its 320 workers, instead reassigning them to expand its Canadian product lines and pursue growth domestically. Expanding beyond North America is far from a quick fix. Different standards and measurement systems mean adapting products for Europe could take years, even decades, he added.

But at home, Bacon said some Asian cable makers blocked from the U.S. market by tariffs have been pouring product into Canada at prices so low that his company sometimes cannot even buy the raw materials cheaply enough to match them.

“You can only fight one battle at a time,” Bacon said. “We seem to be fighting two battles at the same time.”

‘If you take your time, you’re going to get eaten up’

It has been 18 months of improvising under pressure for GoliathTech’s Reusing, who kept the company afloat by engineering an entirely new operational playbook to survive the tariff shock.

On top of setting up a U.S. factory, he moved the engineering department to Mexico to cut costs, began manufacturing for two competitors and made 15 trips to Europe to drum up business.

Reusing acknowledged that he was fortunate to have decades of experience to lean on from working in his father’s manufacturing business at 13 to operating a previous franchise business active in 67 countries.

Simply handing out capital won’t solve every problem, Reusing said. What Ottawa really needs to do, he argues, is to launch targeted programs that train business leaders on how to restructure operations and rebuild on the fly.

“You have to do a revolution to your company instantly,” he said. “If you take your time, you’re going to get eaten up.”

Free Training

Source link

Why Are Some Companies Bringing Manufacturing Back to China Despite US Tariffs?


A year after U.S. tariffs pushed companies to diversify production away from China, some businesses are discovering that replacing the country’s manufacturing ecosystem is more difficult and expensive than expected.

The shift reflects the limits of the “China plus one” strategy, under which companies maintained production in China while developing additional manufacturing capacity in countries such as Vietnam, India and Indonesia to reduce exposure to U.S. tariffs.

While diversification continues, some companies are now restoring Chinese suppliers or bringing production back after facing higher costs, supply chain disruptions, shortages of skilled labour and unreliable infrastructure elsewhere.

What’s Happening

Heather Kuang, vice president of China based Dawang Metals, said the company lost business last year when a major U.S. customer moved some orders to India in response to higher tariffs.

Stay ahead of the geopolitical week.

MD Briefing delivers expert analysis across five global fronts — the Indo-Pacific, energy, geoeconomics, European security, and the Middle East — every Monday morning. Free.

The customer has since returned with new orders after encountering problems in India. Dawang itself also explored moving some production overseas but ultimately abandoned the plan.

Kuang said China’s supply chain advantage remains difficult to reproduce elsewhere.

Other companies are reaching similar conclusions.

U.S. retailer Target has moved some orders back to Chinese suppliers, according to two people familiar with the matter, who cited supply chain disruptions and production constraints.

Chinese exporter Jin Chaofeng also moved production back to China after closing a workshop in Ho Chi Minh City that had opened in 2024. He said he struggled to find the necessary equipment in Vietnam and had to import basic supplies such as screws and moulds from China.

After calculating the full cost of operating abroad, Jin said the overall expense was not significantly different from producing in China.

The Tariff Advantage Is Narrowing

One of the main reasons companies moved production away from China was the difference in U.S. tariff rates.

According to Economist Intelligence Unit estimates from July, China faced an effective U.S. tariff rate of about 20%, compared with 6.1% for Vietnam, 13.4% for Indonesia and 4.5% for Thailand.

That gap, however, has narrowed as Washington expanded tariffs across a wider range of countries.

The changing tariff environment has made it harder for companies to justify relocating production solely to avoid duties on Chinese goods.

Chinese manufacturers are also reconsidering overseas investment as the benefits of lower tariff rates become less certain.

Beyond Tariffs

For many companies, the decision is increasingly about more than tariffs.

Access to reliable electricity and the broader manufacturing infrastructure have become important considerations, particularly after the Middle East crisis pushed up energy costs and highlighted vulnerabilities in global energy markets.

Stanislaw Krykun, CEO of Poland based packaging company DST Pack, said his six year Chinese manufacturing partner helped the company navigate a period when plastic input costs rose sharply.

DST Pack currently sources about 80% of its production from a factory in Shenzhen, with the remainder coming from established backup plants in the United States and Europe.

Those alternatives cost two to three times more per unit.

Krykun said he had rejected the idea of relocating to Southeast Asia after seeing a business partner struggle with production and exports in Vietnam.

A Qingdao based lawyer who advises manufacturers, Guan Baokui, also pointed to electricity supply problems in Vietnam and Indonesia, describing their power systems as unstable and discontinuous.

China’s Manufacturing Ecosystem

The experience of these companies highlights China’s broader manufacturing advantage.

The country has developed extensive networks of suppliers, specialized equipment manufacturers, skilled workers and supporting industries. Companies can often source multiple components and services within the same industrial ecosystem.

This means that moving one factory does not necessarily mean moving only production. Businesses may also need to recreate the network of suppliers, machinery, logistics and technical expertise that supports that factory.

For companies that have already spent years building relationships in China, the cost and complexity of reproducing that ecosystem elsewhere can outweigh the benefits of lower tariffs.

Diversification Has Not Ended

The return of some manufacturing to China does not mean the supply chain diversification trend has stopped.

Vietnam remains one of the biggest beneficiaries of companies seeking alternatives to China and continues to attract billions of dollars in foreign investment.

Some businesses are also maintaining production outside China as insurance against future policy changes.

Yu Yangxian, who sells electric lockers and vending machines, said her company is keeping about one eighth of its total capacity in Vietnam as a hedge.

She said the company could expand production there again if tariffs rise sharply.

This suggests that many companies are moving toward a more flexible strategy rather than choosing China or another country exclusively.

Why It Matters

The developments show that tariffs alone cannot determine where global manufacturing takes place.

Lower tariffs can make countries such as Vietnam, Indonesia and Thailand attractive, but companies must also consider electricity, equipment availability, supplier networks, labour skills, logistics and the overall reliability of the production system.

For China, the return of some orders provides evidence that its manufacturing ecosystem remains difficult for competitors to replicate despite rising geopolitical and trade pressures.

For companies, however, maintaining production in China still carries tariff and geopolitical risks. That is why many are keeping alternative capacity elsewhere even when Chinese production remains cheaper or more reliable.

Key Stakeholders

Chinese manufacturers continue to benefit from established supplier networks, skilled labour, infrastructure and production capabilities.

U.S. companies and retailers are balancing tariff costs against the reliability and overall cost of alternative manufacturing bases.

Vietnam, India and Indonesia remain important destinations for companies pursuing supply chain diversification.

Thailand also retains an advantage through comparatively low U.S. tariff rates, although the gap with China has narrowed.

The U.S. and Chinese governments remain central to the outlook because future tariff decisions could alter companies’ calculations again.

What’s Next

Businesses are watching the expected meeting between Donald Trump and Chinese President Xi Jinping for signs of whether Washington and Beijing can reduce trade barriers on some non sensitive goods.

However, exporters do not expect the meeting to resolve the broader uncertainty.

Companies are likely to continue maintaining manufacturing capacity across multiple countries rather than relying entirely on a single production base.

Analysis

The return of some manufacturing to China reveals a weakness in the assumption that supply chains can be relocated simply by following tariff differences.

China’s advantage is not just the cost of producing an individual product. It is the dense industrial ecosystem surrounding that production. When companies move factories abroad, they may discover that machinery, components, skilled workers, electricity and logistics cannot be replicated at the same cost or speed.

At the same time, the diversification strategy has not failed completely. Companies are increasingly using countries such as Vietnam as backup capacity rather than complete replacements for China.

This could lead to a more fragmented global manufacturing system in which China remains the core production hub for many businesses while Southeast Asia and other emerging hubs provide alternatives.

The result may therefore be less of a reversal of globalization than a more complicated form of it. Companies are learning that reducing dependence on China does not necessarily mean abandoning China. Instead, they may need to maintain Chinese production while building enough alternative capacity elsewhere to protect themselves against future tariffs, geopolitical shocks and supply chain disruptions.

With information from Reuters.

Free Training

Source link

Questions Answered on Trade, Tariffs and U.S. Manufacturing


C-SPAN

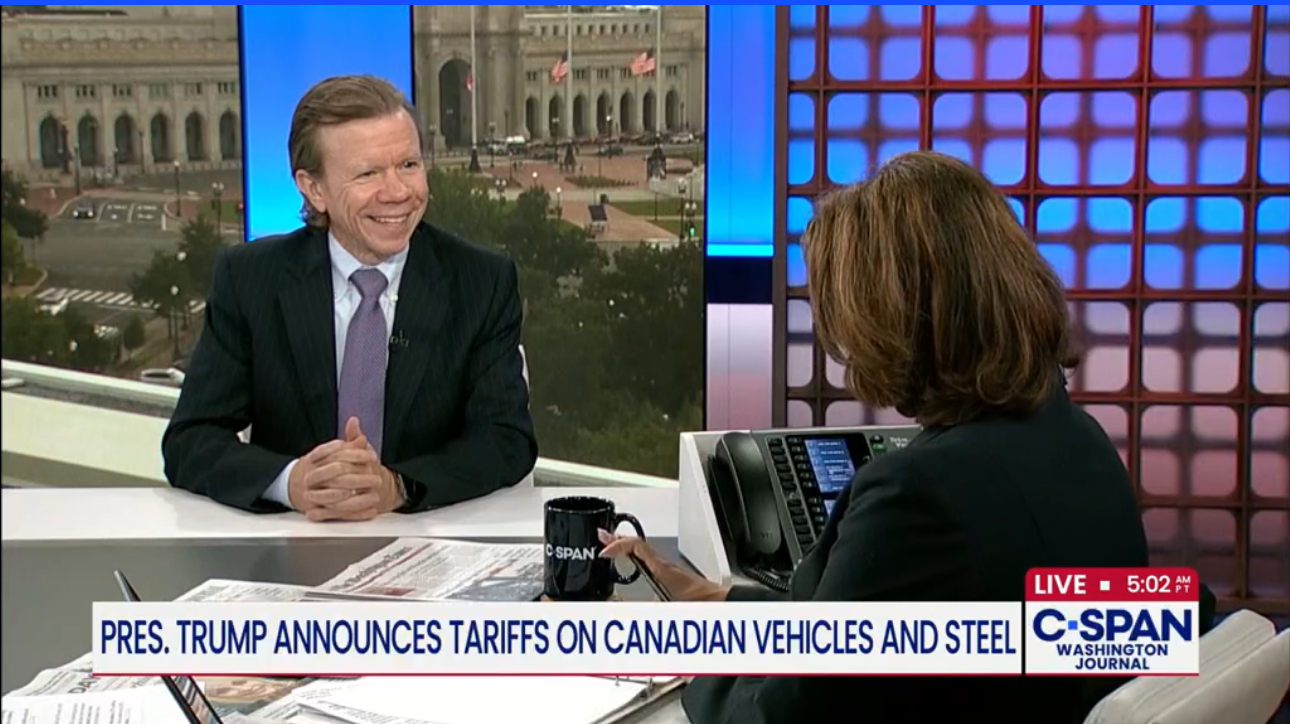
AAM’s Scott Paul gets into detail live on C-SPAN.

Unless you’ve been living under a rock, you’ve likely noticed that tariffs – a certain president’s favorite word – have been in the news a lot recently. And tariffs can have a significant effect on U.S. manufacturing activity. So, how to analyze manufacturing’s outlook? Alliance for American Manufacturing (AAM) President Scott Paul was on C-SPAN’s Washington Journal program last week, where he tackled that question and others.

You can watch the entire segment here. Or see a couple of clips from the appearance below:

How are America’s factories faring in 2026?

Paul wrote about this recently on AAM’s blog.

“There was a period where manufacturing was having some challenges. I think we’re out of that now,” he said. “You’re seeing some of the results of the factory construction boom. Some of this goes back to the Biden administration, there’s evidence of a lot of factory construction that started in 2022 and 23 with respect to semiconductors, pharmaceuticals, some other goods like that, and has been continuing, although at a slightly lower rate, and now people are coming to fill jobs in those factories.”

AI is Bringing a New Generation of Workers to U.S. Factories

“Young people for a whole generation have been conditioned not to look at manufacturing for a career and there’s strong evidence that is changing, particularly as AI hits those entry-level positions that are white collar and all of a sudden the idea of putting on a tool belt or going to trade school and potentially making 80 or 100,000 dollars as an electrician at a factory looks a lot more appealing,” Paul said.

Manufacturing is a ladder to the Middle class

“I think there has been an imbalance between labor and capital that’s been well documented, that has expanded over the last couple of decades,” Paul said. “I do think manufacturing is an industry where you can still find good wages in the United States and particularly for the majority of Americans who won’t have a four-year degree. It’s a ladder to the middle class.”

China’s currency is crushing U.S. manufacturing

“There have been active efforts over the decades to keep the value of the Chinese currency low in order for them to gain a trade advantage. It makes their goods cheaper to send overseas. I wish the Trump administration did more on currency, particularly with respect to China,” Paul said. “I think that’s necessary to have a better relationship moving forward. Hopefully Trump will raise that with [Chinese leader Xi Jinping] when they meet in September.”

Are Chinese autos coming to the United States?

Don’t let ’em in, we say.

“What the Carney government in Canada has done, I think, is defeating for the Canadian auto industry, and that is to turn to China and to say to some of the Chinese auto companies, ‘come in. We’re going to allow you to import some cars into our market. You can enter into joint ventures with some of our companies,’” Paul said. “And what we’ve seen happen in other places around the world that have tried to accommodate that is that it has completely wiped out the auto industries and the Chinese companies are taking over. That’s happening in real time right now in Europe. It’s happened in the UK. It happened in Australia.”

U.S. national security depends on strategic tariffs

“[National security] is the basis for the tariffs that have been in place since 2018 on steel and aluminum. That was under section 232,” Paul said. “And those have been durable. Biden kept those tariffs on. And when you hear Members of Congress raise concerns about tariffs its generally not those steel and aluminum tariffs, it’s some of the other trade actions the administration has taken. That’s not universally true but I think generally true. I completely agree we have to have a baseline productive capacity for critical metals like steel and aluminum that go into defense purposes.”  

You can find the entire C-SPAN segment here.

Free Training

Source link

XTEND Highlights U.S. Drone Manufacturing Expansion as New Tariffs Strengthen Case for Domestic NDAA-Compliant Supply Chain


~ New Tariffs of Up to 100% on Imported Drones Underscore the Case for the Domestic, NDAA-Compliant Manufacturing Base XTEND Has Been Building ~

~ Company’s Growing Tampa-Based XFAB Facility and U.S. Manufacturing Relationships Support XTEND’s Plans to Scale Production as America Reduces Reliance on Foreign-Made Drone Technology ~

TAMPA, Fla., Aug. 14, 2026 (GLOBE NEWSWIRE) —

JFB Construction Holdings (Nasdaq: JFB) announced today that XTEND, a leader in AI-powered autonomy and software-defined robotics, is positioned to support America’s newly announced drive to strengthen its domestic drone industrial base. President Trump this week signed a proclamation imposing tariffs of up to 100% on imported drones and certain drone components, citing national security risks tied to foreign-made, and in particular Chinese-made, unmanned aircraft technology and the need to strengthen the U.S. drone industrial base. Under the proclamation, drones weighing more than 25 kilograms or equipped with thermal imaging, along with their docking stations and critical components, are subject to a 100% tariff, while smaller drones lacking security-sensitive features and other drone components face a 25% tariff, with most provisions taking effect within 21 days of signing.

As the United States moves decisively to strengthen its domestic drone industrial base and reduce dependence on Chinese technology, XTEND finds itself exactly where it was built to be.

XTEND has been developing and supplying NDAA-compliant drone technology and robotic systems to the U.S. Department of War (“DOW”), winning U.S. defense programs and investing in the American manufacturing infrastructure needed to produce them at scale in the United States.

XTEND’s growing U.S. manufacturing facility, XFAB, in Tampa, Florida, which XTEND is continuing to develop and expand, was built around this exact vision, which is directly aligned with the objectives of the new proclamation: bring critical drone technology, components and manufacturing to the United States and create a secure American alternative to foreign-controlled supply chains. The Tampa facility is the U.S. anchor of XTEND’s global XFAB manufacturing network, which combines localized regional production with centralized software innovation through its proprietary XTEND Operating System (XOS) across facilities in the United States, the United Kingdom, Singapore, Israel, and Latvia. Earlier this month, XTEND announced that it had produced seven robotic platforms across its five global XFAB facilities in a single week, all powered by XOS. As XTEND continues to build out its U.S. production capacity, it also works with U.S.-based manufacturers to support increased production. XTEND believes it brings not only its technology, but also its proven XFAB model for building a network of American manufacturing at scale.

Beyond defense, XTEND is also expanding into the private security market, and expects its ability to deliver NDAA-compliant drones manufactured in the United States to be a competitive advantage there as well, as private security customers increasingly prioritize secure, domestically manufactured systems.

Today, that vision has become a national priority.

XTEND wasn’t built in response to this moment. XTEND was built for it.

“We made the bet that America would need a homegrown, NDAA-compliant alternative to Chinese drone technology, and we are building XFAB, our people and our supply chain around that bet,” said Aviv Shapira, Chief Executive Officer of XTEND. “These tariffs validate what our defense customers have known for years: security and resilience start with who builds your technology and where. We’re not reacting to this moment; we’ve been preparing for it since day one, and we’re building the capacity to scale.”

To sign up to receive press releases in real time, please visit ir.xtend.me.

As announced on February 17, 2026, JFB Construction Holdings (Nasdaq: JFB) and XTEND entered into a definitive agreement to combine in an all-stock transaction. The business combination is further supported by strategic investments from Eric Trump, Unusual Machines, American Ventures, LLC, Protego Ventures, and Aliya Capital. The U.S. Securities and Exchange Commission declared the registration statement on Form S-4 relating to the transaction effective on August 11, 2026, clearing the way toward an anticipated closing on September 1, 2026, subject to customary closing conditions. Upon closing, the combined company will be renamed XTEND AI Robotics, Inc., a U.S. public company incorporated in Delaware, and is expected to trade on the New York Stock Exchange under the ticker symbol “XTND.” The closing will complete XTEND’s transition to a U.S.-domiciled public company, aligning its corporate structure with its growing American manufacturing footprint.

About XTEND

XTEND is a leader in software systems and artificial intelligence-powered robotics, deployed in high-threat, complex operational environments where human exposure carries significant risk. Powered by its proprietary XTEND Operating System (XOS), XTEND’s integrated software and advanced robotic hardware solutions are designed to provide autonomy at the edge. Operating across defense, law enforcement, and private security missions through a platform of robots, drones, and robotic subsystems, XTEND’s open architecture platform facilitates scalability across partners and third-party applications. With over 12,500 systems deployed in over 30 countries, XTEND’s solutions have been validated in five combat zones and operationally deployed by national defense, special-mission units, and security organizations across the globe. Founded in Tel Aviv, Israel, and headquartered in Tampa, Florida, XTEND delivers NDAA-compliant solutions through a global network of regional XFAB manufacturing facilities located in the U.S., the U.K., Singapore, Israel, and Latvia. XTEND has previously announced a proposed business combination with JFB Construction Holdings (Nasdaq: JFB); upon closing, the combined company will be renamed XTEND AI Robotics, Inc., a U.S. public company incorporated in Delaware. For more information, visit

www.xtend.me

.

About JFB Construction Holdings

JFB Construction Holdings (Nasdaq: JFB) is a real estate development and construction company that has provided general contracting and construction management services in 36 U.S. states. For more information, visit the company’s SEC filings at

www.sec.gov

.

Forward-Looking Statements

This communication contains, and oral statements made from time to time by our representatives may contain, forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended (the “Securities Act”), and Section 21E of the Securities Exchange Act of 1934, as amended. These forward-looking statements generally include statements regarding the anticipated impact of recently announced U.S. tariffs on imported drones and drone components, XTEND’s ability to scale U.S. manufacturing at its XFAB facility, XTEND’s relationships with U.S.-based manufacturers, its ability to build a network of U.S. manufacturing at scale, and their anticipated contribution to increased production, XTEND’s expansion into the private security market and the anticipated benefits of U.S.-based, NDAA-compliant manufacturing in that market, the potential transaction between XTEND Reality Expansion Ltd. (“XTEND”) and JFB Construction Holdings (“JFB”), including statements regarding the expected impacts and benefits of the potential transaction, the timing of the transaction closing, and strategic initiatives for XTEND AI Robotics, Inc. (“NewCo”) following the closing. All statements other than statements of historical facts contained in this communication may be forward-looking statements. In some cases, you can identify forward-looking statements by terms such as “may,” “will,” “outlook,” “should,” “expects,” “plans,” “anticipates,” “could,” “intends,” “targets,” “projects,” “contemplates,” “believes,” “estimates,” “predicts,” “potential” or “continue” or the negative of these terms or other similar expressions.

The forward-looking statements in this communication are only predictions. XTEND’s and JFB’s management have based these forward-looking statements largely on their current expectations and projections about future events and financial trends that management believes may affect its business, financial condition and results of operations. These statements are neither promises nor guarantees and involve known and unknown risks, uncertainties and other important factors that may cause actual results, performance or achievements to be materially different from what is expressed or implied by the forward-looking statements, including, but not limited to: the ultimate scope, duration, and implementation of recently announced tariffs on imported drones and components, and their impact on XTEND’s costs, competitive position, and customers; the proposed transaction with JFB may not be consummated, or may not close on the anticipated timeline; there may be difficulties integrating the two companies and realizing the expected benefits of the transaction; XTEND’s ability to complete the continued development of, and scale U.S.-based manufacturing at XFAB to meet increased demand; XTEND’s ability to maintain and expand its relationships with U.S.-based manufacturers, to build a network of U.S.-based manufacturing at scale, and to realize the expected benefits of these relationships; XTEND’s ability to successfully expand into the private security market; XTEND’s dependence on a limited number of defense and governmental security customers for a substantial portion of its business; significant delays or reductions in appropriations, XTEND’s programs and certain government funding and programs more broadly, including as a result of a prolonged continuing resolution and/or government shutdown, and/or related to the global security environment or other global events; increased competition within XTEND’s and JFB’s markets; changes in procurement and other U.S. and foreign laws, including changes through executive orders and tariff actions, contract terms and practices applicable to our industry; disruptions in supply chains and the cost of components and materials; cyber and other security threats or disruptions faced by XTEND and JFB, its customers or its suppliers and other partners; and XTEND’s ability to innovate, develop new products and technologies, and maintain technologies to meet the needs of XTEND’s customers. In addition, a number of important factors could cause JFB’s, XTEND’s or NewCo’s actual future results and other future circumstances to differ materially from those expressed in any forward-looking statements, including but not limited to those important factors discussed in the section entitled “Risk Factors” in the registration statement on Form S-4 filed by JFB and NewCo, as any such factors may be updated from time to time in other filings with the Securities and Exchange Commission (the “SEC”), which are available on the SEC’s website at

https://www.sec.gov

and on XTEND’s investor relations site at

https://www.xtend.me/newsroom

and JFB’s investor relations site at

https://investors.jfbconstruction.net/

. Forward-looking statements speak only as of the date they are made and, except as may be required under applicable law, neither XTEND nor JFB undertakes any obligation to update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.

Important Information for Investors and Stockholders

This communication is for informational purposes only and is not intended to, and does not, constitute an offer to sell or the solicitation of an offer to buy any securities or a solicitation of any vote or approval, nor shall there be any issuance or sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction. Investors and security holders of XTEND and JFB are urged to read the information statement/prospectus and registration statement on Form S-4, and any other document that has been or will be filed with the SEC in connection with the proposed transaction, carefully and in their entirety, because they contain important information. Investors and security holders will be able to obtain free copies of these documents through the website maintained by the SEC at

https://www.sec.gov

, or free of charge on JFB’s website at

https://investors.jfbconstruction.net/

.

JFB Construction Holdings Contact:

CORE IR

Mike Mason

516-222-2560


[email protected]

XTEND Media Contact:

Headline Media

Sarah Small

929-255-1449


[email protected]

XTEND Investor Relations:

MZ North America

Shannon Devine


[email protected]


203-741-8811

Free Training

Source link

Trump Slaps Up to 100% Tariffs on Drones to Boost US Manufacturing, Citing National Security Risks


US President Donald J. Trump has signed a proclamation imposing tariffs of up to 100% on imported drones and certain drone components, citing national security risks and vulnerabilities arising from foreign dependence on critical Unmanned Aircraft System (UAS) components.

“The Proclamation imposes a 100% ad valorem tariff on drones of a certain size or with certain capabilities that are particularly sensitive for national security purposes,” the White House said. The tariff covers drones with a maximum takeoff weight of more than 25 kg, drones with thermal imaging capabilities, their docking stations and certain critical components.

The proclamation imposes a 25% ad valorem tariff on certain smaller drones that lack capabilities considered particularly sensitive to national security, as well as other drone components.

For selected trading partners, the tariff rates will be lower. Drones and components from the European Union, Japan, Liechtenstein, Republic of Korea, Switzerland and Taiwan will attract a 15% tariff, while those from the UK will face a 10% tariff, provided “substantially all hardware, software, and technology originates from within these countries and the United States.”

“The tariffs will take effect 21 days after signing,” the White House said. Tariffs on non-sensitive drone components will take effect after 180 days. Products and components approved by the Department of War for exemption from the Federal Communications Commission’s Covered List within 20 days of signing will also face tariffs after 180 days.

The proclamation authorises the Commerce Secretary to establish an onshoring programme for companies making new investments in US drone and component manufacturing.

“Drones are a key technology in modern armed conflict and critical for present and future U.S. military operations,” the White House said, adding that commercial and military drones rely on foreign sources for critical UAS components, creating “significant risks to U.S. national security and creates cybersecurity vulnerabilities.”

The administration said “U.S. drone production needs to be expanded rapidly” to strengthen national and economic security and support jobs in the country’s defence and defence-adjacent industrial base.

The latest move builds on Trump’s broader use of Section 232 tariffs to protect industries considered critical to US national security. The White House said the administration has imposed or strengthened tariffs on steel, aluminium, copper, trucks, automobiles, timber, lumber and pharmaceuticals since Trump’s return to office..

Free Training

Source link

3 U.S. Manufacturing Stocks Investors Are Watching After New China Forced Labor Tariffs


Fresh US tariffs tied to alleged forced labor in China are reshaping global supply chains and putting a spotlight on companies that make more at home. This creates potential openings and risks as money shifts toward U.S. based manufacturing strength. This article walks through three U.S. domestic manufacturing screener stocks that are closely exposed to this news and explains what the headlines could mean for your watchlist today.

The three stocks in focus below are just a starting sample, and the full U.S. domestic manufacturing screen surfaced 44 more companies with equally compelling onshoring and reshoring narratives that are not covered in this article. If you want to identify and analyze potential high conviction ideas at your own pace, head straight into the U.S. Domestic Manufacturing (Onshoring/Reshoring) screener.

Atkore (ATKR)

Atkore is a US based manufacturer of electrical conduit, cable management and safety products that sit inside the walls, ceilings and perimeters of factories, data centers and other critical infrastructure. The Electrical segment is the core of the business, generating about US$2.1b of revenue, while Safety & Infrastructure adds around US$836 million. Atkore has a market cap of roughly US$3.2b.

Atkore sits at the center of the onshoring story because many of its conduits, cable trays and support systems are made domestically and are essential for new and expanded US plants. The latest US tariffs on Chinese suppliers reduce import competition and align with management commentary that tariffs on steel, PVC and copper products tend to be a tailwind for the company. However, higher input costs and price pressure on PVC conduit remain real risks. When you add in the planned all cash acquisition by Prysmian at US$95 per share, ongoing tariff policy changes and a history of earnings volatility, you have a business that could benefit from supply chain shifts but still asks investors to think carefully about pricing power, project timing and how much of the U.S. manufacturing uptrend is already reflected in expectations.

Atkore’s tariff tailwinds and onshoring exposure could be masking a very different risk reward picture under the surface. Before the Prysmian deal closes, read the 2 key rewards and 2 important warning signs

ATKR Discounted Cash Flow as at Aug 2026ATKR Discounted Cash Flow as at Aug 2026

Build your own onshoring shortlist around Atkore

Atkore and the two other stocks in this article all came from a single screener, but the real value comes from setting your own filters. Use our flexible Screener to mix metrics like valuation, growth and balance sheet strength, or lean on our curated Investing Ideas if you prefer ready made shortlists.

Comfort Systems USA (FIX)

Comfort Systems USA is a Houston based contractor that designs, installs and maintains heating, cooling, electrical and plumbing systems for commercial, industrial and institutional buildings across the United States. The company generates the bulk of its revenue from Mechanical Services at about US$8.0b, with Electrical Services contributing roughly US$3.2b. Comfort Systems USA has a market cap of around US$60.2b.

Comfort Systems USA sits in the slipstream of reshoring and AI infrastructure spending, wiring and plumbing the data centers, fabs and hospitals that global supply chains now depend on. A record project backlog, a growing modular construction footprint and rising service revenue give the company more visibility and pricing power. At the same time, tariff driven material cost swings and dependence on large tech related projects keep execution risk front and center. With management openly discussing how scale, contract structures and early material purchasing help them handle supply chain shocks, investors weighing this stock have more to consider than just headline growth numbers.

Comfort Systems USA looks like a simple contractor; however, accelerating orders and modular projects hint at something bigger in reshoring and AI buildouts. Get the full story in the analysis report for Comfort Systems USA

NYSE:FIX Earnings & Revenue Growth as at Aug 2026NYSE:FIX Earnings & Revenue Growth as at Aug 2026

JBT Marel (JBTM)

JBT Marel is a Chicago based food and beverage equipment company that supplies automated processing, packaging and material handling systems used in everything from poultry and meat plants to ready meals, dairy and pet food facilities worldwide. It also sells automated guided vehicle systems for warehouses, auto plants and hospitals. JBT Marel has a market cap of about US$6.3b.

JBT Marel gives you exposure to two themes at once: automation in food production, and the push to bring more high value equipment manufacturing closer to U.S. customers. Management is already discussing tariff headwinds of around US$10 million to US$15 million per quarter and an annualized cost impact of roughly US$50 million to US$60 million. At the same time, the company is working to shift sourcing and some production to the U.S. and other regions to offset those costs. Along with merger synergies, growing aftermarket and software revenue, and a board that has reaffirmed 2026 guidance despite tariff developments, this creates a situation where the potential benefits are identifiable while the tariff, integration and debt risks still require careful analysis.

JBT Marel is reshaping food automation just as tariffs bite and sourcing shifts closer to U.S. customers. See how the tariff bill, merger plans and debt profile really stack up in the analysis report for JBT Marel

NYSE:JBTM Earnings & Revenue Growth as at Aug 2026NYSE:JBTM Earnings & Revenue Growth as at Aug 2026

Seeking Alternatives Before The Crowd Moves

Fresh ideas do not stay under the radar for long. By the time momentum is high, the easiest entry points can be gone. Scan these curated lists and consider getting in early.

  • Target income that can keep working for you through changing cycles by reviewing our curated 8 dividend fortresses that focus on durability as much as yield.
  • Spot early movers in critical infrastructure and explore potential grid upgrade trends with a focused sweep through 36 power grid technology and infrastructure stocks while it still feels under followed.
  • Consider positioning ahead of potential data center and automation buildouts by screening 55 AI infrastructure stocks before interest increases and more investors start focusing on the same tickers.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: AI Stock Screener & Alerts

Our new AI Stock Screener scans the market every day to uncover opportunities.

• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies

Or build your own from over 50 metrics.

Explore Now for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

AI demand, U.S. tariffs reshape South Korean manufacturing


An engineer walks inside a laboratory of Taiwan Semiconductor Research Institute at a Science park in Hsinchu county, Taiwan. Photo by RITCHIE B. TONGO/ EPA

July 27 (Asia Today) — Growing artificial intelligence demand and stronger trade barriers are rapidly reshaping the production and supply chains of South Korea’s major manufacturing industries, the Bank of Korea said Monday.

The central bank said Taiwan has become South Korea’s second-largest semiconductor export destination as the AI supply chain draws Korean memory-chip producers closer to Taiwanese manufacturers.

Meanwhile, South Korean automakers are increasing production in the United States and expanding hybrid vehicle exports as tariffs and U.S. industrial policies make direct exports less competitive.

The findings were included in the Bank of Korea’s Map of Production and Supply Chains for South Korea’s Major Manufacturing Industries. The report used data from 2024 and 2025 to examine 11 industries, including semiconductors, automobiles, steel, shipbuilding and petrochemicals.

South Korean semiconductor exports to Taiwan nearly tripled from $12.78 billion in 2022 to $36.77 billion in 2025.

Taiwan’s share of South Korea’s semiconductor exports increased from 9% to 19.9%, moving it from the fourth-largest export destination to the second largest.

China remained the largest destination, but its share fell from 53.1% in 2022 to 40.3% in 2025.

The central bank attributed the change to a shift in demand from conventional dynamic random-access memory chips to graphics processing units and high-bandwidth memory used in AI systems.

The AI semiconductor supply chain generally involves U.S.-based Nvidia designing graphics processors, Taiwan Semiconductor Manufacturing Co. producing and packaging the chips and Samsung Electronics and SK hynix supplying high-bandwidth memory.

That structure has increased the volume of South Korean semiconductor products shipped to Taiwan.

Semiconductors have also become more important to South Korea’s overall manufacturing sector.

Domestic semiconductor production rose from 74 trillion won in 2014 to 210.8 trillion won in 2024 ($50.4 billion to $143.6 billion). Its share of total manufacturing production doubled from 5% to 10.1% during the same period.

Production remains heavily concentrated in the greater Seoul area, which accounted for 82.3% of the national total. The Chungcheong region accounted for another 14.7%.

Major facilities in the Seoul metropolitan region include Samsung Electronics plants in Hwaseong, Pyeongtaek and Giheung and SK hynix’s plant in Icheon.

China’s growing influence was most apparent in South Korea’s automobile import market.

The share of vehicle imports from China increased from 3.5% in 2022 to 37.2% in 2025. Chinese-made vehicles accounted for about 70% of South Korea’s electric vehicle imports by value in 2025.

The report attributed the increase to China’s price competitiveness and its extensive supply chain covering vehicles, batteries and components.

The United States remained South Korea’s largest automobile export market in 2025. Shipments were valued at $30.15 billion and accounted for 41.9% of total finished-vehicle exports.

However, the United States’ share of South Korea’s electric vehicle exports fell from 33.6% in 2022 to 5.2% in 2025.

The central bank said U.S. subsidies, local production requirements and tariff barriers had weakened the competitiveness of electric vehicles manufactured in South Korea and shipped directly to the United States.

South Korean automakers have responded by expanding U.S. factory operations while increasing exports of hybrid vehicles.

Hybrids’ share of South Korea’s finished-vehicle exports rose from 11.6% in 2022 to 20.4% in 2025.

The shift reflects automakers’ efforts to respond to slowing electric vehicle demand and insufficient charging infrastructure by offering vehicles that combine electric motors with internal combustion engines.

— Reported by Asia Today; translated by UPI

© Asia Today. Unauthorized reproduction or redistribution prohibited.

Original Korean report: https://www.asiatoday.co.kr/kn/view.php?key=20260727010009651

Free Training

Source link

3 US Manufacturing Stocks Better Placed For New Tariffs


Tariffs have moved from political headline to portfolio issue, with new US import duties of 10% to 12.5% affecting nearly all goods from about 60 trading partners and drawing immediate legal and international pushback. For US domestic manufacturing stocks, this mix of higher import costs, possible retaliation, and supply chain strain can create both fresh openings and new risks. This article looks at how that backdrop connects to companies in the US Domestic Manufacturing Stocks screener and highlights 3 stocks that appear positively exposed to these tariff moves.

Astec Industries (ASTE)

Overview: Astec Industries designs and builds heavy equipment and systems used mainly for road building, aggregates, and related construction work, supplying everything from asphalt and concrete plants to crushers, screens, conveyors, and wood processing machines to contractors, materials producers, quarries, and public agencies worldwide.

Operations: Astec generates most of its revenue from Infrastructure Solutions at US$893.8m and Materials Solutions at US$623m, with the United States contributing about US$1.2b of sales.

Market Cap: US$1.29b

Astec Industries stands out in the new tariff regime because it manufactures its road building and materials equipment in the US, while many rivals import finished units that are now subject to 10% to 12.5% duties. Management has already modeled tariff impacts on costs, tightened supplier scrutiny, and used pricing and dual sourcing to help offset input pressures. This matters for a business where margins are still relatively low and earnings were affected by a US$30.2m one off loss. At the same time, analysts see potential for earnings growth supported by US infrastructure spending and higher margin parts and acquisitions such as TerraSource. That combination of possible tariff tailwinds, operational execution, and valuation debate is a key consideration for investors assessing Astec.

Astec Industries looks like a classic tariff era beneficiary, with US production, margin work and acquisitions pulling in the same direction. However, the real story sits in the 4 key rewards and 2 important warning signs

NasdaqGS:ASTE Earnings & Revenue History as at Jul 2026NasdaqGS:ASTE Earnings & Revenue History as at Jul 2026

Insteel Industries (IIIN)

Overview: Insteel Industries manufactures steel wire reinforcing products used to strengthen concrete in bridges, parking decks, industrial buildings, data centers, drainage systems and residential slabs, with a portfolio centered on prestressed concrete strand and engineered welded wire reinforcement sold to concrete product makers, rebar fabricators, distributors and contractors.

Operations: Insteel generates about US$707.7m of revenue from concrete reinforcing products, with roughly US$705.4m coming from the United States and around US$2.2m from foreign markets.

Market Cap: US$626m

Insteel Industries sits at the intersection of US infrastructure spending and tariff policy, which makes it particularly relevant after the latest broad import duties. The company is closely tied to domestic construction demand, with 9M 2026 sales of US$530.24m and earnings that remain positive even as net income and EPS have recently fallen. At the same time, heavy dependence on imported wire rod and exposure to Section 232 tariffs mean input costs, lead times and margins can move quickly, especially if enforcement tightens or domestic supply remains constrained. In addition, index deletions may have reduced visibility, and the combination of a P/E below the US building industry and an active buyback program suggests there is more going on beneath the surface than headline earnings alone indicate.

Insteel Industries looks like a story where falling EPS, a lower P/E than US building peers and an active buyback may be masking something investors have not fully pieced together yet, and the analysis report for Insteel Industries hints at what could be missing.

NYSE:IIIN P/E Ratio as at Jul 2026NYSE:IIIN P/E Ratio as at Jul 2026

EnerSys (ENS)

Overview: EnerSys supplies stored energy systems for industrial customers, powering telecom networks, data centers, electric forklifts, trucks and defense equipment through lead acid and lithium based batteries, chargers and related services sold worldwide.

Operations: EnerSys generates about US$1.7b from Energy Systems, US$1.4b from Motive Power and US$665.1m from Specialty products, with total revenue of roughly US$3.8b and most sales tied to these core operating segments.

Market Cap: US$7.29b

EnerSys gives you exposure to several themes in one stock, including AI driven data center demand, electrification of forklifts and trucks, and increased focus on secure US based energy supply for defense, supported by a broad product mix and a refined lithium strategy. New US tariffs could pressure customer sentiment in the short term. However, EnerSys has already built a tariff task force, produces largely in region, and has levers in pricing, sourcing and cost cuts, including a planned US$80m of annual savings. Earnings have recently fallen and the balance sheet leans on external borrowing. Some analysts expect faster earnings growth than the wider US market, which may make the combination of valuation, buybacks and tariff exposure worth a closer look.

EnerSys looks like an earnings story that may be decoupling from headline worries about tariffs and borrowing, and the analyst forecasts for EnerSys can help you see what expectations might be missing right now.

NYSE:ENS Earnings & Revenue Growth as at Jul 2026NYSE:ENS Earnings & Revenue Growth as at Jul 2026

The three stocks covered here are only a starting point, and the full US Domestic Manufacturing Stocks screener on Simply Wall St surfaces 42 more companies with equally compelling narratives that you have not seen yet through the US Domestic Manufacturing Stocks screener. Use the Simply Wall St platform to identify and analyze the specific catalysts, risk factors and business narratives that matter most to you so you can focus on the highest conviction US manufacturing opportunities.

Take Control of Your Investment Journey

If Insteel Industries or any of these companies sound like a great opportunity, register for FREE with Simply Wall St and add your companies to a Watchlist to monitor the share price against the fair value the ideal entry point.
Once you’ve made your move, manage your holdings with our Portfolio Command Center that filters out the noise to deliver only the most critical, actionable updates.
Throughout your journey, our Community allows you to filter the best ideas from thousands of investor perspectives.
By uncovering hidden catalysts and risks early, you’ll accelerate your decision-making and stay one step ahead of the market.

Seeking Alternatives Before Everyone Else?

Fresh ideas move first, and the best entry points often pass quickly as momentum builds, prices start flying, or interest drops off. Scan under the radar for now and consider acting before conditions change.

  • Spot potential turnarounds early by tracking companies in the 49 high quality undervalued stocks while sentiment is still catching up and pricing in the next phase, and aim to position before the shift is widely recognized.
  • Monitor structural demand shifts by scanning the 35 power grid technology and infrastructure stocks as grids modernize and capital moves toward upgraded infrastructure, before those developments become more broadly reflected in prices.
  • Target stronger balance sheets by filtering the list of solid balance sheet and fundamentals (49 results) so you focus on businesses with more flexibility if conditions change and others are caught off guard, and consider positioning ahead of those adjustments.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: AI Stock Screener & Alerts

Our new AI Stock Screener scans the market every day to uncover opportunities.

• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies

Or build your own from over 50 metrics.

Explore Now for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

3 US Manufacturing Stocks Worth Watching As Brazil Tariffs Shift Demand


Tariffs between the US and Brazil are back in the headlines, and that kind of trade tension can quietly reshuffle the deck for large industrial and manufacturing stocks. Some companies face new questions around costs and supply chains, while others may find breathing room if Brazilian competitors become less price competitive. This article looks at three US industrial stocks from a health focused screener that appear closely exposed to the latest tariff news. You will see how each stock could be positioned to benefit, what risks to keep in mind, and why this theme might matter for your watchlist.

Alamo Group (ALG)

Overview: Alamo Group manufactures equipment that keeps infrastructure and land in working order, from tractor powered mowers and forestry tools to street sweepers, sewer cleaners, snow plows, and waste handling trucks used by governments, contractors, and agricultural customers worldwide.

Operations: Alamo Group generates about US$964.3 million from Industrial Equipment and US$665.6 million from Vegetation Management, with most revenue coming from the United States alongside smaller contributions from Canada, France, the United Kingdom, and other markets.

Market Cap: US$2.0b

Alamo Group provides direct exposure to infrastructure and agriculture equipment at a time when tariffs on Brazilian products may make domestically produced machinery more competitive. The company already has substantial manufacturing in the US and Canada. Analysts highlight healthy earnings growth expectations, high quality earnings and a discount to estimated fair value. Management has recently reduced net debt to a modest level and secured a sizeable long term credit facility. However, recent earnings have declined, margins have come under pressure and the management team is relatively new. Execution and tariff related input cost pressures therefore remain important watchpoints for investors tracking this stock.

Alamo Group looks like an overlooked tariff beneficiary, with US based manufacturing, reduced net debt and fresh financing capacity that could matter far more than the headline margin pressure suggests, start with the DCF valuation analysis for Alamo Group

ALG Discounted Cash Flow as at Jul 2026ALG Discounted Cash Flow as at Jul 2026

Century Aluminum (CENX)

Overview: Century Aluminum produces primary aluminum and alumina, supplying both standard and value added products from smelters in the United States and Iceland. The company is supported by a carbon anode facility in the Netherlands and bauxite mining and alumina refining in Jamaica.

Operations: Century Aluminum generates about US$2.5b in revenue from Primary Aluminum, with around US$1.9b coming from the United States and US$660.4m from Iceland.

Market Cap: US$4.1b

Century Aluminum operates at the center of US aluminum supply at a time when new 25% tariffs on Brazilian products could redirect demand toward domestic producers and support local pricing. The company already emphasizes short, locally sourced supply chains, and management has indicated that recent reciprocal tariffs did not bring material cost pressure. Earnings momentum, high return on equity and meaningful exposure to US and EU markets contribute to its current positioning. Investors still need to weigh exposure to trade policy shifts, power and raw material costs, and the quality of recent non cash earnings. For readers tracking reshoring, clean energy build out and tariff supported metals, Century Aluminum presents multiple factors to consider.

Century Aluminum sits at the crossroads of tariffs, reshoring and clean energy, yet the real story lies in how its US and EU exposure, costs and earnings quality fit together in the analysis report for Century Aluminum

NasdaqGS:CENX Earnings & Revenue Growth as at Jul 2026NasdaqGS:CENX Earnings & Revenue Growth as at Jul 2026

Proto Labs (PRLB)

Overview: Proto Labs is a digital manufacturer that produces custom parts for developers, engineers, and supply chain teams, using services such as molding, CNC machining, 3D printing, and sheet metal fabrication across the United States and Europe.

Operations: Proto Labs generates about US$546.3 million in revenue from Machinery & Industrial Equipment, with roughly US$444.2 million from the United States and US$102.1 million from Europe.

Market Cap: US$1.8b

Proto Labs provides direct exposure to the shift toward faster, more localized manufacturing. This has become more relevant as 25% US tariffs on Brazilian products push companies to source critical components closer to home. The company focuses on high requirement work in aerospace, defense, medical devices, and drones, supported by a global, digital manufacturing footprint and AI driven pricing systems that can adjust to changing trade rules. At the same time, a high P/E, margin pressure from absorbing tariff related cost shocks, reliance on large customers, and an inexperienced management team are important considerations alongside earnings momentum and cash generation. How those trade offs resolve is a key factor for this stock in a tariff heavy environment.

Proto Labs’ push toward faster, localized manufacturing, AI driven pricing and cash generation sits against a high P/E and tariff related cost pressure. See how those trade offs stack up in the analysis report for Proto Labs.

NYSE:PRLB Earnings & Revenue Growth as at Jul 2026NYSE:PRLB Earnings & Revenue Growth as at Jul 2026

The three stocks covered here are only a starting point, since the full US Domestic Industrial and Manufacturing Stocks screen surfaces 46 more companies with equally compelling health scores, scale and tariff related angles that could reshape how you think about this theme, all organized in the US Domestic Industrial and Manufacturing Stocks screener. Use Simply Wall St to identify and analyze the specific catalysts, balance sheet strength and earnings narratives that matter most to you so you can focus on the highest conviction ideas in this group.

Take Control of Your Investment Journey

If Century Aluminum or any of these companies sound like a great opportunity, register for FREE with Simply Wall St and add your companies to a Watchlist to monitor the share price against the fair value the ideal entry point.
Once you’ve made your move, manage your holdings with our Portfolio Command Center that filters out the noise to deliver only the most critical, actionable updates.
Throughout your journey, our Community allows you to filter the best ideas from thousands of investor perspectives.
By uncovering hidden catalysts and risks early, you’ll accelerate your decision-making and stay one step ahead of the market.

Seeking Alternatives Before The Crowd?

Fresh stock ideas do not stay under the radar for long. As momentum builds and prices start flying, late entries can end up chasing. Review these curated lists and consider your options.

  • Spot companies quietly building strong cash flows before momentum develops by reviewing a curated mix of high quality value candidates in the 47 high quality undervalued stocks.
  • Explore infrastructure opportunities connected to AI-related demand by tracking hand picked enablers of data centers and networking in the 54 AI infrastructure stocks.
  • Monitor activity in robotics, automation and factory upgrades by studying carefully selected industrials inside the 33 robotics and automation stocks.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: AI Stock Screener & Alerts

Our new AI Stock Screener scans the market every day to uncover opportunities.

• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies

Or build your own from over 50 metrics.

Explore Now for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link