Industrial equipment leader for US manufacturing


SPX FLOW Inc provides pumps, valves and mixers essential for food, beverage and industrial processing, with strong exposure to US markets amid ongoing supply chain recovery.

SPX FLOW Inc, a key supplier of engineered equipment for food and beverage processing, recently reported steady demand in its core segments. The company, listed on the New York Stock Exchange under ticker FLOW, serves major US producers with solutions for mixing, blending and heat transfer. Its products support efficiency in manufacturing plants across North America.

The stock traded at approximately 50.25 USD on 05/13/2026 on NYSE, reflecting stability in the industrial sector, according to Yahoo Finance as of 05/13/2026. Investors track SPX FLOW for its role in resilient supply chains vital to US consumer goods production.

As of: 14.05.2026

By the editorial team – specialized in equity coverage.

At a glance

  • Name: SPX FLOW Inc
  • Sector/industry: Industrial Machinery & Equipment
  • Headquarters/country: United States
  • Core markets: North America, Europe
  • Key revenue drivers: Food & Beverage, Power & Energy
  • Home exchange/listing venue: NYSE (FLOW)
  • Trading currency: USD

SPX FLOW: core business model

SPX FLOW designs and manufactures process equipment for applications including homogenization, heat exchangers and dryers. Its portfolio targets the food and beverage industry, where precision mixing ensures product quality for dairy, beverages and bakery goods. The company also serves power generation and chemical processing with pumps and valves built for high-pressure operations.

Headquartered in Charlotte, North Carolina, SPX FLOW operates globally but derives a significant portion of revenue from US customers. For the fiscal year 2025, reported on 02/27/2026, net sales reached 1.45 billion USD, with Food & Beverage contributing 58%, according to SPX FLOW investor site as of 02/27/2026. This segment benefits from US food safety regulations driving equipment upgrades.

Main revenue and product drivers for SPX FLOW

The Food & Beverage division leads with products like APV pumps and mixing systems used by processors such as dairy giants and soft drink makers. In Q4 2025, this unit posted 8% organic growth, fueled by demand for sustainable processing tech amid US sustainability mandates. Industrial segment follows, providing solutions for oil & gas and chemicals.

Key drivers include aftermarket parts and services, which offer high-margin recurring revenue. For 2025 full year, adjusted EBITDA margins hit 17.2%, published with Q4 results on 02/27/2026 per company filings. US manufacturing resurgence supports orders as plants modernize post-pandemic.

Industry trends and competitive position

The industrial processing equipment market grows with US food production output, projected at 3-4% CAGR through 2028 per S&P Global as of 01/2026. SPX FLOW competes with Alfa Laval and GEA Group, differentiating via US-centric service networks that reduce downtime for domestic clients.

Sustainability trends favor its energy-efficient heat exchangers, aligning with EPA guidelines. The company’s 2025 sustainability report highlighted 15% reduction in product energy use, enhancing appeal to US firms facing carbon reporting rules.

Why SPX FLOW matters for US investors

SPX FLOW’s NYSE listing and US headquarters provide direct exposure to American industrial recovery. Over 50% of revenue ties to North America, linking performance to US GDP growth and manufacturing PMI. Its dividend yield around 1.2% as of Q1 2026 adds income stability for retail portfolios.

Conclusion

SPX FLOW maintains a solid position in industrial processing equipment, with Food & Beverage driving growth amid US market demands. Recent financials show margin expansion and stable orders, though sector cycles warrant monitoring. The company’s US focus offers retail investors a play on domestic manufacturing strength without overseas volatility.

Disclaimer: This article does not constitute investment advice. Stocks are volatile financial instruments.

Free Training

Source link

Tariffs drive companies to expand manufacturing in U.S., Gerdau says


Gustavo Werneck, chief executive of Gerdau, said the U.S. administration’s tariff policy may be viewed as an unexpected measure, but it also reflects a long-term vision and confidence in the revival of American industry.

According to Werneck, Gerdau does not base its investment decisions on short-term volatility and continues to invest because it believes in the long-term recovery of U.S. manufacturing.

“There has been an additional incentive for Brazilian companies to establish manufacturing operations here in the United States,” Werneck said during the third edition of the Summit Valor Brazil-USA on Wednesday in New York.

The executive, who took part in a panel on trade and investment relations between Brazil and the United States, said the cost of key industrial inputs such as energy and natural gas in the U.S. is unmatched, making it impossible to offset the price gap between the two countries solely through management efficiency.

“In Brazil, we pay around $16 per cubic meter of natural gas. Here, despite all the volatility, we are still paying around $4,” he said.

Gerdau operates 13 of its 29 steel production units in North America, with facilities spread across the United States and Canada.

According to Werneck, the reindustrialization of the U.S. is already visible through customers building new factories in the country.

“We are currently supplying a significant amount of steel to new semiconductor plants being established here,” he added.

Gustavo Werneck — Foto: Vanessa Carvalho/Valor Gustavo Werneck — Foto: Vanessa Carvalho/Valor

Free Training

Source link

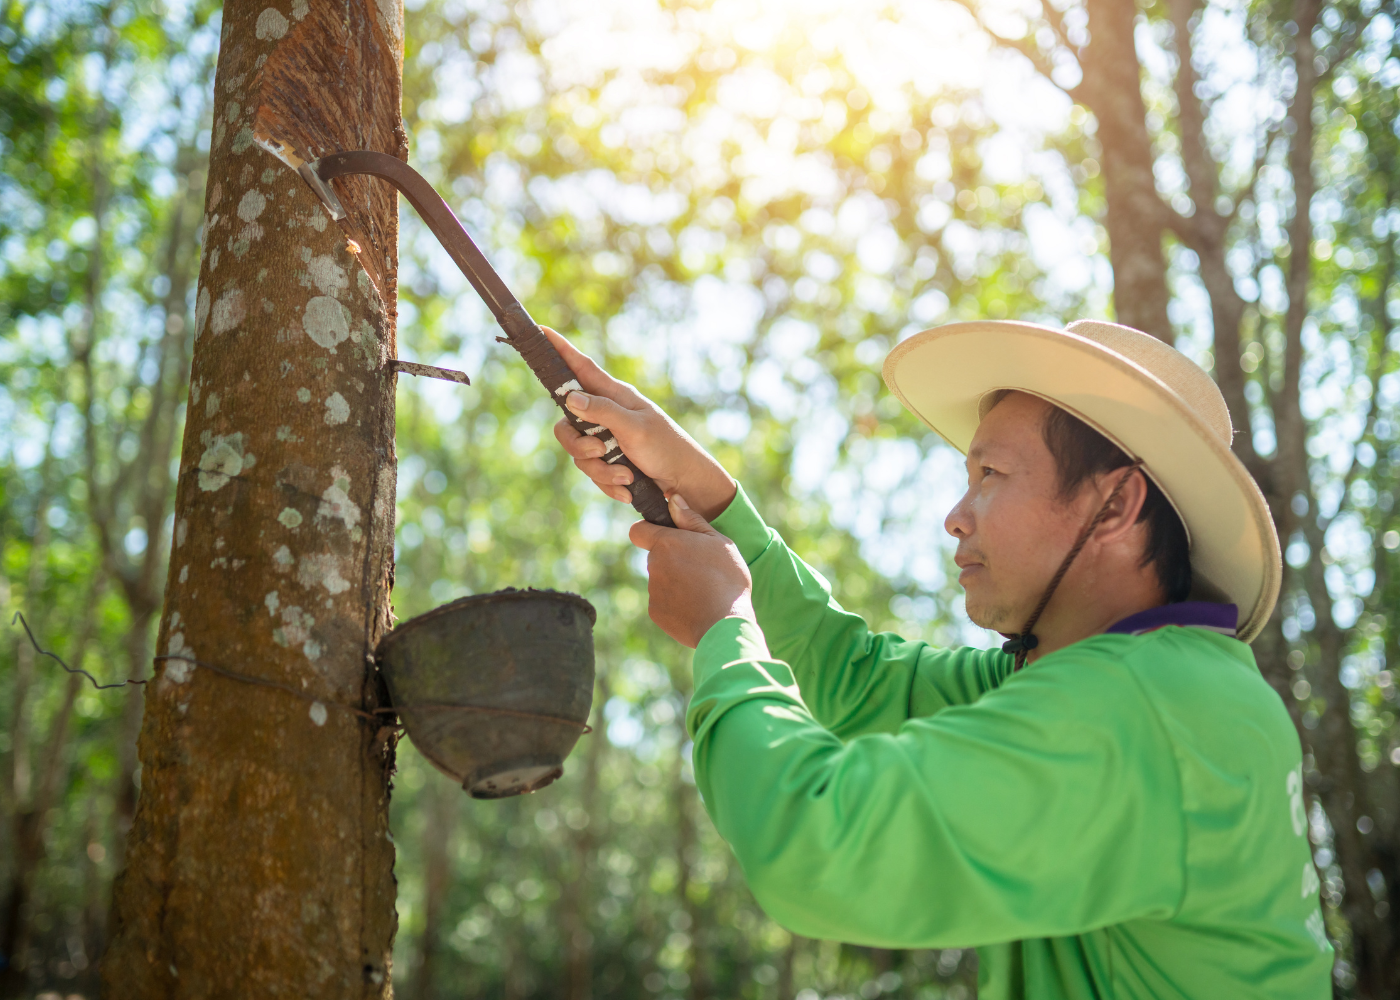
No commercial rubber trees grow in the United States


FACT:  No commercial rubber trees grow in the United States.

THE NUMBERS: Imports of goods by industry type (2024)* –

Industry type 
Import value
Share of Imports

All identifiable U.S. importers
$2.925 trillion
89%

… Manufacturers 
$1.220 trillion
37%

… Wholesalers 
$0.971 trillion
29%

… All known others 
$0.735 trillion
22%

All else, not identified by importer type
$0.370 trillion
11%

* Census Bureau.

WHAT THEY MEAN: 

As legal devices, the Trump administration’s tariff decrees are faring poorly. The Supreme Court killed most of Plan A — “emergency” declarations under the International Emergency Economic Powers Act — in February. The specialized Court of International Trade found Plan B, a Section 122 claim that the U.S. is in the midst of a “balance of payments crisis,” illegal last Thursday: 

“Because the Proclamation’s use of trade and current account deficits to stand in the place of balance-of-payment deficits within the meaning of the statute renders the Proclamation ultra vires … Proclamation No. 11012 is invalid, and the tariffs imposed on Plaintiffs are unauthorized by law.”
Plan C, announced in March and probably going live in July, disinters a third old trade law (“Section 301”), hoping to use it to impose tariffs on allegations of “structural excess capacity” and forced labor law. (PPI’s unimpressed comment here.) Court rulings on this one will presumable coming next year. In the interim, a reality check: if the administration’s decrees are struggling as a legal matter, are they nonetheless achieving their real-world economic goals? 

A year ago, the administration said that while tariff increases might cause pain, this would be transitory. Though prices might go up, and living standards for American waitresses, teachers, truck drivers, and auto mechanics might fall, new manufacturing output and jobs would compensate with better opportunities. A year later, this hasn’t happened: manufacturers have shed about 100,000 jobs, and their “GDP” share is down from 9.8% to 9.4%. Why not? A likely explanation is that the administration’s mental picture of both “trade” and “manufacturing” was naïve: manufacturers are far larger importers than it realized, and a lot of the tariff burden has fallen on them. Two examples, then the big-picture point:

  1. Metal tariffs and container chassis-making: Sitting next to PPI’s Ed Gresser at the U.S. Trade Representative Office’s “public hearing” on Plan C last Friday, a lawyer for U.S.-based makers of container chassis for trucks argued that foreign chassis-makers are getting various tax breaks and other supports from their governments, and unfairly competing to sell the low-priced result to American trucking companies, so tariffs on Chinese-made chassis have simply shifted production to other countries.

Whether or not foreign chassis have gotten too cheap, the administration’s tariff decrees are definitely making the U.S.-made version more expensive. Last June’s “Section 232” tariff decree — not legally challenged so far, and thus fully in force — imposed a 50% tariff on steel on “national security” grounds. According to the Commerce Department, American buyers of steel now pay an average of $971 per ton for their metal, more than twice the $460 average their overseas competitors pay. A 40-foot container chassis costing about $25,000 requires about three tons of steel, and this price gap means the U.S. version now starts out $1,500 in the hole against foreign rivals — even before the potential Plan C tariffs on screws, coatings, rivets, lathes, sandblasters, gantry welders, laser cutters, positioning tables, etc., and all the inputs and capital equipment needed to make things out of metal.

  1. Natural rubber tariffs and airplane tire-making: The March “Federal Register Notice” announcing Plan C cites a “trade surplus in rubber” as grounds for putting Thailand on its 16-country investigation list. Thailand does indeed have such a surplus, but this is natural — in economic terms, a consequence of Southeast Asia’s “absolute advantage” in rubber trees — and a Plan C tariff on Thai rubber would help nobody and harm lots of American manufacturers.

To explain, the U.S. uses about 3 million tons of rubber a year. This includes 1 million tons of natural rubber produced by rubber-tree tapping, and 2 million tons of artificial rubber produced in factories. They aren’t substitutes for one another: artificial rubber is less chemically active and therefore preferred for gaskets, fan belts, tubes, and the soles of shoes; natural rubber, being stretchier and more friction-resistant, is the main material for airplane and truck tires, as well as for condoms, surgical gloves, construction joints, and medical devices.  

All natural rubber comes from abroad — mainly Southeast Asia, secondarily West Africa — because the rubber tree, Hevea brasiliensis, is a tropical plant which thrives in hot, rainy climates. (Curious D.C. Metro residents can see one in the U.S. Botanical Gardens’ climate-controlled Tropics Room near the Capitol.) Since rubber trees don’t grow in places with cold winters, the U.S. produces no natural rubber at all. Tariffs on natural rubber, no matter how high, won’t bring rubber-tree plantation jobs to Minnesota or North Carolina, but will raise costs and reduce sales for every U.S. manufacturer of airplane and truck tires, vibration dampers in bridges, specialized medical equipment, and so on.

These specific cases illustrate a systematic administration error: a belief that “trade” operates on something like 19th-century terms, with manufacturers buying raw materials, farmers and miners exporting bulk commodities, and countries competing to export finished manufactured goods. This wasn’t exactly true then, and hasn’t been close to reality since the 1950s. Just-in-time delivery, supply chains, and coordinated production mean the largest amount of trade is in “intermediate” goods — neither raw materials nor finished stuff, but parts and components used to assemble more complex things. The largest U.S. importers are accordingly not “buyers of finished goods” such as retail chains, hospitals, construction firms, restaurants, and so forth. Instead, they are the chassis-makers buying metals, the airplane-tire-makers buying natural rubber, and other manufacturers buying energy, paint, screws, semiconductor chips, etc., so as to turn these “inputs” into final products or “semi-finished goods” they then sell to others. So though tariffs on steel may benefit steel companies, those benefits only come at the expense of chassis-makers and other metal-users; and tariffs natural rubber are pure losses for U.S. manufacturing.

Statistically, the Census’s annual “Profile of Importing and Exporting Companies” release last Tuesday credits manufacturers with $1.2 trillion in imports — over 40% of the total import value they could identify by industry. That suggests last year’s tariff decrees likely hit U.S. manufacturers with $150 billion or so in new costs. So as the tariffs raised prices for the waitresses, teachers, truck operators, and repair-shop mechanics, they also made it more expensive to operate factories in the United States. Thus no industrial boom has materialized.

In sum: So far, legal judgments on the administration’s tariff decrees haven’t been positive. Real-world economic impacts, likewise.

FURTHER READING

PPI’s four principles for response to tariffs and economic isolationism:

  • Defend the Constitution and oppose rule by decree;
  • Connect tariff policy to growth, work, prices and family budgets, and living standards;
  • Stand by America’s neighbors and allies;
  • Offer a positive alternative.

Data:

Census counts U.S. importers and exporters by industry type, company size, etc., as of 2024 (see Table 1d for the importers), and finds that manufacturers are the largest importers.

Legal update:

Plan A: The April 2nd, 2025, “international emergency” decree. Now defunct.

… the Supreme Court’s February 20 ruling striking it down.

Plan A(ii): The June 3, 2025, steel “national security” decree is an exception since it hasn’t so far faced legal challenge and is still in effect.

Plan B: The February 26, 2026, “balance of payments crisis” decree, ruled illegal last week with appeal pending.

… the Court of International Trade’s ruling striking it down last Thursday.

Plan C: The U.S. Trade Representative Office’s “Structural Excess Capacity” investigation, with a gloomy assessment of how “reindustrialization” is going, and a memorably loopy explanation of “Structural Excess Capacity”:

“The Trump Administration’s reindustrialization efforts continue to face significant challenges due to foreign economies’ structural excess capacity and production in manufacturing sectors. Across numerous sectors, many U.S. trading partners are producing more goods than they can consume domestically. This overproduction displaces existing U.S. domestic production or prevents investment and expansion in U.S. manufacturing production that otherwise would have been brought online. In many sectors, the United States has lost substantial domestic production capacity or has fallen worryingly behind foreign competitors.”

PPI’s Gresser testified on the “Plan C” 301 investigation last week. (Quick summary: inconsistent with the statute and a breach of the separation of powers; economically irrational; data unpersuasive and at times irrelevant.)

… and in Monday’s Wall Street Journal (subs. req.)

ABOUT ED

Ed Gresser is Vice President and Director for Trade and Global Markets at PPI.

Ed returns to PPI after working for the think tank from 2001-2011. He most recently served as the Assistant U.S. Trade Representative for Trade Policy and Economics at the Office of the United States Trade Representative (USTR). In this position, he led USTR’s economic research unit from 2015-2021, and chaired the 21-agency Trade Policy Staff Committee.

Ed began his career on Capitol Hill before serving USTR as Policy Advisor to USTR Charlene Barshefsky from 1998 to 2001. He then led PPI’s Trade and Global Markets Project from 2001 to 2011. After PPI, he co-founded and directed the independent think tank ProgressiveEconomy until rejoining USTR in 2015. In 2013, the Washington International Trade Association presented him with its Lighthouse Award, awarded annually to an individual or group for significant contributions to trade policy.

Ed is the author of Freedom from Want: American Liberalism and the Global Economy (2007). He has published in a variety of journals and newspapers, and his research has been cited by leading academics and international organizations including the WTO, World Bank, and International Monetary Fund. He is a graduate of Stanford University and holds a Master’s Degree in International Affairs from Columbia Universities and a certificate from the Averell Harriman Institute for Advanced Study of the Soviet Union.

Read the full email and sign up for the Trade Fact of the Week.

Free Training

Source link

FH Capital to Acquire 75.1 Percent Stake in JinkoSolar US Manufacturing Unit, Expand Solar and BESS Platform – Asia Pacific


FH Capital will acquire 75.1 percent of JinkoSolar’s US manufacturing subsidiary, expand 2 GW solar module capacity, and launch domestic BESS production to strengthen America’s clean energy manufacturing and supply chain.

May 13, 2026. By EI News Network

FH Capital has entered into an agreement to acquire a 75.1 percent majority stake in JinkoSolar’s US manufacturing subsidiary, creating a domestic solar and Battery Energy Storage Systems (BESS) platform anchored by a 2 GW solar module manufacturing facility in the United States. JinkoSolar will retain a 24.9 percent minority stake in the venture.

Following the transaction, FH Capital plans to inject additional expansion capital to at least double the facility’s current solar module production capacity while also launching domestic BESS manufacturing operations. The move is aimed at strengthening US-based clean energy manufacturing amid rising demand for locally sourced solar and storage products and evolving US energy policies.

FH Capital is led by Sanjeev Chaurasia, a renewable energy investment banker with more than two decades of experience. Chaurasia previously served as Managing Director at Credit Suisse, where he co-founded the firm’s renewable energy practice and led JinkoSolar’s 2010 NYSE IPO.

According to Chaurasia, the transaction combines JinkoSolar’s established US manufacturing presence, technology portfolio, and customer network with FH Capital’s investment and operational capabilities to support growing domestic solar and storage demand.

Nigel Cockroft, US General Manager of JinkoSolar, said that the partnership provides strategic direction and ownership support to expand manufacturing capacity and serve increasing demand for US-sourced renewable energy products.

The transaction remains subject to customary regulatory approvals and closing conditions. Financial details of the deal were not disclosed.

Free Training

Source link

Switzerland-Based Novartis Breaks Ground on Radioligand Therapy Site in Denton » Dallas Innovates


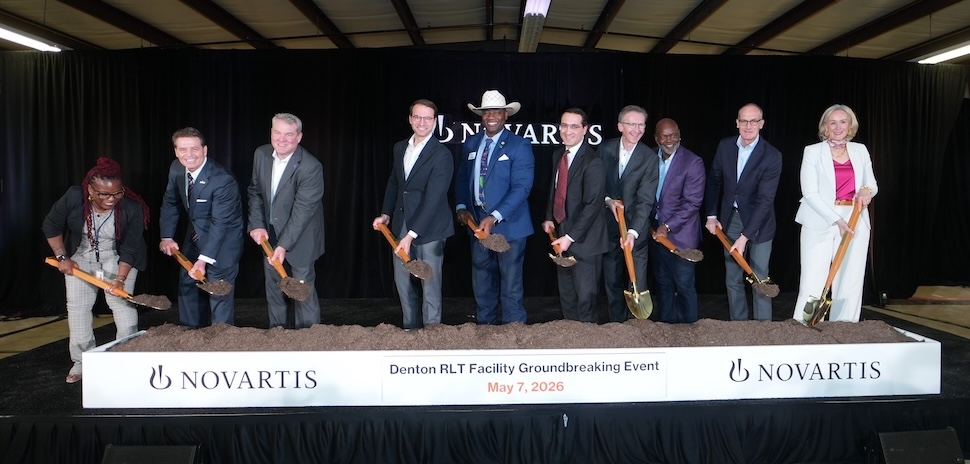
Swiss global pharmaceutical giant Novartis recently broke ground on its new radioligand therapy (RLT) manufacturing site in Denton, part of its broader $23 billion investment in U.S. manufacturing and research.

When completed in 2028, the company’s first Texas‑based manufacturing facility will bring RLT medications closer to patients across the southern United States, becoming the fifth RLT site nationwide, Novartis said.

Novartis CEO Vas Narasimhan said radioligand therapy “is transforming how we treat cancer, and expanded manufacturing is essential to delivering these therapies at scale.”

“Breaking ground in Denton further strengthens our U.S. supply chain and helps ensure patients can receive these highly personalized treatments when and where they need them,” Narasimhan added in a statement.

The 46,000-square foot facility aims to boost Novartis’ position as the first company to deliver RLT at scale, creating the network capacity needed as these therapies extend into earlier stages of treatment and a broader range of cancers. Announced earlier this year, the Denton facility is expected to create new U.S.-based Novartis jobs in bioengineering, advanced manufacturing, quality, and operations, supporting economic growth in Denton and surrounding communities, the company said. 

Swiss ambassador, U.S. Department of Commerce official took part in groundbreaking 

Taking part in the groundbreaking in Denton were U.S. Under Secretary of Commerce for Industry and Security Jeffrey Kessler; Swiss Ambassador to the U.S. Ralf Heckner; Texas State Senator Brent Hagenbuch; Texas State Representative Andy Hopper; and Denton Mayor Gerard Hudspeth. They joined Novartis leadership, employees, and community partners to celebrate the start of construction.

“I’m pleased to welcome Novartis to Denton as their newest manufacturing location for their cancer therapies,” Texas State Senator Brent Hagenbuch said in a statement. “Their decision establishes a strong partnership and reflects the unique opportunity Denton provides to a well-educated workforce, and the unique access the new plant location will provide to the vibrant North Texas economy and rapidly growing state population.”

Producing medications for U.S. patients in the U.S.

The Texas facility strengthens the Novartis coast-to-coast RLT manufacturing network, with existing US sites in New Jersey, Indiana and California, and another new site being added in Florida. Together, the facilities make up the largest U.S. RLT manufacturing network, further bolstering the company’s longstanding track record of enabling over 99% of doses to be administered on the planned day of treatment.

Each dose of RLT is custom-made and requires precise coordination, the company said, making manufacturing reliability and proximity to treatment centers key factors in providing timely treatment.

At the groundbreaking, Kessler said the Trump Administration “is delivering historic wins for the American people—lowering drug prices, revitalizing manufacturing, creating jobs, and attracting massive new investments. Novartis’s groundbreaking today is the latest example of the Administration’s successful policies at work.

In April 2025, Novartis said it was designating $23 billion over five years to grow its U.S. research and manufacturing footprint. Seven new and three expanded facilities across the country are already under construction—part of the company’s goal of manufacturing all key medicines for U.S. patients in the U.S, supporting supply resilience and dependable delivery of medicines.

Don’t miss what’s next. Subscribe to Dallas Innovates.

Track Dallas-Fort Worth’s business and innovation landscape with our curated news in your inbox Tuesday-Thursday.


Free Training

Source link

FH Capital acquires majority stake in JinkoSolar US


New York-based FH Capital has entered a definitive agreement to acquire a 75.1% stake in JinkoSolar’s US subsidiary, Jinko Solar (US) Industries Inc. China-based JinkoSolar will retain a 24.9% minority interest following transaction completion. The deal includes control of a 2 GW solar module manufacturing facility and an expanding Battery Energy Storage Systems business in the United States. FH Capital stated that additional investment will support plans to at least double existing solar module production capacity and begin domestic BESS manufacturing operations. JinkoSolar said the transaction builds on its seven-year U.S. manufacturing presence and established relationships with large domestic customers. The transaction remains subject to customary regulatory approvals and closing conditions, while financial terms were not disclosed.

Free Training

Source link

The State of Clean Energy Manufacturing in Q1 2026: Environmental Defense Fund Report | Mitchell, Williams, Selig, Gates & Woodyard, P.L.L.C.


Introduction –

2025 represented a turning point in clean energy manufacturing in the United States. From 2021 to 2024, the country experienced an unprecedented clean energy manufacturing boom supported by federal policies that accelerated private investment. In 2025, growth in clean energy manufacturing largely declined in the wake of the Trump administration’s policies and congressional cuts to clean energy tax credits.

Please see full publication below for more information.

Free Training

Source link

Understanding the global clean tech manufacturing slowdown


Investment in clean technology manufacturing facilities is falling worldwide. After peaking at $70 billion in 2023, quarterly manufacturing investment more than halved to $35 billion by end-2025. This is despite global demand for clean technologies growing rapidly. Since 2020, solar installations have more than tripled in China (+250 percent), while more than doubling in the United States and European Union (+132 percent and +125 percent, respectively). Also since 2020, electric vehicle (EV) sales in China have grown nearly tenfold, in the US fourfold and in the EU threefold. These three economies host 86 percent of total clean-technology manufacturing investment since 2018.

In the context of growing demand, why is global clean-tech manufacturing investment slowing? We examine the three largest clean-tech sectors: solar, batteries and EVs. The headline fall largely reflects an oversupplied market, especially falling Chinese investment in solar photovoltaic manufacturing (Figure 1) – in this respect the decline is not a cause for concern. However, the drop in battery manufacturing investment that has followed abrupt US policy changes is worrying. Amid the slowdown, European investment remains largely stable.

Overcapacity and policy reversals

Most of the global clean-tech investment drop relates to China, where investment in 2025 was down nearly 70 percent from a peak in 2023 (Figure 2). This followed years of state-led investment that secured dominance for China in solar, battery and EV supply chains and allowed Chinese firms to produce at prices no competitor could match. But the strategy also drove overcapacity and domestic price wars. To rein in overcapacity, the Chinese government has adjusted policy since 2024 (Davidson and Qian, 2026).

Meanwhile, access to foreign markets for Chinese goods has tightened, with steep US tariffs on Chinese clean technology and European tariffs on EVs. This has led some Chinese companies to shift investment overseas.

Declining clean-tech investment in the US is driven by policy, especially the dismantling under President Donald Trump of the 2022 Inflation Reduction Act (IRA), which provided clean-tech subsidies. Since mid-2025, some subsidies have been cut and certain tax credits phased out. Many clean-tech manufacturing projects have since been cancelled, with €7 billion worth of project cancellations in the first quarter of 2025 and another €5 billion in the second quarter (Rhodium Group, 2025).

European manufacturing investment has remained stable, though EV investment has slowed because of weaker than expected demand growth, partly driven by a European Commission proposal to reduce to 90 percent a goal for zero-emission passenger vehicles to comprise 100 percent of new sales in 2035 (European Commission, 2025). Unlike the US however, the EU remains broadly committed to its climate targets, which favours clean-tech investment. The EU Net-Zero Industry Act (Regulation (EU) 2024/1735) sets a target for the bloc to meet 40 percent of its clean-tech demand from domestic manufacturing by 2030. European governments have provided subsidies to support manufacturing projects for selected clean technologies, especially batteries and EVs. The rollback of US climate policy and imposition of tariffs is reducing an important export market for EU manufacturers. Monthly net EU EV exports to the US have fallen from €1.5 billion to €300 million since the beginning of 2025.

Supply-demand imbalances contribute to slowing solar investment

More than 90 percent of the world’s solar PV manufacturing capacity is in China, with just one percent in the EU and two percent in the US (Rhodium Group, 2025). The Chinese government identified solar energy as a strategic sector in the early 2000s, and a combination of land subsidies, cheap loans and low-cost financing backed an enormous manufacturing push. Five-Year Plans set binding targets for installation, creating certainty on the demand side (IEA, 2022). As factories expanded, solar panel costs fell and Chinese companies became the default suppliers for buyers worldwide.

Intense Chinese competition saw solar module prices fall by about two thirds between 2022 and 2024. Subsequently, changes were made to Chinese state support to reign in price wars and rationalise the industry (Davidson and Qian, 2026). Since 2024, firms must fund at least 30 percent of project costs through equity rather than debt and new efficiency standards have been introduced. New power-market reforms now expose solar to market-based pricing. Consequently, Chinese solar manufacturing investment fell from €83 billion in 2023 to €15 billion in 2025, the single largest driver of the global clean-tech investment slowdown.  

This however will not fundamentally change China’s dominance of global solar PV manufacturing. Current Chinese solar cell manufacturing capacity of 1,200 GW already meets annual domestic solar demand four times over and global demand more than twice over. Already underway investment is on track to add an additional one third to Chinese capacity in the next few years (Figure 3). 

Solar manufacturing investments in the US and EU are not comparable to China. The IRA encouraged through tax credits US solar manufacturing investment, leading to a rapid expansion of domestic capacity. However, the Trump administration has shortened eligibility windows for credits and tightened sourcing restrictions, slowing new developments. This has reduced the business case for new projects, and announced US solar manufacturing investment fell to $3.25 billion in 2025, down from a peak of $11.25 billion in 2023. 

Europe’s manufacturing capacity remains limited. Enel’s 3SUN gigafactory is the largest operational plant in Europe with a 3 GW capacity, equivalent to approximately 5 percent of annual European solar PV demand. A handful of projects concentrated in Spain, France and the Netherlands are at a very early stage and considering final investment decisions. 

From 2026, under the Net-Zero Industry Act, European governments must introduce requirements for public authorities to favour bids that diversify away from dominant third-country suppliers, in sectors in which the EU is particularly dependent on a single country. This is the case for EU imports of Chinese solar PV, and the change will marginally reduce the attractiveness of Chinese imports. However, the economic rationale for replacing Chinese solar panel supply with domestic production is weak (McWilliams et al, 2024). Governments remain reluctant to offer the necessarily substantial fiscal support to domestic solar manufacturers.

Europe is adopting a more targeted approach aimed at reducing dependence on Chinese supply for solar components that are considered security relevant. In May 2026, the EU barred the use of Chinese inverters, which convert solar energy into a form suitable for the power grid, for European publicly funded solar projects. The European Commission considers the inverter to represent a cybersecurity risk because of the possibility of remotely operated shutdowns.

Sharp contraction in battery manufacturing investment is a concern for the US

Similarly to solar PV, China remains the dominant global battery and EV market and manufacturing hub, but is entering a managed slowdown phase after years of state-led expansion. A comprehensive policy framework, including purchase subsidies since 2013, the Dual-Credit Policy (ICCT, 2017) and sustained industrial planning, have framed the rapid development of a fully integrated supply chain. The Dual Credit Policy sets rising annual EV credit quotas that carmakers can trade, with foreign battery-makers excluded from subsidies during this crucial phase.

Since 2023, Chinese battery and EV investment has declined as margins have fallen and authorities respond to overcapacity and falling profitability. Policy adjustments in 2024-2025, including tighter battery regulations and revised credit rules, aim to curb price wars and rationalise the industry, shifting towards higher-quality growth.

Some of the slowdown has been offset by growth in the stationary storage market. In 2025, two-thirds of the announced battery investments in China were earmarked for stationary storage, compared to about 15 percent in 2021. 

In the US, the IRA shaped battery and EV investments. In 2022, the IRA introduced a $7,500 consumer EV tax credit, alongside manufacturing subsidies and loans. This support triggered a rapid expansion in battery production and vehicle assembly. Battery manufacturing accounted for three-quarters of the growth in US clean-tech investment between 2021 and the 2024 peak, with investment rising more than fivefold over that period.

However, unlike in China – where the investment slowdown comes after global leadership has been secured – US industrial policy support ended before domestic manufacturing had scaled sufficiently or a robust home market took hold. Changes introduced by the US Congress preserve manufacturing credits in principle but introduce ‘foreign entity of concern’ restrictions that require 60 percent of qualifying battery inputs to come from non-Chinese sources by 2026, rising to 85 percent by 2030 (Elizalde et al, 2025). For most US battery manufacturers, whose supply chains run through China, compliance means costly restructuring or losing the credits entirely. The IRA manufacturing loan programme has been eliminated, while new tariffs have increased import prices.

US EV demand has also fallen sharply, with the expiry of the $7,500 vehicle tax credit in September 2025. Consumer spending on EVs fell 43 percent in the last quarter of 2025 after the previous quarter’s record high, and was down 31 percent on the last quarter of 2024. The EV demand outlook has also weakened following federal rollbacks of vehicle emission standards and fuel economy penalties. The abrupt policy shifts on both the supply and demand side of the EV supply chain have dampened battery manufacturing investment, with $11 billion of investment cancelled in 2025, more than ten times the 2024 level (Figure 4). In two quarters of 2025, cancellations exceeded new announcements. A further $51 billion of investment for US battery projects is still in the planning or construction stages and vulnerable to cancellations or delays.

European EV investment steady for now

In the EU, battery investment remained relatively high throughout 2025, between $1.7 billion and $2.4 billion per quarter, and continues to grow. EV manufacturing investment in the EU has slowed slightly. South Korean companies own most of the operational battery cell capacity in Europe, while Chinese companies are responsible for close to half of ongoing investments. European governments have provided upfront subsidies to these investments and to notable investments by domestic manufacturers, such as Verkor in France.

For the EU, EV and battery demand is guided by a regulation to phase out the sale of new passenger vehicles with exhaust emissions by 2035 (Regulation (EU) 2023/851). Alongside government purchase support, this regulation supports manufacturing investments. The steady tightening of the regulation since 2019 has been mirrored by a steady growth in manufacturing investment. In 2025, a proposal by the European Commission to weaken the 2035 target (European Commission, 2025) partly disrupted what was a stable policy framework. However, the proposed weakening is relatively minor in reducing the 2035 target for zero emission vehicles from 100 percent to 90 per cent (see above). European demand for EVs continues to grow, especially in the context of high petrol and diesel prices since the US-Israel war against Iran and the closure of the Strait of Hormuz. 

EV production capacity in the EU is already substantial at 4.8 million vehicles annually, compared to a demand close to 2.5 million (Figure 3). The EU has introduced tariffs on the import of Chinese electric vehicles, but these are far lower than those imposed by the US. In 2024, the US was the destination for €10 billion (one quarter) of EU EV exports; the imposition since then of vehicle tariffs by the US has hurt.

References

Bruegel Dataset (2025) ‘European Clean Tech Tracker’, version of 10 January 2026, available at https://doi.org/10.64153/HYOM7675

Davidson, M. and S. Qian (2026) ‘China’s Solar Industry Is in Upheaval—The Effects Will Be Global’, CSIS Briefs, Center for Strategic & International Studies, available at https://www.csis.org/analysis/chinas-solar-industry-upheaval-effects-will-be-global

Dornoff, J., C. Baldino, S. Díaz de Aguilar, E. Mulholland, M. Negri and M. Vega Gonzalo (2025) ‘Unwrapping the package: A review of the European Commission’s CO2 standards proposal’, Policy Brief, International Council on Clean Transportation, available at https://theicct.org/wp-content/uploads/2025/12/ID-537-%E2%80%93-EU-CO2-proposal_policy-brief_final.pdf

Elizalde, D., Z, Urecki and X, Fishman (2025) ‘Unpacking the FEOC Provisions in the House Ways and Means Reconciliation Bill’, Issue Brief, Bipartisan Policy Center, available at https://bipartisanpolicy.org/issue-brief/2025-reconciliation-feoc-provisions-house-ways-and-means-bill/

European Commission (2025) ‘Proposal for a Regulation of the European Parliament and of the Council amending Regulation (EU) 2019/631 as regards CO2 emission performance standards for new passenger cars and new light commercial vehicles’, COM(2025) 995 final, available at https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=celex:52025PC0995

ICCT (2017) ‘China’s New Energy Vehicle Mandate Policy (Final Rule)’, Policy Update, International Council on Clean Transportation, available at https://theicct.org/wp-content/uploads/2021/06/China_NEV_mandate_PolicyUpdate-_20180525.pdf

IEA (2022) Solar PV Global Supply Chains, International Energy Agency, available at https://www.iea.org/reports/solar-pv-global-supply-chains

McWilliams, B., S. Tagliapietra and C. Trasi (2024) ‘Smarter European Union industrial policy for solar panels’, Policy Brief 02/2024, Bruegel, available at https://www.bruegel.org/system/files/2024-02/PB%2002%202024_3.pdf

Rhodium Group (2025) ‘Clean Investment Monitor: US Q2 2025 Update’, 28 August, available at https://www.cleaninvestmentmonitor.org/reports/q2-2025-update

Free Training

Source link

U.S. Battery Manufacturing Construction Hits $45 Billion Amid Energy Storage Shift


U.S. Battery Manufacturing Construction Reaches $45B as Automakers Shift Toward Energy Storage

Battery manufacturing construction activity across the United States has reached unprecedented levels, with approximately $45 billion worth of projects currently under construction as automakers and energy companies pivot toward energy-storage technology.

Courtesy: photo by Julia on Pexels

According to new data released by Industrial Info Resources (IIR), the U.S. has roughly $63 billion in active and planned battery-manufacturing projects underway, with the majority of spending tied to facilities already being built.

The construction boom reflects a significant shift in strategy among automotive manufacturers and battery suppliers as demand growth for fully electric vehicles slows and companies increasingly focus on battery energy storage systems, or BESS.

“Rollbacks on energy transition funding — including the expiration of the federal $7,500 consumer EV tax credit — and slower-than-expected market adoption — are leading domestic automakers to shift production from full EVs, leaving some U.S. battery-manufacturing capacity underutilized,” the report stated.

Industry analysts say the transition is also being fueled by growing electricity demand from data centers and renewable energy infrastructure.

Automakers Reconfigure Facilities for Energy Storage Production

Major automakers including Ford and General Motors are investing billions to convert or expand facilities capable of producing lithium-iron-phosphate batteries for energy-storage applications.

Ford recently launched its new Ford Energy division and is investing approximately $2 billion to convert a former EV battery plant in Glendale, Kentucky, into a commercial BESS manufacturing facility. The plant is expected to produce at least 20 gigawatt-hours annually and begin operations in 2027.

Another Ford battery project under construction in Marshall, Michigan, is expected to begin production later this year and will focus on smaller residential battery units.

General Motors and Samsung SDI are also constructing a $3.5 billion battery facility in Indiana designed to support both EV and energy-storage battery production. Construction is expected to conclude by the end of 2027.

Meanwhile, GM’s Ultium Cells joint venture with LG Energy Solution is retooling its Spring Hill, Tennessee, facility to shift manufacturing toward lithium-iron-phosphate battery cells for energy storage.

Battery-storage technology is becoming increasingly important for utilities and data centers seeking alternatives to diesel-powered backup systems during grid disruptions.

Suppliers Expand U.S. Battery Investments

Battery manufacturers and suppliers are continuing to invest heavily in U.S. production capacity tied to Tesla and hybrid vehicle demand.

LG Energy Solution recently signed a deal to provide Tesla with $4.3 billion worth of lithium-iron-phosphate battery cells from its Lansing, Michigan, facility for use in energy-storage systems. The agreement is driving plans for a multibillion-dollar retooling and expansion of the plant.

Panasonic is also moving forward with a $4 billion expansion of its De Soto, Kansas, facility near Kansas City to increase production of battery cells for Tesla electric vehicles. Full-scale production is expected to begin in 2027.

Toyota is simultaneously expanding battery production at its Liberty, North Carolina, campus, the company’s only battery plant outside Japan. The project includes a new building with two production lines and eight additional lines dedicated to plug-in hybrid vehicles.

Industrial Info Resources said the rapid expansion of battery manufacturing construction demonstrates how energy storage is becoming a critical component of the nation’s evolving power infrastructure and industrial economy.

The report also highlights how data center growth and grid reliability concerns are reshaping investment priorities across the automotive and manufacturing sectors.

Originally reported by Danny Levin, Deputy Editor for IIR News Intelligence (Sugar Land, Texas) in Industrial Info. Com.

Free Training

Source link

Trump’s crackdown on China-linked solar firms stalls U.S. factory boom


Top solar companies, banks and insurers have stopped doing business with at least a half dozen recently built U.S. panel factories because of ⁠uncertainty over whether their ties to China could disqualify them from clean-energy subsidies, according to industry executives and documents.

The shift, driven by new policies of U.S. President Donald Trump’s administration, jeopardizes more than a third of U.S. solar capacity in factories initially built by Chinese firms. Details of how the policy uncertainty is driving installers and insurers away from U.S. solar factories with China ties have not been previously reported.

The emerging effects dovetail with Trump’s broader efforts to block Chinese companies from the U.S. market and to slash government support for green energy. However, the policy could backfire by imperiling growth in U.S. manufacturing jobs and power generation at a time of rising utility bills and soaring electricity demand from data centers serving the artificial intelligence industry, industry experts say.

Free Training

Source link