Abingdon Health opens US manufacturing hub in Madison


Abingdon Health has expanded its operations with a facility in Madison, Wisconsin, to meet growing demand for rapid diagnostic testing solutions.

The company is a developer and manufacturer of rapid diagnostic tests and med-tech solutions.

Chris Yates, president of Abingdon Health USA and chief commercial officer of Abingdon Health plc, said: “The opening of our Madison manufacturing hub is a significant milestone for Abingdon Health USA that enables us to offer a more comprehensive and integrated ‘end to end’ CDMO (Contract Development and Manufacturing Organization) solution for our US customers, paving the way for continued growth in the biggest med-tech market in the world.

RECOMMENDED READING:

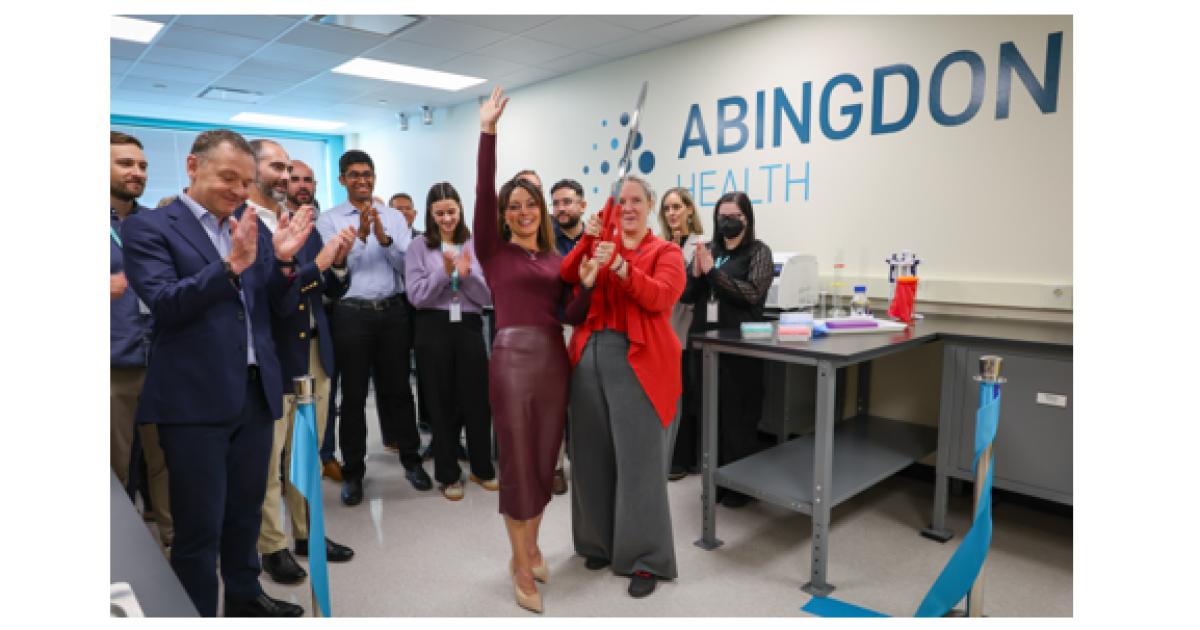
“We were delighted to welcome Representative Mark Pocan, Mayor Satya Rhodes-Conway, WEDC (Wisconsin Economic Development Company) Secretary John Miller and other legislative and industry leaders to the ribbon-cutting ceremony.

Their support throughout our journey is recognition of the importance of high-quality, domestic diagnostics manufacturing for the United States as well our investment in Madison and its community.”

The ribbon-cutting ceremony was attended by Congressman Mark Pocan, Madison Mayor Satya Rhodes-Conway, WEDC Secretary John Miller, representatives from the Wisconsin State Legislature, leaders of Wisconsin’s biohealth industry, and representatives from the Company.

The new facility is part of Abingdon Health’s strategy to expand its presence in the US market and support customers with products that are developed and manufactured domestically.

Abingdon Health Group serves an international customer base as a med-tech contract service provider.

The company was founded in 2008 and is headquartered in York, with additional laboratories in Doncaster and laboratories and commercial offices in Madison.

A spokesperson for Abingdon Health said: “The opening is an important milestone in the company’s continued expansion and investment in its US operations.”

More information can be found at abingdonhealth.com.

Free Training

Source link

Some Canadian manufacturers move to U.S. to survive tariffs


One day last December, Julian Reusing pulled his managers into a virtual meeting to lay bare an uncomfortable truth. 

His Quebec company, GoliathTech, a manufacturer of helical screw piles that operates on a franchise model, was getting battered by U.S. tariffs and running out of ways to keep its head above water.

Since the steel tariffs came into effect last March, the company has paid about $3.7 million in tariffs that it has split with its U.S. franchisees.

Reusing, 56, was eager to open a factory south of the border, but he was cash-strapped. Just days earlier, RBC had turned down financing for the company’s European franchise expansion.

Reusing appealed to his own employees for money.

There have been few moments in Canadian history when small and mid-sized manufacturers have faced such pressure. Insurmountable trade barriers with the U.S. have appeared overnight for some companies, suddenly cutting off their largest export market and forcing an urgent need to pivot.

The fight to survive can feel lonely, business owners told the Star. Several said the country’s support falls far short of what they need: the tariff relief programs don’t go far enough and structural threats to Canadian manufacturing competitiveness are making it difficult to replace lost U.S. business.


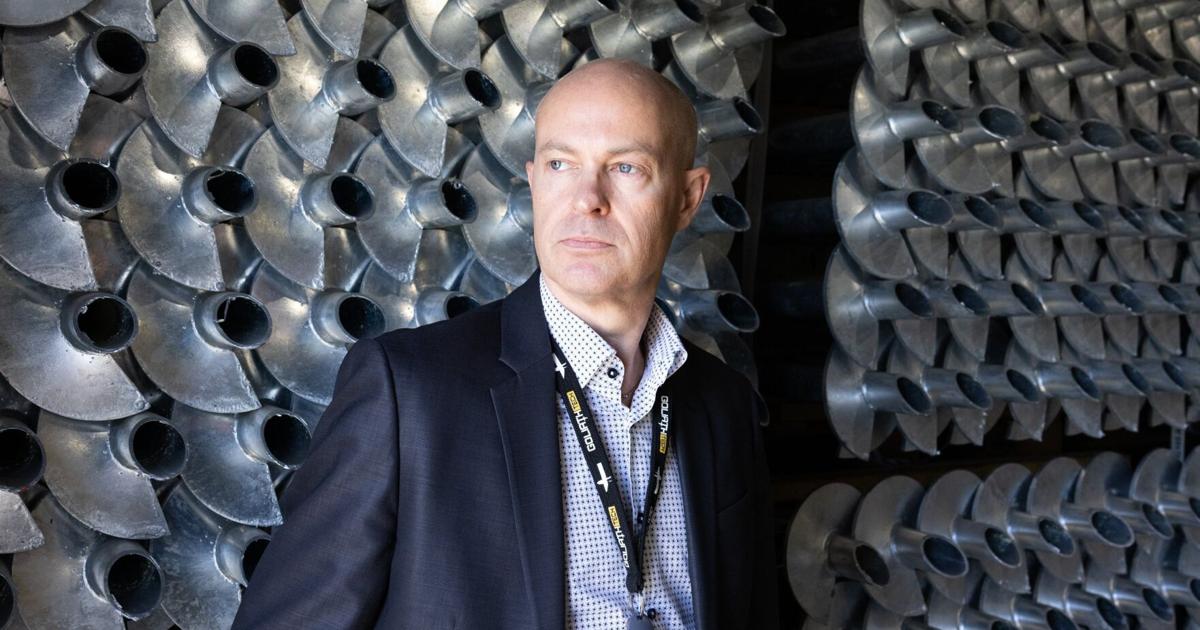
Julian Reusing.JPG

Over the past two years, GoliathTech’s Julien Reusing approached multiple Canadian government agencies and banks for financing, but was repeatedly turned down. He found his own investors to raise $2.4 million.


Luckily, GoliathTech did not go under that winter. 

Instead, following that pivotal meeting in December, the company raised $900,000 through an equity sale to six of its employees, alongside $1.5 million from a private investor. Reusing opened a small factory in Ohio in March after 10 months of planning in an effort to bypass most U.S. tariffs. He also added 19 European and British franchisees, expanding the firm’s global network to 190 locations as part of a broader restructuring.

“Without a shadow of a doubt, we would be a non-existent company right now if we didn’t make that move,” said Reusing, explaining why he chose to move some production south. “It’s impossible for a company to survive where for every hundred dollars you ship, you have to give fifty dollars to the government.”

Headquartered in Magog, Que., the 13-year-old company is turning a profit for the first time in three years — a turnaround that resulted from Reusing’s own scrambling, with little help from the Canadian government or financial institutions at home.

Many company owners are not nearly as fortunate, and he says Canada needs to do more before more of them are pushed to the brink.

“The government needs to come up with some programs that would teach people how to deal with this, not just offer money,” he said. “I don’t think everybody knows how to deal with a massive revolution.”

Why $7.5 billion in loans isn’t enough

It’s rare to find a clothing company that makes all of its products in Canada — about 95 per cent of the apparel sold here is manufactured outside the country.

When the 50-per-cent U.S. tariffs hit in August, Amit Thakkar feared they could spell the end of his Brampton textile company, Roopa Knitting Mills, which makes fabric for T-shirts, sweatshirts and leggings now caught in the tariff net.

Across the three Canadian clothing businesses he owns, Thakkar employs 120 people, with 50 to 70 per cent of sales destined for the U.S.

His disappointment only grew when Ottawa rolled out a $7.5-billion package to aid tariff-stricken businesses, the majority of which came in the form of loans. 

“If you want to know my honest truth, I think those are all bulls—t,” Thakkar said. “The Canadian government wants to give us loans, but we don’t have customers anymore.”

To Thakkar, the situation is reminiscent of a problem that emerged during the pandemic, when businesses took on emergency debt that some are still struggling to repay years later.

Thakkar says he believes the best way to save his business is for Ottawa to return counter-tariff revenue to companies affected by the trade war, giving them cash to cover tariff costs or lost sales.


GoliathTech 1.JPG

Julien Reusing considers himself lucky to have had the resources and experience to reshape GoliathTech. Many other businesses, he fears, do not have the same room to manoeuvre. 


“If this is like the same in six months,” said Thakkar, “we’re going to be talking about shutting down or moving to the U.S.,” adding that there just isn’t enough buy-in for Canadian-made clothes from the government or domestic consumers.

Before Reusing raised money on his own to restructure his business, he went to the Business Development Bank of Canada (BDC), which launched its Pivot to Grow program last March, offering up to $5 million in loans to help businesses stay afloat and break into new markets.

It seemed like a perfect fit for Reusing’s strategy, but he was denied financing because the business had reported losses in the past two years.

“I’ve spoken with the BDC, Investissement Québec, many different government entities, and we’ve had zero money from the government,” he said. “I lost faith.”

Reusing found investors on his own. 

Dennis Darby, president of Canadian Manufacturers and Exporters, said he is in constant contact with Ottawa to discuss the eligibility and access issues manufacturers are running into. The recent tariff-relief programs are well-intentioned, he said, but their success depends on execution and the speed of approvals.


Tube_laseer_cutter.JPG

A tube laser cutter in action at GoliathTech manufacturing.


“For these smaller manufacturers getting access to that funding, it can’t take six months,” he said.

Companies need more support at home

When Jack Dell’Accio set out to expand Essentia Organic Mattress in 2023, he faced a choice: scale up the company’s factory in Laval, Que., or open a second plant. He chose the latter, investing in a facility in Florida that opened last October.

Mattresses are not subject to the tariffs, and the move was driven purely by logistics costs, particularly the high shipping rates in Canada.

“I have no issues building in Canada all of our raw materials, but it’s our distribution of finished product that has challenges in Canada,” said Dell’Accio, whose company generates about 70 per cent of its sales in the U.S.

The Florida plant has cut Essentia’s shipping costs by about one-third, he said. It also brought an unexpected advantage: with no state personal income tax in Florida, Dell’Accio said Essentia can attract highly skilled engineers with lower salaries than it would need to offer in Quebec.

Alex Greco, senior director of manufacturing and value chains at the Canadian Chamber of Commerce, said tariffs are only one part of the equation when Canadian companies look south, alongside factors such as taxes, regulation, financing and supply chain proximity to customers.


GoliathTech 3.JPG

GoliathTech plate laser operator Stéphane Roy, removes helixes after they’ve been cut.


Canada needs to create a more attractive, business-friendly environment for domestic and foreign investment, so that it can reduce the risk of losing businesses to the U.S., he said.

“We can’t be like psychologists with the president of the United States, but we can control our own competitiveness,” said Greco. 

For Reusing, the solution starts with Canadian financial institutions doing more to back manufacturers.

After the tariffs took effect last March, Reusing approached RBC several times for financing to expand his European franchise network. It was not until December, he said, that his account manager told him the bank was no longer lending against European receivables and inventory.

“It was the ultimate blow because we’ve been with RBC for seven years, very solid, great relationship.”

When asked whether the bank pulled back from corporate financing in Europe, RBC said in a statement that it is unable to comment on individual clients for privacy reasons, but “that financing decisions are made on a client-by-client basis.”

“We see significant opportunity in Europe and are expanding our financing capacity in that market, while also continuing to support clients with cross-border financing needs,” the bank said.


GoliathTech 2.JPG

GoliathTech tube laser technician Josée Roy, who’s worked for nine years at company, arranges tubes. 


Reusing then turned to other Canadian banks, only to be told they would not lend to a company that was “losing money.” He eventually approached a U.S. bank, and the first one he tried agreed to back him.

Last week brought some uplifting news for Canada’s capital markets, as Ottawa unveiled a “productivity mega deduction” as part of its push to attract $1 trillion in new investment over five years.

The measure expands the range of capital assets eligible for businesses to immediately deduct in their first year of use and makes the incentive permanent.

“It’s hard to predict what the future holds for investments in Canada, but this is a policy change that absolutely provides a much stronger incentive for companies to invest in Canada,” said Trevor Tombe, an economics professor at the University of Calgary.

Mutual assured economic destruction

While tariffs have not directly affected Essentia Organic Mattress, they have brought some “social negativity” from Canadian customers when they learn the company operates a factory in the U.S., said Dell’Accio.


GoliathTech 4.JPG

GoliathTech laser cutting supervisor since 2020, Patrick Montmigny, prepares a machine for cutting new plates.


Dell’Accio said opening a plant across the border does not mean scaling back production in Canada, where the company still makes all of its raw materials. If anything, he said, the Florida operation gives Essentia a hedge against any future escalation in trade tensions.

“We’re a Canadian success story that exists in both markets and sometimes it feels that we’re forced to choose sides,” said Dell’Accio. “We can’t. We have a commitment and a customer base in both countries.”

Jim Stanford, economist and director of the Centre for Future Work, said there is no evidence of a migration of jobs to the United States from Canada or elsewhere. But what the data do show, he said, is that tariffs have taken a toll on manufacturing workforces on both sides of the border.

“In terms of Donald Trump’s trade war, this is a case of mutual assured destruction,” he said.

Between January 2025 and August 2026, Canadian manufacturing employment fell by 27,600, from 1.875 million to 1.847 million while the U.S. manufacturing workforce shrank by 35,000. Both countries, however, have seen a modest rebound in those numbers in recent months.

Since the new 50 per cent tariffs took effect, Northern Cables, which has manufactured commercial and industrial power cable with aluminum and copper conductors in Brockville and Prescott, Ont., for 30 years, has had to shut off its cross-border shipping.

Shelley Bacon, the company’s chief executive, said half of the company’s sales go to the U.S. and leadership will have to consider establishing a facility south of the border should the tariffs remain in place to the end of the year.

The Star, simplified

Breaking news, interactive polls, video, and voice notes. Star stories you’ll want to share, delivered where you’re already chatting. Follow the Star on WhatsApp.

Yet that offers no easy workaround, he said. Building an American operation from the ground up represents a massive capital undertaking. 

“If they have trade rules that say you can’t ship product into the country and you have a good customer base and wants to buy from you, you really don’t have a lot of choice here,” he said.

Northern Cables has not laid off any of its 320 workers, instead reassigning them to expand its Canadian product lines and pursue growth domestically. Expanding beyond North America is far from a quick fix. Different standards and measurement systems mean adapting products for Europe could take years, even decades, he added.

But at home, Bacon said some Asian cable makers blocked from the U.S. market by tariffs have been pouring product into Canada at prices so low that his company sometimes cannot even buy the raw materials cheaply enough to match them.

“You can only fight one battle at a time,” Bacon said. “We seem to be fighting two battles at the same time.”

‘If you take your time, you’re going to get eaten up’

It has been 18 months of improvising under pressure for GoliathTech’s Reusing, who kept the company afloat by engineering an entirely new operational playbook to survive the tariff shock.

On top of setting up a U.S. factory, he moved the engineering department to Mexico to cut costs, began manufacturing for two competitors and made 15 trips to Europe to drum up business.

Reusing acknowledged that he was fortunate to have decades of experience to lean on from working in his father’s manufacturing business at 13 to operating a previous franchise business active in 67 countries.

Simply handing out capital won’t solve every problem, Reusing said. What Ottawa really needs to do, he argues, is to launch targeted programs that train business leaders on how to restructure operations and rebuild on the fly.

“You have to do a revolution to your company instantly,” he said. “If you take your time, you’re going to get eaten up.”

Free Training

Source link

Kikkoman Opens Third U.S. Plant In Wisconsin With $560 Million Planned Investment


Kikkoman Foods Inc. (KFI), Kikkoman Corporation’s wholly owned U.S. manufacturing subsidiary headquartered in Walworth, Wisconsin, will operate the new plant. The company scheduled a grand opening ceremony for September 18, 2026, as it prepared to begin commercial shipments from the facility.

Construction of the Jefferson plant began in April 2024, and soy sauce brewing operations commenced in May 2026. The company expects to begin shipping products from the facility in October 2026, adding manufacturing capacity to its established North American production network.

The plant occupies a 100-acre site, equivalent to about 405,000 square meters, and includes about 240,000 square feet of total floor space. The steel-frame facility will produce soy sauce and soy sauce-related seasonings, with capabilities designed to accommodate a range of products tailored to customer needs.

Kikkoman’s planned investment of approximately $560 million, or ¥80 billion, over a 10-year period reflects its commitment to expanding manufacturing capacity in North America, which represents the largest market in the company’s overseas business. The investment figure represents the company’s longer-term spending plan rather than an amount already invested at the time of the opening.

The Jefferson facility becomes Kikkoman’s third production plant in the United States, joining its existing operations in Walworth, Wisconsin, and Folsom, California.

Kikkoman’s Walworth plant began commercial shipments in June 1973, establishing the company’s first U.S. manufacturing operation. The company subsequently expanded its American production network with its Folsom plant, which began shipments in October 1998.

The addition of Jefferson represents Kikkoman’s first new U.S. manufacturing location in nearly three decades. It also becomes the Kikkoman Group’s ninth soy sauce production base outside Japan, further expanding its international manufacturing footprint.

The new facility will help meet rising demand for soy sauce in North America, where the company has reported steadily increasing shipments from its existing Walworth headquarters plant.

By adding production capacity in Wisconsin, Kikkoman intends to strengthen its supply infrastructure while expanding its ability to manufacture different products for customers throughout the region.

The additional plant also provides greater manufacturing capacity within the company’s largest overseas market, complementing its existing operations in Wisconsin and California.

Kikkoman Foods Inc. was established in March 1972 and is wholly owned by Kikkoman Corporation. The subsidiary reported 274 employees as of March 31, 2026, including 218 employees at its Walworth facility and 38 at its Folsom plant.

Ryohei Tsuji, President and Chief Operating Officer of Kikkoman Foods Inc., leads the company’s U.S. operations.

The expansion forms part of Kikkoman’s broader international growth strategy under Global Vision 2030, established in 2018. One of the strategy’s central objectives is to establish Kikkoman Soy Sauce as a truly global seasoning by expanding its availability and adapting its offerings to different markets.

The Jefferson plant will support that objective by increasing the company’s manufacturing capacity in a market that has become central to its international business.

Kikkoman has also emphasized its commitment to maintaining strong relationships with the communities in which it operates. The new facility expands its longstanding manufacturing presence in Wisconsin, where it has maintained U.S. production operations for more than 50 years.

With brewing operations already underway and shipments scheduled to begin in October, the Jefferson plant adds a production base for Kikkoman as it pursues further growth in North America and strengthens its global supply network.

Free Training

Source link

‘Significant milestone’ as York firm launches US manufacturing facility


Published 25th Sep 2026, 11:31 BST

Updated 25th Sep 2026, 11:31 BST

Launched as part of the company’s plans to expand in the region, the new manufacturing hub is located in the company’s site at University Research Park in Madison, Wisconsin.

The firm said the new manufacturing facility represents a “significant step forward” for its US operations, providing it with the “infrastructure and capacity to expand its US footprint and respond to growing demand”.

It comes after Abingdon first established a presence in Wisconsin in April of 2025, opening a research lab and commercial office.

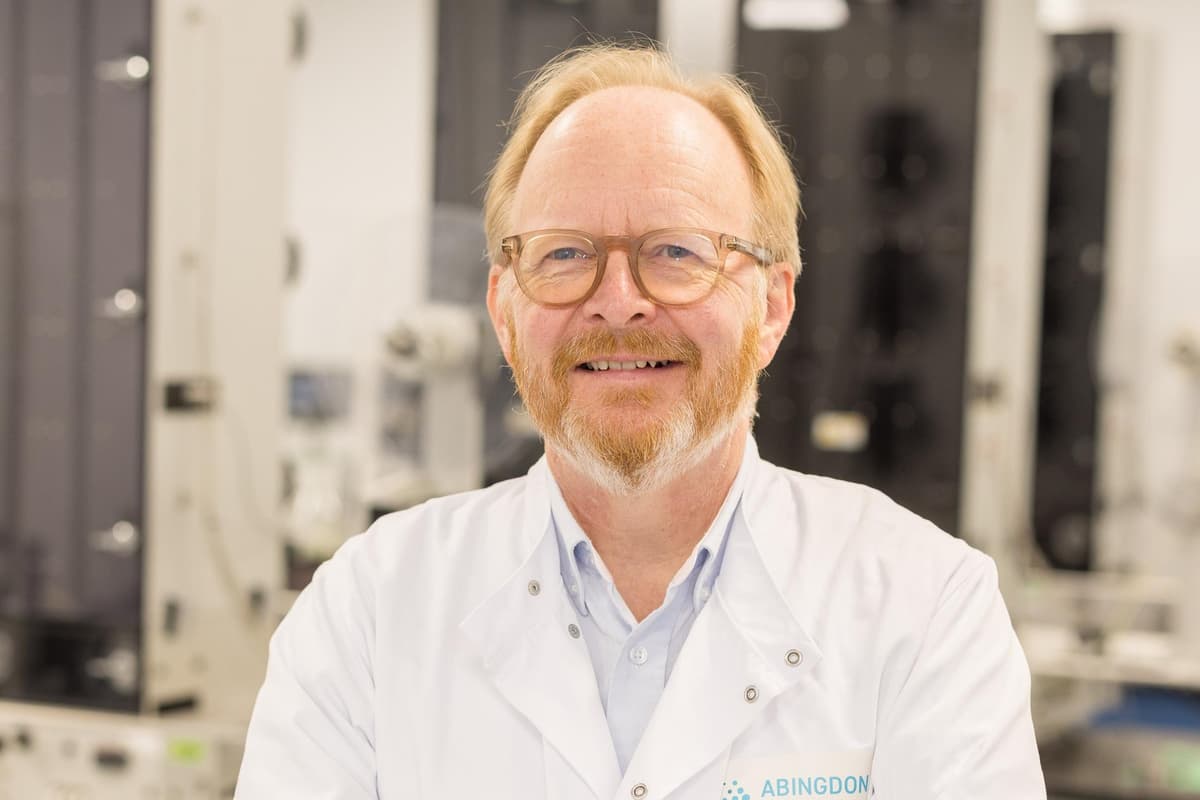
Dr Chris Hand, executive chairman of Abingdon Health.placeholder imageDr Chris Hand, executive chairman of Abingdon Health.

Speaking to The Yorkshire Post in March, Dr Chris Hand, executive chairman of Abingdon Health, said the choice to expand in the region had been driven by a demand from customers for “made in the USA solutions”.

The company raised £3.2m in October of last year to support the expansion.

Speaking on the opening of the new US facility, Chris Yates, president of Abingdon Health USA and chief commercial officer of the firm’s UK entity, said: “The opening of our Madison manufacturing hub is a significant milestone for Abingdon Health USA that enables us to offer a more comprehensive and integrated “end to end” CDMO solution for our US customers, paving the way for continued growth in the biggest med-tech market in the world.”

Abingdon Health develops and manufactures lateral flow tests, used to identify various illnesses and conditions. The company earlier this year launched a “world first” blood test designed to enable paramedics to more quickly identify strokes.

An official ribbon-cutting event for the firm’s new US site was attended by Congressman Mark Pocan, representing Wisconsin’s 2nd Congressional District, as well as Madison Mayor Satya Rhodes-Conway, WEDC Secretary John Miller, and other representatives from the Wisconsin State Legislature.

Mr Yates added: “We were delighted to welcome Representative Mark Pocan, Mayor Satya Rhodes-Conway, WEDC Secretary John Miller and other legislative and industry leaders to the ribbon-cutting ceremony.

“Their support throughout our journey is recognition of the importance of high-quality, domestic diagnostics manufacturing for the United States as well our investment in Madison and its community.”

As part of its expansion, Abingdon also recently listed on the OTCQB Venture Market in the US, trading under the abbreviation ABDXF.

In a trading update issued in July, Abingdon said its revenues had grown by more than 30 per cent – with further increases expected.

Updating investors on the financial year to the end of June 2026, the firm hailed strong growth in the second half of the financial year, with total revenue for the full year expected to reach £11.3m – 31 per cent on the £8.6m recorded 12 months before.

The company said there was a 63 per cent increase in revenue during the second half of the year compared to the first six months.

Free Training

Source link

Gold Near $4,300: Durable Goods Data and Fed Rate Tightening Risks – News and Statistics


Sep 25, 2026

Gold continued to hold its ground near the $4,300-an-ounce level, though the metal may face further headwinds as U.S. manufacturing activity remains relatively firm, according to Kitco News.

The Commerce Department reported Friday that U.S. durable goods orders were essentially flat in August, after a revised gain of 0.9% in July. The result came in slightly above expectations, since economists on consensus had projected a decline of 0.3%.

Core durable goods orders, which exclude the transportation sector, increased 0.3% in August, following a 0.4% rise in July. Consensus estimates had pointed to a 0.4% gain.

Non-defense capital goods orders excluding aircraft climbed 1.6% in August, well above expectations for a 0.5% increase.

Adam Button, head of currency strategy at investingLive, commented that while the headline figure was flat, the core orders carry more weight for the underlying direction of the economy, describing the number as strong and supportive of a bullish economic view.

The gold market showed little major reaction to the data. Spot gold last traded at $4,298.70 an ounce, up 0.60% on the day.

Some analysts noted that gold could still struggle, as the latest manufacturing data gives the Federal Reserve more room to keep tightening interest rates to address the persistent inflation threat.

  1. 1. INTRODUCTION

    Making Data-Driven Decisions to Grow Your Business

    1. REPORT DESCRIPTION
    2. RESEARCH METHODOLOGY AND THE AI PLATFORM
    3. DATA-DRIVEN DECISIONS FOR YOUR BUSINESS
    4. GLOSSARY AND SPECIFIC TERMS
  2. 2. EXECUTIVE SUMMARY

    A Quick Overview of Market Performance

    1. KEY FINDINGS
    2. MARKET TRENDS This Chapter is Available Only for the Professional EditionPRO
  3. 3. MARKET OVERVIEW

    Understanding the Current State of The Market and its Prospects

    1. MARKET SIZE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. CONSUMPTION BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. MARKET FORECAST TO 2035
  4. 4. MOST PROMISING PRODUCTS FOR DIVERSIFICATION

    Finding New Products to Diversify Your Business

    1. TOP PRODUCTS TO DIVERSIFY YOUR BUSINESS
    2. BEST-SELLING PRODUCTS
    3. MOST CONSUMED PRODUCTS
    4. MOST TRADED PRODUCTS
    5. MOST PROFITABLE PRODUCTS FOR EXPORT
  5. 5. MOST PROMISING SUPPLYING COUNTRIES

    Choosing the Best Countries to Establish Your Sustainable Supply Chain

    1. TOP COUNTRIES TO SOURCE YOUR PRODUCT
    2. TOP PRODUCING COUNTRIES
    3. TOP EXPORTING COUNTRIES
    4. LOW-COST EXPORTING COUNTRIES
  6. 6. MOST PROMISING OVERSEAS MARKETS

    Choosing the Best Countries to Boost Your Export

    1. TOP OVERSEAS MARKETS FOR EXPORTING YOUR PRODUCT
    2. TOP CONSUMING MARKETS
    3. UNSATURATED MARKETS
    4. TOP IMPORTING MARKETS
    5. MOST PROFITABLE MARKETS
  7. 7. PRODUCTION

    The Latest Trends and Insights into The Industry

    1. PRODUCTION VOLUME AND VALUE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. PRODUCTION BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  8. 8. IMPORTS

    The Largest Import Supplying Countries

    1. IMPORTS: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. IMPORTS BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. IMPORT PRICES BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  9. 9. EXPORTS

    The Largest Destinations for Exports

    1. EXPORTS: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. EXPORTS BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. EXPORT PRICES BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  10. 10. PROFILES OF MAJOR PRODUCERS

    The Largest Producers on The Market and Their Profiles

  11. 11. COUNTRY PROFILES

    The Largest Markets And Their Profiles

    This Chapter is Available Only for the Professional Edition
    PRO

    1. 11.1

      United States

      • Market Size
      • Production
      • Imports
      • Exports
    2. 11.2

      China

      • Market Size
      • Production
      • Imports
      • Exports
    3. 11.3

      Japan

      • Market Size
      • Production
      • Imports
      • Exports
    4. 11.4

      Germany

      • Market Size
      • Production
      • Imports
      • Exports
    5. 11.5

      United Kingdom

      • Market Size
      • Production
      • Imports
      • Exports
    6. 11.6

      France

      • Market Size
      • Production
      • Imports
      • Exports
    7. 11.7

      Brazil

      • Market Size
      • Production
      • Imports
      • Exports
    8. 11.8

      Italy

      • Market Size
      • Production
      • Imports
      • Exports
    9. 11.9

      Russian Federation

      • Market Size
      • Production
      • Imports
      • Exports
    10. 11.10

      India

      • Market Size
      • Production
      • Imports
      • Exports
    11. 11.11

      Canada

      • Market Size
      • Production
      • Imports
      • Exports
    12. 11.12

      Australia

      • Market Size
      • Production
      • Imports
      • Exports
    13. 11.13

      Republic of Korea

      • Market Size
      • Production
      • Imports
      • Exports
    14. 11.14

      Spain

      • Market Size
      • Production
      • Imports
      • Exports
    15. 11.15

      Mexico

      • Market Size
      • Production
      • Imports
      • Exports
    16. 11.16

      Indonesia

      • Market Size
      • Production
      • Imports
      • Exports
    17. 11.17

      Netherlands

      • Market Size
      • Production
      • Imports
      • Exports
    18. 11.18

      Turkey

      • Market Size
      • Production
      • Imports
      • Exports
    19. 11.19

      Saudi Arabia

      • Market Size
      • Production
      • Imports
      • Exports
    20. 11.20

      Switzerland

      • Market Size
      • Production
      • Imports
      • Exports
    21. 11.21

      Sweden

      • Market Size
      • Production
      • Imports
      • Exports
    22. 11.22

      Nigeria

      • Market Size
      • Production
      • Imports
      • Exports
    23. 11.23

      Poland

      • Market Size
      • Production
      • Imports
      • Exports
    24. 11.24

      Belgium

      • Market Size
      • Production
      • Imports
      • Exports
    25. 11.25

      Argentina

      • Market Size
      • Production
      • Imports
      • Exports
    26. 11.26

      Norway

      • Market Size
      • Production
      • Imports
      • Exports
    27. 11.27

      Austria

      • Market Size
      • Production
      • Imports
      • Exports
    28. 11.28

      Thailand

      • Market Size
      • Production
      • Imports
      • Exports
    29. 11.29

      United Arab Emirates

      • Market Size
      • Production
      • Imports
      • Exports
    30. 11.30

      Colombia

      • Market Size
      • Production
      • Imports
      • Exports
    31. 11.31

      Denmark

      • Market Size
      • Production
      • Imports
      • Exports
    32. 11.32

      South Africa

      • Market Size
      • Production
      • Imports
      • Exports
    33. 11.33

      Malaysia

      • Market Size
      • Production
      • Imports
      • Exports
    34. 11.34

      Israel

      • Market Size
      • Production
      • Imports
      • Exports
    35. 11.35

      Singapore

      • Market Size
      • Production
      • Imports
      • Exports
    36. 11.36

      Egypt

      • Market Size
      • Production
      • Imports
      • Exports
    37. 11.37

      Philippines

      • Market Size
      • Production
      • Imports
      • Exports
    38. 11.38

      Finland

      • Market Size
      • Production
      • Imports
      • Exports
    39. 11.39

      Chile

      • Market Size
      • Production
      • Imports
      • Exports
    40. 11.40

      Ireland

      • Market Size
      • Production
      • Imports
      • Exports
    41. 11.41

      Pakistan

      • Market Size
      • Production
      • Imports
      • Exports
    42. 11.42

      Greece

      • Market Size
      • Production
      • Imports
      • Exports
    43. 11.43

      Portugal

      • Market Size
      • Production
      • Imports
      • Exports
    44. 11.44

      Kazakhstan

      • Market Size
      • Production
      • Imports
      • Exports
    45. 11.45

      Algeria

      • Market Size
      • Production
      • Imports
      • Exports
    46. 11.46

      Czech Republic

      • Market Size
      • Production
      • Imports
      • Exports
    47. 11.47

      Qatar

      • Market Size
      • Production
      • Imports
      • Exports
    48. 11.48

      Peru

      • Market Size
      • Production
      • Imports
      • Exports
    49. 11.49

      Romania

      • Market Size
      • Production
      • Imports
      • Exports
    50. 11.50

      Vietnam

      • Market Size
      • Production
      • Imports
      • Exports
  12. LIST OF TABLES

    1. Key Findings In 2025
    2. Market Volume, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    3. Market Value: Historical Data (2012–2025) and Forecast (2026–2035)
    4. Per Capita Consumption, by Country, 2022–2025
    5. Production, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    6. Imports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    7. Imports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    8. Import Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    9. Exports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    10. Exports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    11. Export Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
  13. LIST OF FIGURES

    1. Market Volume, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    2. Market Value: Historical Data (2012–2025) and Forecast (2026–2035)
    3. Consumption, by Country, 2025
    4. Market Volume Forecast to 2035
    5. Market Value Forecast to 2035
    6. Market Size and Growth, By Product
    7. Average Per Capita Consumption, By Product
    8. Exports and Growth, By Product
    9. Export Prices and Growth, By Product
    10. Production Volume and Growth
    11. Exports and Growth
    12. Export Prices and Growth
    13. Market Size and Growth
    14. Per Capita Consumption
    15. Imports and Growth
    16. Import Prices
    17. Production, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    18. Production, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    19. Production, by Country, 2025
    20. Production, In Physical Terms, by Country: Historical Data (2012–2025) and Forecast (2026–2035)
    21. Imports, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    22. Imports, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    23. Imports, In Physical Terms, By Country, 2025
    24. Imports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    25. Imports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    26. Import Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    27. Exports, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    28. Exports, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    29. Exports, In Physical Terms, By Country, 2025
    30. Exports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    31. Exports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    32. Export Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)

Free Training

Source link

U.S. Manufacturing Boosts Capex Expectations


Written by Danny Levin, Deputy Editor for IIR News Intelligence (Sugar Land, Texas)

Summary

A recent outlook survey indicates U.S. manufacturers expect an increase in capital spending over the next 12 months. Industrial Info Resources project data shows U.S. manufacturing industry construction remains robust.

U.S. Manufacturers Expect More Capex

U.S. manufacturers reported another increase in expected capital expenditures over the next 12 months, based on the latest outlook survey by the National Association of Manufacturers (NAM).

According to Industrial Info Resources data, there is $785 billion worth of capital U.S. Industrial Manufacturing Industry projects under construction, with another $278 billion that could kick off in the fourth quarter.

While not all of those fourth-quarter kickoffs will move forward as planned, IIR data show $117 billion worth of projects kicked off in fourth-quarter 2025.

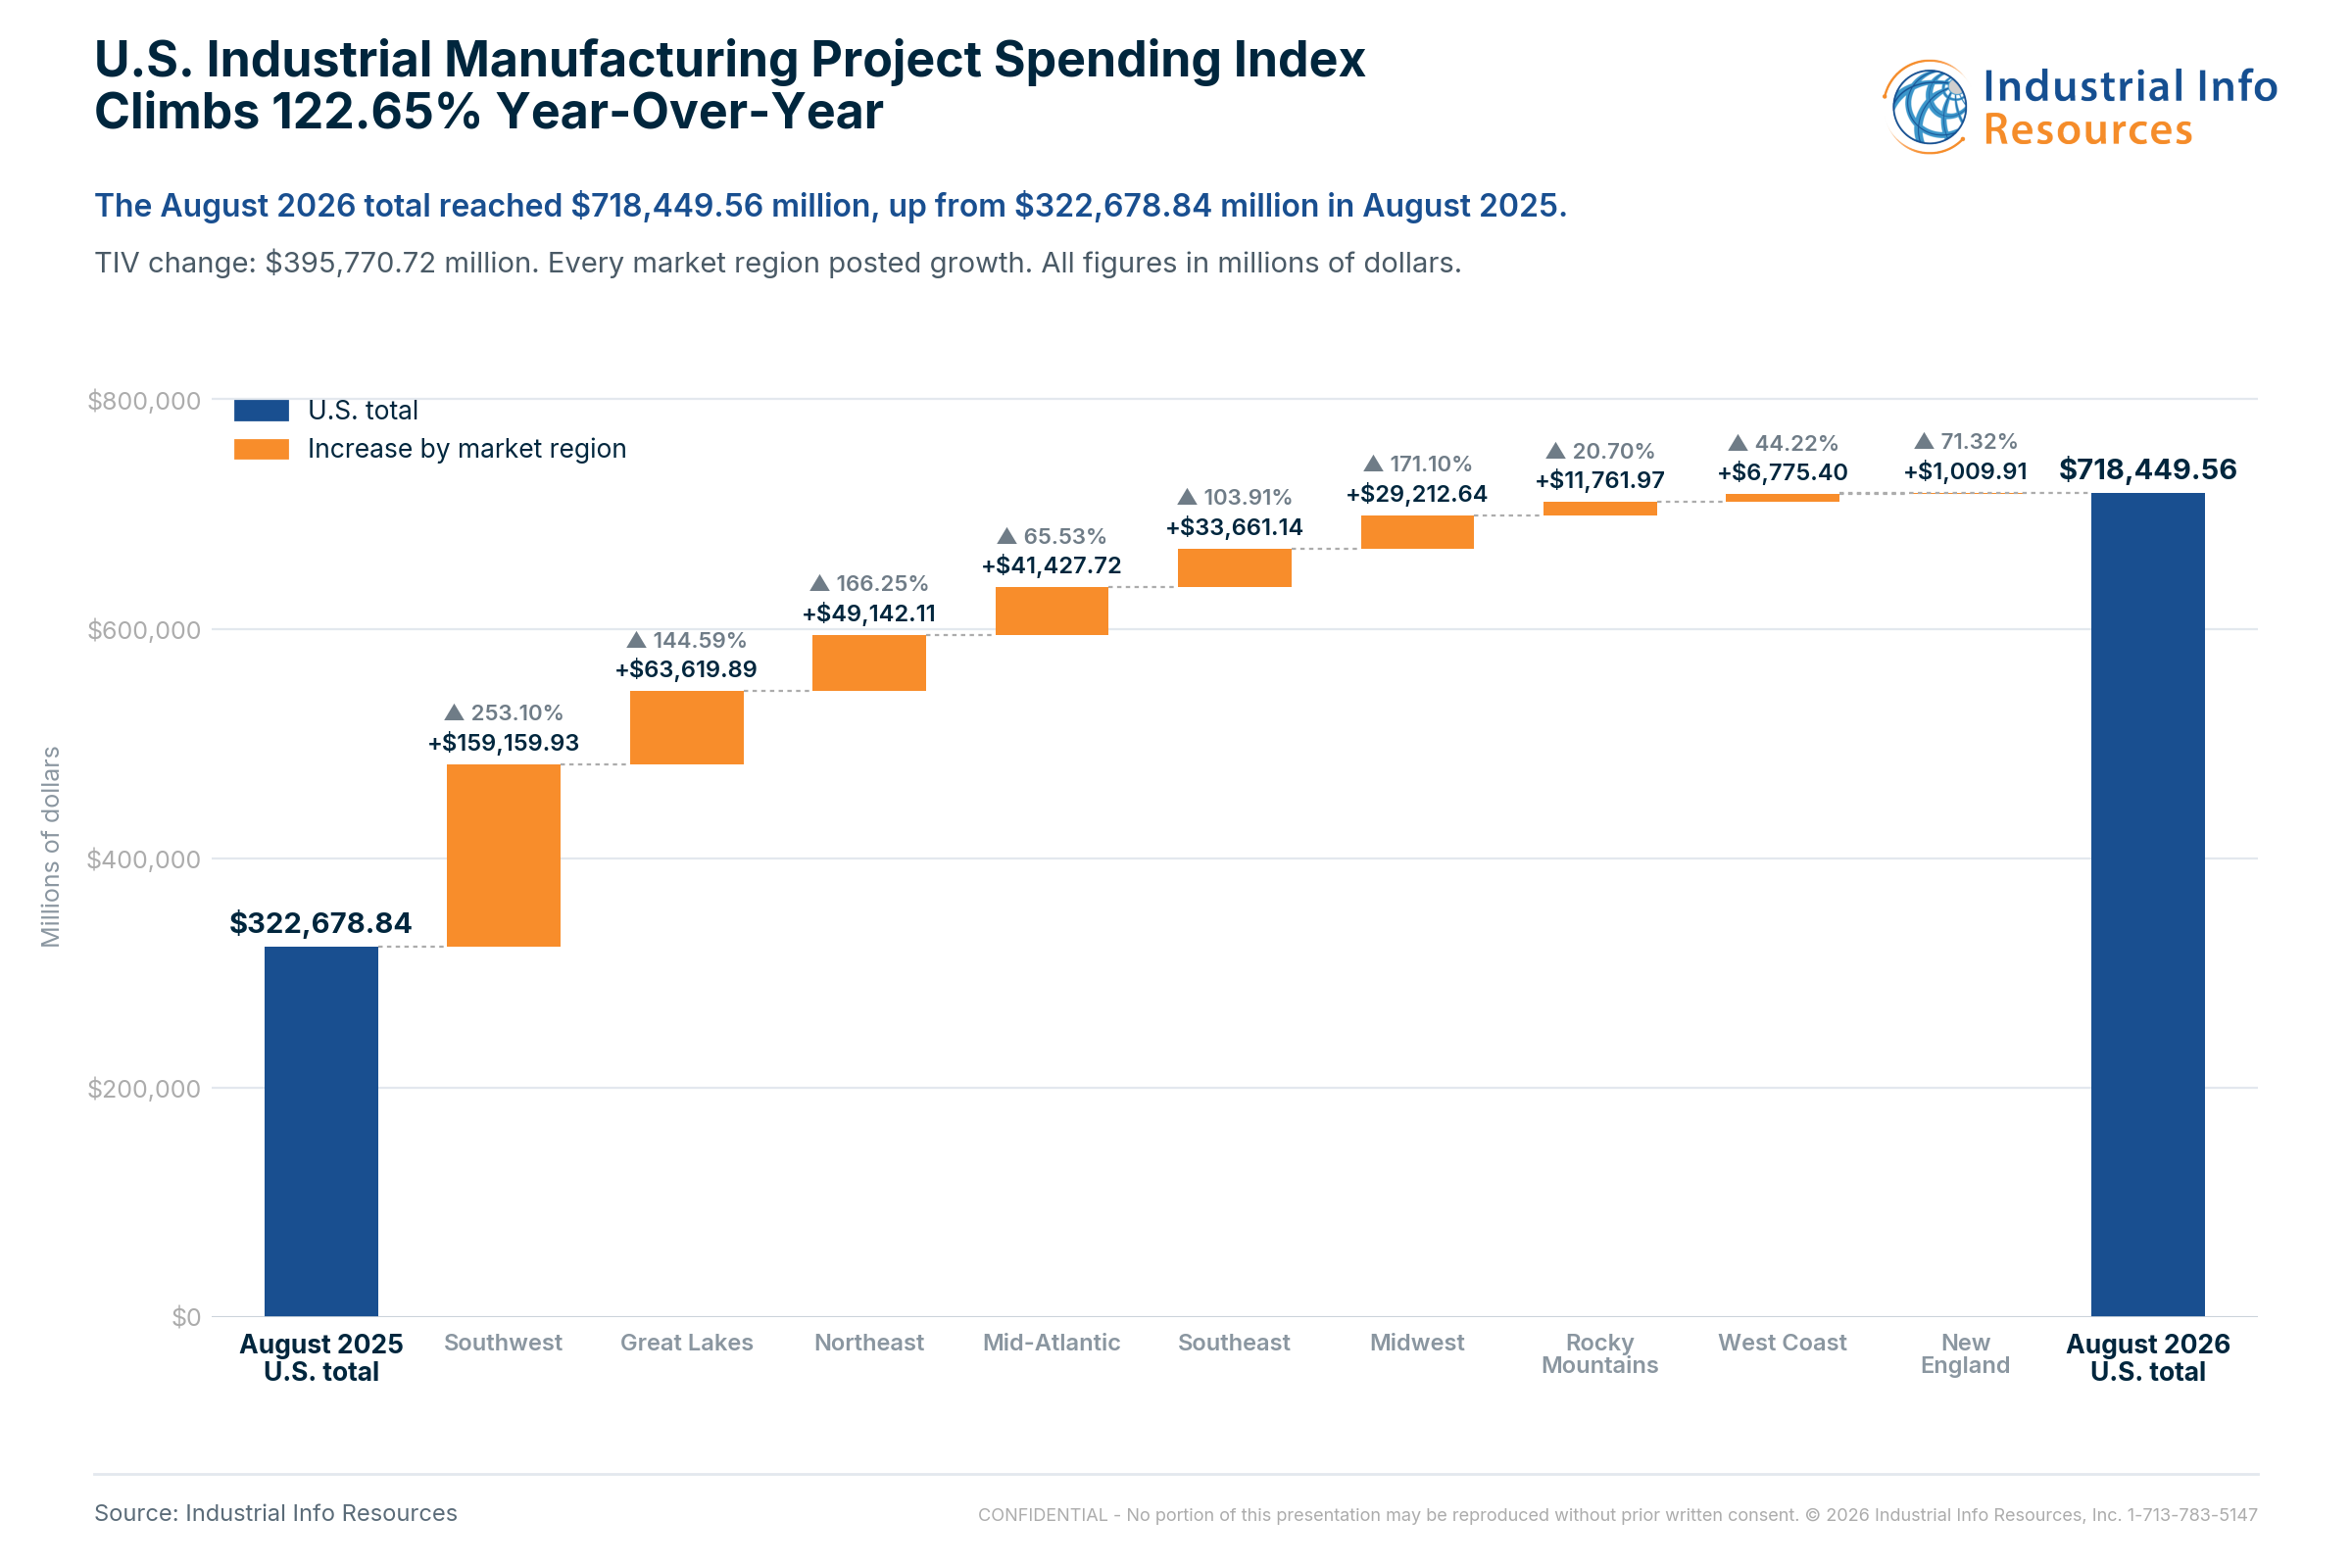
IIR’s North American Industrial Project Spending Index–which tracks both capital and maintenance project activity–for the U.S. Industrial Manufacturing industry also shows strong spending: The monthly index for August (the latest available data) shows project spending was $718.4 billion–up 122.65% from $322.7 billion in August 2025.

Attachment

The NAM survey ran from August 11 to August 27 and received 220 responses, featuring small (those with 49 or less employees), medium-sized (between 50 and 499 employees) and large manufacturers (500 or more employees).

According to the survey results, which were released September 14, respondents anticipated an increase of 2.6% in capital spending over the next 12 months–an increase from 1.8% and 1.7% in the first and second quarters, respectively.

Nearly 50% of the respondents indicated they expected additional capital spending in the next year (up from 37.1% last quarter), with 39.4% predicting no change and 11.3% forecasting reduced capital expenditures. Large firms forecast the highest level of investment, projecting a 2.9% increase over the next 12 months.

On another positive note, the overall sentiment improved to a four-year high: 78.9% of respondents were positive about their own company’s outlook, up 4.7% from the previous quarter.

…But Challenges Remain


The survey respondents reported increased raw material costs as their top business challenge, followed by rising healthcare costs and trade uncertainties (e.g. actual or proposed tariffs, trade negotiations uncertainty).

Respondents anticipate raw material prices and other input costs will rise 5% over the next 12 months, down from 5.8% that was expected in the second quarter. Overall, about 90% expect an increase in raw material costs over the next year, with nearly half anticipating increases exceeding 5%.

The Middle East conflict in particular continues to pose a challenge: “When asked how challenges, such as higher input costs, difficulty sourcing inputs and supply-chain disruptions, arising from the conflict in the Middle East compare to last quarter, nearly one-third (33.2%) said challenges have worsened. At the same time, 60.6% said that challenges were about the same as three months ago, while only 6.2% have seen their situation improve.”

In addition, respondents indicated freight rates and fuel costs are hurting supply chains.

Manufacturing Construction Projects


Data centers play the dominant role in manufacturing projects being tracked by Industrial Info Resources. This includes Amazon Web Services’ ongoing construction of 14 artificial intelligence (AI) data center buildings in New Carlisle, Indiana, alongside 18 operational buildings. Upon full buildout, the overall footprint would span roughly 6.5 million square feet, require 2.25 gigawatts of grid power, and run strictly on Amazon’s proprietary Trainium2 AI chips. The GMI data show the first six buildings out of the new 14 are under construction, with eight subsequent buildings kicking off by the end of 2029.

The Industrial Info Resources Global Market Intelligence (GMI) Industrial Manufacturing Plant and Project databases offer more information–including construction schedules, investment values and necessary equipment–in a plant profile and detailed project reports.

Key Takeaways

  • According to a recent survey, U.S. manufacturers expect capital spending will increase 2.6% over the next 12 months.
  • Challenges for manufacturers stemming from the Middle East conflict have worsened.
  • $785 billion: Total investment value of U.S manufacturing projects under construction.

About Industrial Info Resources
Industrial Info Resources (IIR) is the leading provider of industrial market intelligence. Since 1983, IIR has provided comprehensive research, news and analysis on the industrial process, manufacturing and energy related industries. IIR’s Global Market Intelligence (GMI) helps companies identify and pursue trends across multiple markets with access to real, qualified and validated plant and project opportunities. Across the world, Industrial Info Resources is tracking over 250,000 current and future projects worth $30.2 trillion (USD).

Free Training

Source link

US Manufacturing Revival Fosters Derivatives Plays as High-Tech Outpaces Traditional Industry


US manufacturing is showing a revival after a long period of weak momentum, with survey data indicating stronger activity. The ISM production index has moved from sub-50 contraction territory to levels consistent with firmer growth ahead, while business surveys point to solid order books. Over the next three years, manufacturing volumes are projected to rise by 1.5–2% per year, a pace framed against the sluggish backdrop of the past two decades.

The upturn is expected to be uneven. Advanced, highly automated, high value-added industries linked to the AI and technology cycle are positioned to expand, with pharmaceuticals, tech, transport and aerospace, and electrical and power-related segments cited as areas of strength. By contrast, more traditional, labour-intensive production faces further retrenchment unless it can command a “made in America” price premium, while heavy industry such as steel sits between the two. Relative growth differentials also support the US manufacturing proposition: from 2023 to 2026, the US economy is averaging 2.5% year-on-year volume growth versus 0.9% in Europe.

Strategies for Capitalizing on the Manufacturing Divide

With the US economy outpacing Europe with a 2.5% average growth rate over the last three years, we should position our derivative portfolios to capitalize on a starkly divided manufacturing sector. We recommend buying medium-term call options on advanced manufacturing, aerospace, and semiconductor ETFs like the iShares US Aerospace & Defense ETF (ITA) or the VanEck Semiconductor ETF (SMH). This strategy leverages the massive wave of AI-driven capital expenditure and defense spending that is keeping order books full for high-tech firms.

Conversely, we must hedge this bullishness by purchasing put options on traditional, labor-intensive industrial companies that are suffering from high domestic wages. Sectors like basic textiles or low-value metal fabrication cannot absorb these wage pressures and are poised to contract further. Targeting weak components of the Russell 2000 index with put spreads will protect our portfolios as these low-margin businesses retrench.

Opportunities in Utilities and Volatility Trades

The massive power demands of AI data centers and highly automated factories mean we should also look at utilities and energy derivatives. Historically, US industrial electricity consumption has spiked alongside manufacturing construction spending, which recently hovered around an unprecedented $230 billion annualized rate. We suggest using bull call spreads on the Utilities Select Sector SPDR Fund (XLU) to capture this secular power surge.

As we watch the ISM Manufacturing Index fluctuate around the expansion-contraction threshold, we expect heightened volatility in industrial equities over the coming weeks. We should deploy long straddles on broad industrial ETFs like the Industrial Select Sector SPDR Fund (XLI) ahead of upcoming October economic releases. This allows us to profit from the sharp market reactions as the divide between high-tech champions and struggling traditional factories widens.

Start trading now — click

Free Training

Source link

Eli Lilly Advances U.S. Manufacturing Buildout


Reports related to this article:

Written by Danny Levin, Deputy Editor for IIR News Intelligence (Sugar Land, Texas)

Summary

Amid a $50 billion plan to reshore medicine production, Eli Lilly broke ground on a $6.5 billion manufacturing plant in Houston, Texas. Industrial Info Resources is tracking $57 billion worth of active and planned projects from Eli Lilly worldwide, about 90% of which is in the U.S.

New U.S. Plant Construction

Eli Lilly and Company recently broke ground on a $6.5 billion manufacturing plant in Houston, Texas, which is part of a $50 billion plan to reshore production to the U.S. Industrial Info Resources data show $57 billion worth of active and planned projects from Eli Lilly worldwide, about 90% of which is in the U.S.

The company has said the multibillion-dollar effort is designed to “meet growing demand at home and export American-made medicines to people around the world.”

This comes as major global pharma and biotech companies have been hard at work reshoring and expanding domestic production in the face of U.S. demand and potential import tariffs. However, Eli Lilly and 16 other large drugmakers are exempt from President Donald Trump’s 100% Section 232 tariff on imported patented drugs and their active pharmaceutical ingredients (APIs)–the chemical compounds in medicine–that was set to take effect on July 31.

Annette Kreuger, Industrial Info’s vice president of research for the Pharma-Biotech Industry, said: “We have definitely seen a spike in domestic capital activity. It surpasses anything experienced during the pandemic.”

“The vast majority of these projects are in the biological sector–the cash cow, if you will, for the industry,” she continued. “Tariffs and policy can change with the wind, but one thing is certain: Companies want to ensure supply of their most profitable drugs. What is good about these plants is their flexibility to change over to other products as they come to the commercial production stage.”

“Will the growth spike continue? It can’t, not at this level, and it will settle down into a more normal pattern of investment. But, make no mistake, these massive projects are making it to construction all over the country.”

Eli Lilly’s plant under construction in Houston will produce APIs that will support planned production of medicine such as Foundayo (orforglipron), Lilly’s first U.S. Food & Drug Administration-approved, once-daily oral pill for weight loss that can be taken without food or water restrictions. The plant also will support other small-molecule medicines and advanced therapeutics. Construction is expected to wrap up next year.

Lilly has said Foundayo is under regulatory review in more than 40 countries, with a full global rollout targeted for 2027. The company also is studying Foundayo for other applications, including type 2 diabetes and obstructive sleep apnea.

Industrial Info Resources offers more information on the Houston project in its Global Market Intelligence (GMI) Pharmaceutical-Biotech Plant and Project databases, where readers can find details–including construction schedules, investment values and key contacts–in a plant profile and related project reports.

GLP-1s, in particular, are a main focus for Eli Lilly and are driving billions of dollars’ worth of investment for the company, as well as the global pharma and bio industry. For more information, see August 27, 2026, article – GLP-1 Drugs Drive Pharma Construction Wave.

The project marks one of 10 U.S. manufacturing sites–and its fifth location to produce U.S.-based APIs–announced by Eli Lilly since 2020.

Eli Lilly’s Other Investment Projects


Other domestic projects underway aimed at producing APIs for GLP-1s include construction of the Lilly Lebanon API manufacturing plant in Lebanon, Indiana, which is designed for mass production of Zepbound, Mounjaro and Foundayo. The plant is part of a larger complex that also includes the $4.5 billion Lilly Medicine Foundry, which is designed for the research, trial-supply production and manufacturing process development for Zepbound and Mounjaro.

When fully operational, Lilly Lebanon API would be the largest API manufacturing site in U.S. history. Readers can view a detailed list of project reports related to Eli Lilly’s overall investment in Lebanon, which includes ongoing construction of an advanced therapies campus.

Other planned API plants are located near Richmond, Virginia, and Huntsville, Alabama.

Manufacturing sites also are planned for the production of injectable medicines and manufacturing devices, including those in Concord, North Carolina, Kenosha, Wisconsin, and Lehigh Valley, Pennsylvania.

Industrial Info Resources offers a full list of reports for active and planned Eli Lilly projects across the U.S. and worldwide.

Lilly has a major presence in Europe and plans to spend US$3 billion on an oral solid medicines manufacturing facility in Katwijk, Netherlands, which is designed to support medication such as orforglipron. Final construction permits are still under review. Readers can view more information here.

Industrial Info Resources also offers a full list of detailed reports for projects mentioned in this article, and a full list of related plant profiles.

Key Takeaways

  • $57 billion: Total investment value of active and planned projects from Eli Lilly worldwide, about 90% of which is in the U.S.
  • Production of APIs, especially for GLP-1s, is a main focus.

About Industrial Info Resources
Industrial Info Resources (IIR) is the leading provider of industrial market intelligence. Since 1983, IIR has provided comprehensive research, news and analysis on the industrial process, manufacturing and energy related industries. IIR’s Global Market Intelligence (GMI) helps companies identify and pursue trends across multiple markets with access to real, qualified and validated plant and project opportunities. Across the world, Industrial Info Resources is tracking over 250,000 current and future projects worth $30.2 trillion (USD).

Free Training

Source link

Ernst, Miller-Meeks Bill to Strengthen U…


WASHINGTON – Today, the U.S. Senate unanimously passed U.S. Senator Joni Ernst’s (R-Iowa) bipartisan Critical Infrastructure Manufacturing Feasibility Act to decrease our reliance on foreign adversaries for key materials and boost manufacturing in rural America.

The bill instructs the Secretary of Commerce to identify critical goods that are currently being imported and find ways to help domestic producers manufacture them in rural areas and industrial parks, boosting manufacturing here at home.

The bill now heads to the president’s desk to be signed into law.

2026-09-23 JKE Floor Speech on Critical Manufacturing Bill

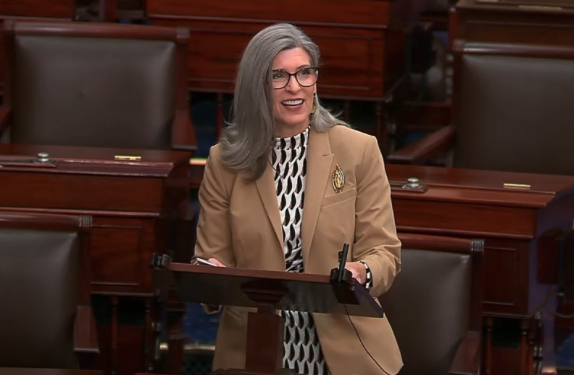
Ernst spoke on the Senate floor ahead of its passage.

“My bipartisan bill will identify vulnerabilities in our supply chains and help bring manufacturing back to rural America, where Iowans are ready to roll up their sleeves, get to work, and once again make ‘Made in America’ the norm instead of the exception,” said Sen. Ernst. “I look forward to President Trump signing it into law.”

“Iowa has the skilled workforce, manufacturing expertise, and strong communities America needs to lead the next generation of domestic manufacturing. For too long, critical production has moved overseas, leaving American workers behind and making our country dependent on foreign supply chains,” said Rep. Miller-Meeks. “This bipartisan bill gives us a roadmap to bring that production home, create more opportunities for Iowa workers, and strengthen our nation’s economic and national security. I’m proud to have led this effort with Senator Ernst and grateful for her partnership in getting it across the finish line.”

“Supply chains are critical to global competitiveness and our national security,” said Sen. Blunt Rochester. “I’m proud to see this bipartisan legislation pass into law to help identify where we are over-reliant on foreign imports for critical infrastructure and explore how we can bring that manufacturing back to the United States. These investments will strengthen domestic production, secure our supply chains, and support good-paying jobs right here at home.”

“We have become heavily dependent upon overseas supply chains, leaving us vulnerable to increased cybersecurity risks and price fluctuations,” said Sen. Ossoff. “This bipartisan bill will take steps to mitigate those risks, while helping open the door to new manufacturing jobs in Georgia and across the nation.”

Ernst’s full remarks as delivered below:

“Mr. President, I’m here today to talk a little more about our national and economic security of the United States. This has really been the focus of my career, protecting that national and economic security.

“In 1940, the United States became the ‘Arsenal of Democracy,’ and our country came together to quickly accelerate production of the weapons, vehicles, food, and supplies that enabled the Allies to defeat the Axis powers.

“Americans in factories, farms, small businesses, and across the country did what was necessary to make what was needed.

“Instead of internalizing the lesson that our ability to make these critical items in the United States led to great success…we spent much of the last 50 years offshoring our jobs and manufacturing capabilities.

“This is something China, Russia, and other nefarious actors around the world have all been too happy to accommodate and take on themselves.

“Today, we have only ONE active facility producing cannon barrels.

“Today, we rely 100 percent on foreign sources for 12 critical minerals essential to our military and our economy.

“During COVID, we saw what happens when supply chains are strained.

“There was a global shortage of microchips, which upended manufacturers’ ability to make everything from cars to computers. At the same time, moms in the Midwest had to worry about finding baby formula due to supply chain issues at both the production and shipping levels.

“Put simply: we’ve lost the ability to make what we need right here at home.

“In the event of a conflict with one of our near-peer adversaries, supply chains will be challenged, and the United States will have to make what it needs.

“Thank goodness President Trump, his administration, and Congress have been taking steps to put us on the right track and bring back the manufacturing capabilities we need right here at home.

“My bipartisan Critical Infrastructure Manufacturing Feasibility Act builds on these efforts.

“My bill, which has already passed the Senate unanimously, directs the Secretary of Commerce to identify critical goods that are currently being imported and find ways to help domestic producers manufacture them in rural areas and shovel-ready industrial sites.

“Rural Iowans are ready to roll up their sleeves and build the factories and processing facilities we need to secure our supply chains.

“We can and need to make things here.

“But you can’t fix vulnerabilities you can’t see.

“Which is why my bill gives Congress and the Executive Branch the visibility necessary to identify gaps and close them.

“I am grateful to Representative Mariannette Miller-Meeks for introducing the House version of this bill, and for the House of Representatives passing the bill unanimously.

“Now it is time for the Senate to act and send this bill to the President’s desk. Thank you.”

###

Free Training

Source link

India Services Hits 55.8, US Manufacturing Hits 57


Market snapshot: Global economic momentum accelerated sharply in September 2026, driven by a strong rebound in India’s services activity and an impressive dual expansion in both manufacturing and services in the United States. India’s preliminary services PMI climbed to 55.8, while US S&P Global manufacturing activity recorded its fastest rate of expansion since May 2022 at 57.0.

Data Snapshot

  • The preliminary HSBC India Services PMI rebounded to 55.8 in September 2026, up from 54.1 in August 2026.
  • The US S&P Global Manufacturing PMI surged to 57.0 in September 2026, exceeding market estimates.
  • The US S&P Global Services PMI climbed to 58.7 in September 2026, compared to 56.5 in the previous month.
  • The HSBC India Composite PMI rose to 56.5 in September 2026, up from 54.3 in August, signaling a broad-based recovery.

What’s Changed

  • The Indian services activity expansion rate accelerated by 1.7 points month-on-month (derived: September flash of 55.8 vs August final of 54.1).
  • The US S&P Global Manufacturing PMI registered a sharp 3.1-point monthly increase, rising from 53.9 in August to 57.0 in September.
  • The US S&P Global Services PMI expanded by an additional 2.2 points to hit 58.7 in September compared to 56.5 in August.

Key Takeaways

  • Stronger output growth and resilient new business inflows drove the sharp recovery in India’s services sector.
  • The US economy is showing intense momentum, with manufacturing output expanding at its fastest rate since mid-2022 and jobs growth hitting multi-year highs.
  • Underlying price pressures have picked up in both the US and Indian economies, primarily fueled by rising fuel, transportation, and material costs.
  • The stronger-than-expected US data has significantly increased investor expectations of a hawkish stance or potential rate hike from the Federal Reserve in upcoming meetings.

SAHI Perspective

The synchronized surge in economic activity across India and the US highlights strong global demand but brings inflation back into sharp focus. For India, the recovery in services is a relief after August’s multi-year low. However, in the US, the dramatic expansion in both manufacturing and services to multi-year highs suggests that the economy remains highly resilient despite previous rate hikes. This resilience is likely to keep the Federal Reserve hawkish, potentially putting upward pressure on yields and creating a challenging environment for emerging market capital flows, even as domestic corporate earnings are supported by robust demand.

Market Implications

A stronger US economic footprint reinforces US Dollar strength and pushes Treasury yields higher, which historically weighs on emerging market equity and debt flows. In India, while strong domestic growth metrics are positive for corporate earnings and local equities, macro headwinds from a strengthening dollar and rising US yields could cap immediate upside. Furthermore, the pick-up in input prices across both geographies signals that inflation is not yet fully tamed, complicating the policy paths for both the Reserve Bank of India and the Federal Reserve.

Trading Signals

Market Bias: Neutral

Strong economic growth is positive for corporate earnings, but the massive beats in US PMI data (manufacturing at 57.0 and services at 58.7) lift the threat of a hawkish Fed. Yields are rising, which neutralizes the positive impact of India’s services rebound to 55.8.

Overweight: Information Technology, Capital Goods, Industrial Manufacturing

Underweight: Real Estate, Financials, Utilities

Trigger Factors:

  • US Federal Reserve monetary policy commentary and interest rate decisions.
  • Movement of the US 10-year Treasury yield and the US Dollar Index (DXY).
  • Final release of the September PMI data to confirm preliminary flash trends.
  • Crude oil price trends and their impact on imported inflation in India.

Time Horizon: Near-term (0-3 months)

Industry Context

The purchasing managers’ index (PMI) is a key leading indicator of macroeconomic health. In August, India’s services activity had slowed to a 54.1 reading—one of its lowest points in four years—as service providers faced intense competition and softer client interest. However, the September flash recovery to 55.8 points to a solid rebound in new orders and business activity. In the US, the manufacturing sector has been pulling out of a prolonged period of contraction, and the jump to 57.0 in September indicates robust inventory re-stocking and an acceleration in job creation.

Key Risks to Watch

  • Resurgent inflationary pressures driven by rising fuel, transport, and operating costs in both India and the US.
  • Hawkish Federal Reserve policy shifts, which could lead to further capital outflows from emerging markets like India.
  • Friction in global supply chains, with suppliers’ delivery times lengthening due to ongoing geopolitical uncertainties, particularly in the Middle East.

Recent Developments

In August 2026, India’s services PMI stood at a downwardly revised 54.1, while the manufacturing PMI fell to a near five-year low of 52.8. At the same time, the US manufacturing PMI had settled at 53.9 in August, reflecting moderate expansion before the sharp rebound observed in the September flash estimates.

Closing Insight

The September flash PMI numbers present a classic double-edged sword: exceptional economic expansion that confirms corporate resilience, but with the immediate drawback of sticky cost inflation and higher interest rate risks. Investors should focus on high-quality, margin-resilient sectors that can withstand higher borrowing costs while capitalizing on strong underlying demand.

High Performance Trading with SAHI.

Free Training

Source link