Global Tier-1 YFORE launches U.S. manufacturing factory in Atlanta


SUWANEE, Ga., Aug. 27, 2026 /PRNewswire/ — YFORE officially inaugurated its new 62,225 sq. ft. American Headquarters in Suwanee, Georgia. Integrating R&D, manufacturing, procurement, sales, and delivery, the facility brings resilient supply chains directly to local automotive partners.

Rooted Locally, Empowering Global Mobility

This image opens in the lightbox

Local officials, global OEM partners, and supply chain leaders joined YFORE Technology to celebrate this strategic milestone.

“Becoming the trusted partner for intelligent vehicle clients is YFORE’s core mission, and our Georgia facility brings that commitment to life,” said Leo Liu, CEO of YFORE. “Driven by rising OEM demand for localized, resilient supply chains, this investment embodies our ‘Global Footprint, Local Excellence’ strategy. By pairing global scale with dedicated on-site teams, we deliver agile co-development and responsive delivery close to our customers.”

Alex Warner, President of the Forsyth County Chamber, welcomed the investment and its contribution to regional growth: “Today is not just an opening—it’s YFORE becoming part of the Forsyth County family.”

First US-Made Digital Key Rollout & Tech Showcase

  • Intelligent Mirror: Leveraging its pioneer standing in digital vision and proven mass production on 60+ vehicle models globally, YFORE showcased Interior Digital Mirrors, Auto-Dimming Mirrors, and Exterior Side Mirrors. Its Multifunctional Digital Mirror made its global debut, integrating DMS/OMS sensing and intelligent interactions into a centralized hub for simplified wiring, optimized overhead space, and full-domain perception.
  • Intelligent Access: With mass production across 50+ global models, YFORE provides a “Car-Cloud-Phone/Watch” digital key solution supporting BLE, UWB, and NFC across intelligent devices, KeyFobs. Door handle sensors and an anti-pinch system completes an end-to-end smart vehicle entry ecosystem.
  • Intelligent Sensing: Making its global debut, YFORE’s ODMS In-Cabin Full-Coverage Sensing System fuses smart mirror optics with radar sensing for full-cabin precision monitoring and E-NCAP compliance. Advanced UWB multi-function convergence enables kick sensors, low-power sentry mode, and in-cabin life detection without extra hardware.

Guests toured the SMT and automated digital key production lines and experienced YFORE’s products firsthand.

As automakers demand greater supply chain agility, YFORE is strengthening its local presence worldwide. With resilient local service, YFORE is committed to building an open, collaborative ecosystem with automotive partners worldwide.

About YFORE

YFORE is a global Tier 1 automotive electronics supplier dedicated to driving the future of intelligent mobility. Partnering with more than 30 leading automotive OEMs worldwide, YFORE delivers high-performance, automotive-grade solutions across Intelligent Access, Intelligent Mirror and Sensing systems.

Free Training

Source link

Graphene Manufacturing (TSXV: GMG) (OTCQX: GMGMF) New G FLUID™ Technology Targets AI Data Center


Graphene Manufacturing (TSXV: GMG) (OTCQX: GMGMF) New G FLUID™ Technology Targets AI Data Center

August 25, 2026 – Graphene Manufacturing Group Ltd. (TSXV: GMG) (OTCQX: GMGMF) is expanding its commercial graphene portfolio into the rapidly growing AI data center cooling and high-density computing infrastructure market with the launch of G FLUID™, a graphene-enhanced water coolant additive designed for closed-loop cooling systems.

G FLUID™ is added directly to existing water-based coolant and is designed to help transfer heat away from equipment more efficiently. In preliminary internal testing reported by GMG, adding G FLUID™ to demineralized water at a 1% dose—with graphene representing approximately 0.01% of the final solution by weight—produced an approximately 20% increase in heat-transfer rate.

AI Data Centers Create a Potential New Growth Market

The timing could be significant. The continued expansion of artificial intelligence, GPU computing, cloud infrastructure, hyperscale data centers and high-performance computing (HPC) is creating unprecedented demand for electricity and increasingly sophisticated data center thermal management and liquid cooling technologies.

GMG is initially targeting power-intensive data centers but sees potential applications across industrial process chillers, manufacturing facilities and commercial HVAC systems. The company cites a global cooling-water treatment chemicals market valued at approximately US$15 billion annually in 2026, projected to reach US$27.2 billion by 2035.

G FLUID™ has also demonstrated up to 87% antimicrobial testing outcomes in independent third-party laboratory testing conducted under EN 1276, adding another potential performance characteristic for closed-loop cooling applications.

Watch the G FLUID™ video now: https://youtu.be/_uAGHFaKQQQ

Alongside Graphene Manufacturing Group Ltd. (TSXV: GMG) (OTCQX: GMGMF), investors are also watching actively traded stocks including Sphere 3D Corp. (NASDAQ: ANY), Expion360 Inc. (NASDAQ: XPON), HIVE Digital Technologies Ltd. (TSX: HIVE) (NASDAQ: HIVE), and Keel Infrastructure Corp. (NASDAQ: KEEL) (TSX: KEEL), as small-cap and emerging growth stocks tied to data centers, energy storage, digital infrastructure and power technologies continue attracting market attention.

U.S. Manufacturing Could Become Another Catalyst

GMG has also submitted an amended application to the U.S. Environmental Protection Agency (EPA) seeking authorization to manufacture graphene and its THERMAL-XR®, G® LUBRICANT and G FLUID™ products in the United States, in addition to existing sales permissions.

GMG expects a decision on the amendment by the end of September 2027. Importantly, the company says its existing Consent Order conditions covering THERMAL-XR® sales into the United States remain unaffected.

Approval could eventually provide GMG with greater flexibility to establish U.S.-based graphene manufacturing and supply-chain capabilities closer to customers across the data center, HVAC, industrial and energy markets.

Why G FLUID™ Could Matter to GMG’s Future Valuation

For investors, G FLUID™ potentially adds another commercial market to a graphene platform already targeting HVAC energy efficiency, industrial cooling, oil and gas, rail transportation, lubricants and next-generation batteries.

If independent testing, customer trials and commercialization ultimately demonstrate meaningful energy savings at scale, G FLUID™ could give GMG exposure to the massive investment underway in AI data centers, liquid cooling, GPU infrastructure and energy-efficient computing. That could broaden the company’s addressable market and potentially support recurring product revenue as coolant is deployed and maintained across cooling systems.

The development complements GMG’s recent commercial progress, including its Gen 2.0 Graphene Manufacturing Plant, record sales orders, THERMAL-XR® commercialization, global industrial partnerships, and development of its Graphene Aluminum-Ion Battery technology.

These milestones do not guarantee a higher GMG/GMGMF share price. However, successful commercialization of G FLUID™, validation with major data center customers, U.S. regulatory progress and scalable graphene manufacturing could provide investors with additional metrics for valuing GMG beyond its existing advanced-materials business.

As global spending accelerates across AI infrastructure, data center cooling, advanced materials, clean technology and energy efficiency, G FLUID™ gives Graphene Manufacturing Group another potentially significant pathway to convert its proprietary graphene technology into commercial revenue.

About Graphene Manufacturing Group Ltd.

Graphene Manufacturing Group Ltd. (TSXV: GMG) (OTCQX: GMGMF) is an Australian clean-technology company that manufactures graphene in-house and develops graphene-enhanced solutions for energy efficiency, thermal management, industrial applications and next-generation energy storage. GMG’s portfolio includes graphene coatings, lubricants, data center cooling technologies, battery materials and advanced graphene battery development.

About The Street Reports

The Street Reports (TSR) is a financial media and reader awareness platform focused on emerging-growth, small-cap, micro-cap and nano-cap companies. The Street Reports publishes and distributes market-focused content across financial news, media and digital channels, providing companies with expanded visibility and exposure to a broad audience of readers and market participants.

Disclaimers: The Private Securities Litigation Reform Act of 1995 provides investors with a safe harbor with regard to forward-looking statements. Any statements that express or involve discussions with respect to predictions, expectations, beliefs, plans, projections, assumptions, objectives, goals, and assumptions about future events or performance are not statements of historical fact and may be forward looking statements. Forward looking statements are based on expectations, estimates, and projections at the time the statements are made that involve a number of risks and uncertainties that could cause actual results or events to differ materially from those presently anticipated. Forward looking statements in this action may be identified through use of words such as projects, foresee, expects, will, anticipates, estimates, believes, understands, or that by statements, indicating certain actions & quotes; may, could or might occur Understand there is no guarantee past performance is indicative of future results. Investing in micro-cap or growth securities is highly speculative and carries an extremely high degree of risk. It is possible that an investor’s investment may be lost or due to the speculative nature of the companies profiled. TheStreetReports (TSR) is responsible for the production and distribution of this content.”TSR” is not operated by a licensed broker, a dealer, or a registered investment advisor. It should be expressly understood that under no circumstances does any information published herein represent a recommendation to buy or sell a security. “TSR” authors, contributors, or its agents, may be compensated for preparing research, video graphics, podcasts and editorial content. “TSR” has not been compensated to produce content related to “Any Companies” appearing herein. As part of that content, readers, subscribers, and everyone viewing this content are expected to read the full disclaimer in our website.

Media Contact
Company Name: The Street Reports
Contact Person: Editor
Email: Send Email
Country: United States
Website: http://www.thestreetreports.com


Free Training

Source link

Company that makes equipment for computer chip manufacturing commits $1.5B in Tualatin, breaks ground on new lab


FILE - The inside of a computer is seen on Feb 23, 2019, in Jersey City, N.J. A global computer chip shortage has made it harder for consumers to get their hands on cars, computers and other modern-day necessities, so Congress is looking to boost chip manufacturing and research in the United States with billions of dollars from the federal government.

FILE – The inside of a computer is seen on Feb 23, 2019, in Jersey City, N.J. A global computer chip shortage has made it harder for consumers to get their hands on cars, computers and other modern-day necessities, so Congress is looking to boost chip manufacturing and research in the United States with billions of dollars from the federal government.

Jenny Kane / AP

A company vital in designing and building equipment for the world’s largest computer chip firms broke ground on a $620 million research and development lab in Tualatin Wednesday.

Overall, Lam Research will spend $1.5 billion on major research and development laboratories in Washington County over the next decade and half.

It’s part of a global expansion of the semiconductor equipment firm’s network of labs. Lam Research plans to pump $3 billion into operations in the U.S., as well as in Asia and Europe.

“In the AI era, the pace of innovation is relentless, requiring chips with new architectures, different materials, and complex features engineered with nanoscale precision,” Lam Research CEO Tim Archer said in a written statement earlier this month about the $3 billion global investment. “Our ability to increase velocity throughout the research and development process has become a decisive advantage.”

Wednesday’s groundbreaking comes at a precarious time for the state’s manufacturing sector, which includes semiconductor manufacturing. The sector has been shedding jobs as companies consolidate. Oregon has lost nearly 8,500 manufacturing jobs over the last year, according to state employment data.

Those losses include nearly 2,500 layoffs last summer at major chipmaker Intel, the state’s largest private employer. Lam Research designs and builds tools for Intel and other major semiconductor companies, like Micron.

Lam Research's groundbreaking ceremony on its new research & development lab in Tualatin, Oregon. The facility is expected to create 400 jobs at the semiconductor equipment company.

Lam Research’s groundbreaking ceremony on its new research & development lab in Tualatin, Oregon. The facility is expected to create 400 jobs at the semiconductor equipment company.

Kyra Buckley / OPB

The job losses come despite soaring demand for computer chips due to advancement in the use of artificial intelligence. Intel, which acts as an anchor company for Oregon’s industry that’s mainly concentrated in Washington County, is playing catch-up to other companies when it comes to AI.

But recent partnerships now have Intel providing chips for data centers, needed to keep the AI industry running. Experts say that won’t necessarily translate into big jobs gains for Oregon’s technology manufacturing sector. However, it does raise confidence for equipment companies like Lam Research that their products will be in demand for the foreseeable future.

Lam currently employs around 3,000 people, mostly at its campus in Tualatin. Once constructed, the new 120,000 square foot facility is expected to add another 400 jobs to the company’s headcount. Under a multi-year deal with Washington County, the new building qualifies for property tax breaks and Lam will pay an estimated $111 million in taxes and fees over the life of the agreement.

“Our new advanced Oregon lab is expected to deepen our specialized capabilities and add tens of thousands of square feet of valuable cleanroom space,” Sesha Varadarajan, Lam’s chief operating officer, said in written statement about Wednesday’s groundbreaking, “enabling even closer collaboration with customers while strengthening the expertise and reach of our global lab network.”

Free Training

Source link

US Manufacturing Boom Favors 167 High-Conviction Hubs


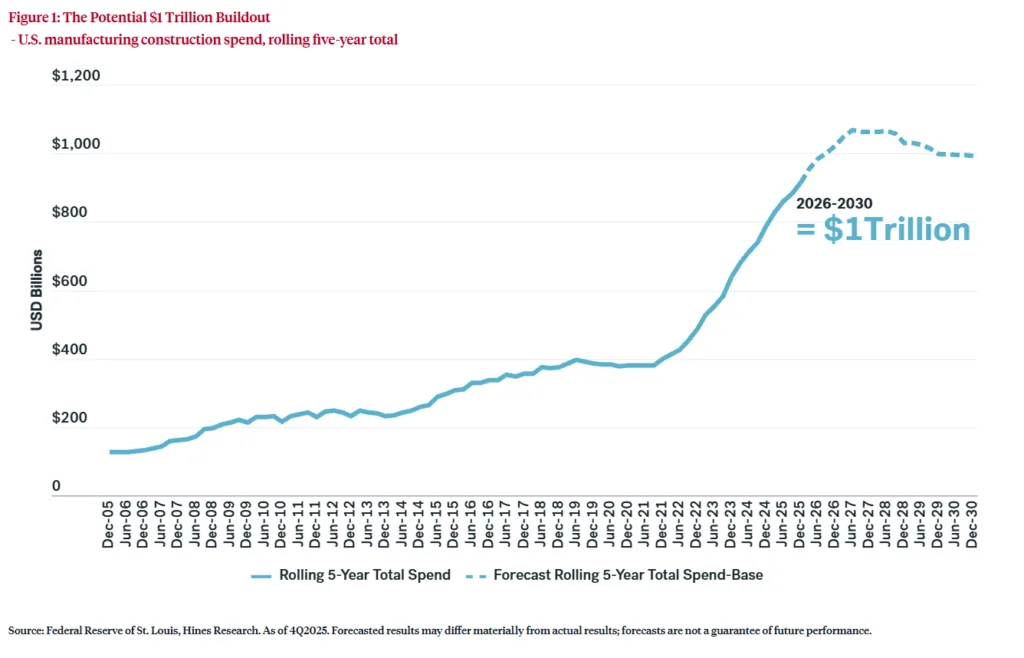
  • US manufacturing construction spending may reach $1 trillion from 2026–2030, with growth concentrated in select industrial submarkets.
  • Advanced manufacturing and ‘New Companies Doing New Things’ are driving leasing demand in regional hubs such as Dallas–Fort Worth, Houston, Phoenix, Atlanta, Chicago, and San Jose.
  • A Hines study identified just 167 ‘high-conviction’ submarkets out of 1,500 nationwide as best positioned to convert manufacturing investment into sustained rent and demand growth.

Key Takeaways

Rise of the Advanced Manufacturing Ecosystem

The US manufacturing surge is sharpening investor focus on a small group of emerging and established industrial hubs. According to Hines Research, manufacturing construction spending could reach roughly $1 trillion between 2026 and 2030. Cyclical rebounds will contribute, alongside a structural shift toward advanced manufacturing.

Hines analyzed about 1,500 submarkets and found that outperformance remains highly concentrated. Winning markets have deep industrial ecosystems or supply constraints that strengthen tenant demand and rent growth. Wholesale reshoring remains limited, but federal incentives and supply chain resilience continue driving capital into US manufacturing. These forces reinforce regional clusters and attract industrial occupiers seeking capacity for next-generation production.

US manufacturing construction spending is projected to reach a rolling five-year total of roughly $1 trillion from 2026 through 2030.

The Details

Hines Research applied its proprietary Manufacturing Market Growth Score (MMGS) across submarkets in 75 US metros. The score weighs manufacturing stock at 48% and five-year manufacturing employment growth at 47%. Current manufacturing workforce size accounts for the remaining 5%. Only 167 submarkets, or roughly 12%, scored above 70, highlighting concentrated investment opportunities.

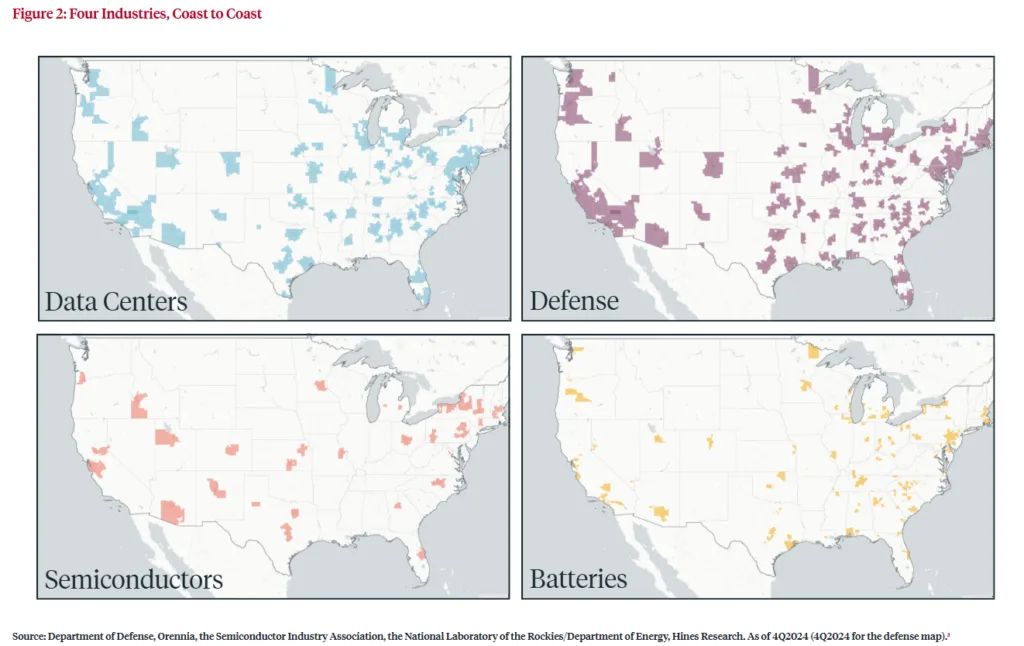
Dallas–Fort Worth leads as a logistics and defense hub, while Houston stands out in energy and petrochemicals. Phoenix and San Jose excel in semiconductors. Data centers also attract logistics companies and advanced component providers, despite falling outside traditional manufacturing. Meanwhile, battery hubs stretch from the Great Lakes through Tennessee and the Southeast. Many overlap with Opportunity Zones, adding another consideration for tax-sensitive capital.

US map showing geographic clusters for data centers, defense, semiconductor, and battery industries across major manufacturing markets.

Concentration, Not Uniformity, Defines Growth

Despite the $1 trillion forecast, Hines found that capital and tenant demand remain tightly clustered. Of 167 high-conviction submarkets, 162 have significant defense and data center footprints. Those sectors now function as industrial table stakes rather than meaningful differentiators. Semiconductor and battery clusters remain more selective. Battery activity concentrates across 54 submarkets that also qualify as Opportunity Zones.

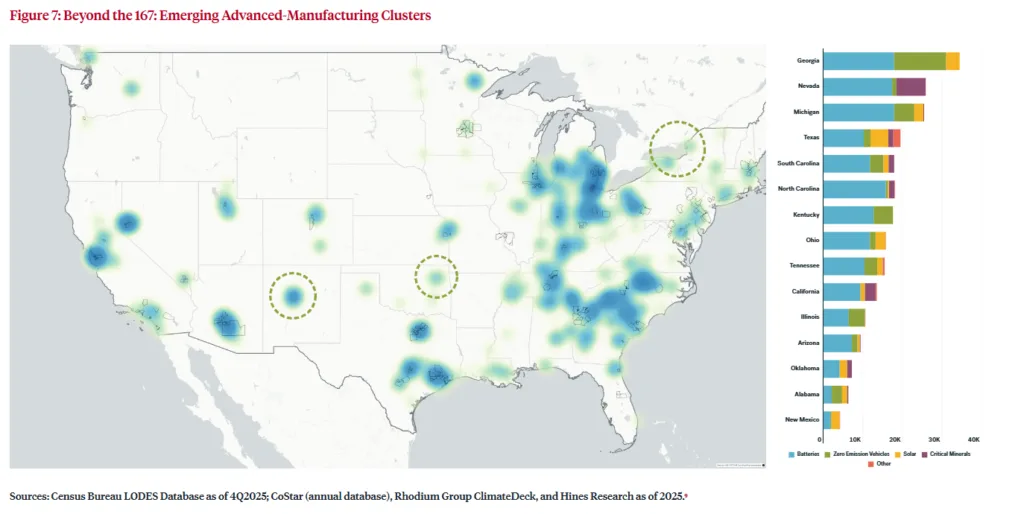
Spillover activity is emerging along the Great Lakes-Tennessee corridor and in upstate New York, Tulsa, and New Mexico. These markets offer lower-cost alternatives for manufacturers seeking available land and power outside highly competitive metros. Recent shifts in Austin battery facility plans also show how quickly manufacturers can adjust investment and production strategies. Data centers follow different site-selection patterns, favoring power-rich markets like West Texas and Iowa. That trend creates parallel industrial demand across regions with limited historical manufacturing density.

US map showing emerging advanced manufacturing clusters, with battery-related employment concentrated across the Southeast, Midwest, and selected Western markets.

Why It Matters

Investors must determine which markets can translate manufacturing investment into durable rent and demand growth. Hines analyzed Census Bureau and CoStar data through 2025 to measure historical performance. Top-scoring submarkets recorded stronger five-year rent growth and occupied SF gains than lower-scoring peers. The demand gap proved especially significant. Highest-scoring markets gained occupied space, while the bottom quartile recorded net declines.

Institutional capital can gain more by targeting established ecosystems than broadly chasing the manufacturing boom. Scale, infrastructure, and supply chain depth create a virtuous cycle that supports additional investment. Supply constraints can amplify rent growth in tight clusters. New industrial nodes offer potential upside but carry greater oversupply risk. Opportunity Zones can further improve risk-adjusted returns for tax-sensitive investors near battery and semiconductor clusters.

The advanced manufacturing buildout also changes CRE demand fundamentals. Companies and government entities increasingly prioritize supply chain resilience alongside operating efficiency. Large projects can create self-reinforcing hubs of investment, skilled labor, and supplier networks. This agglomeration effect expands demand beyond manufacturers to logistics, infrastructure, and component businesses. In turn, those supporting industries strengthen the competitive advantages of leading submarkets.

What’s Next

Federal policy and private capital could sustain the manufacturing expansion and intensify investor focus on Hines’ 167 high-conviction submarkets. Developers will likely pursue emerging corridors with affordable land and sufficient grid capacity. Areas near new data centers and battery plants could attract particularly strong interest.

However, investors must carefully manage exposure in tertiary markets. Rapid construction could outpace tenant absorption and weaken rent growth. The strongest markets will combine supply constraints, established industrial ecosystems, and infrastructure capable of supporting additional investment. Those fundamentals offer the clearest path for converting the $1 trillion manufacturing boom into durable CRE returns.

Free Training

Source link

Edge Aerospace expands U.S. manufacturing through licensing pact with Redwire


SALT LAKE CITY – Redwire will manufacture data processing units and network switches under a licensing agreement with Luxembourg-based Edge Aerospace, the companies announced Aug. 25 at the Small Satellite Conference.

“This agreement represents an important step in our long-term strategy to make advanced space computing more accessible to customers in the United States,” Edge Aerospace CEO Jarosław Jaworski said in the news release. “Redwire has earned a reputation as one of the industry’s most trusted providers of flight-proven space infrastructure. By combining Edge’s high-performance computing technology with Redwire’s manufacturing expertise and customer reach, we can deliver domestically manufactured computing systems that meet the growing demand for intelligent spacecraft capable of processing more data at the edge.”

Through the agreement, Edge Aerospace seeks to accelerate delivery of space-qualified computing products while increasing supply chain resilience and broadening support for its growing U.S. customer base, according to the news release.

“Redwire is proud to leverage our trusted domestic manufacturing expertise and strong customer base to support Edge Aerospace,” Don Wesson, Redwire senior vice president for defense technology and general manager of Redwire’s Marlborough, Massachusetts, facility. “Redwire is committed to manufacturing and delivering reliable, American-made, flight-qualified technology to customers who need mission-ready capabilities.”

Debra Werner is a correspondent for SpaceNews based in San Francisco.

Debra earned a bachelor’s degree in communications from the University of California, Berkeley, and a master’s degree in Journalism from Northwestern University. She is a recipient…

Free Training

Source link

Vicente Torns announces first U.S. manufacturing facility – Peak of Ohio


A major economic development announcement has been made in West Liberty after months of work at the local and state levels.

Spanish manufacturer Vicente Torns has announced plans to establish its first U.S. operation in Logan County, bringing new investment and job opportunities to the community.

The project is also receiving support from the state through a Job Creation Tax Credit.

Vicente Torns is among 13 projects approved by the Ohio Tax Credit Authority, with the statewide projects expected to create more than 3,500 new jobs and bring more than $1.1 billion in investment.

The company is expected to create 108 full-time jobs, generating more than $7.1 million in new annual payroll by the end of 2030.

Vicente Torns is a third-generation, family-owned company with more than 100 years of operating history.

The company manufactures copper and aluminum cables and wires used in the energy, automotive, and transportation industries.

As part of the project, Vicente Torns plans to acquire an existing building in West Liberty, renovate and expand it, and add new equipment.

The expansion will allow the company to manufacture conductors used in electric transformers.

The Ohio Tax Credit Authority approved a 1.427-percent, eight-year Job Creation Tax Credit for the project.

Governor Mike DeWine, Lieutenant Governor Jim Tressel and Ohio Department of Development Director Lydia Mihalik announced the approvals Monday.

Statewide, the 13 projects are expected to create 3,553 new jobs, retain another 907 jobs, and generate nearly $310 million in new payroll.

The projects span several industries, including manufacturing, aerospace, defense, technology, and engineering.

Here are the details in the official announcement:

“Vicente Torns Ohio Corp., an international manufacturer of copper and aluminum cables and wires, will establish its first U.S. manufacturing facility in West Liberty. The company will invest $21 million at 600 N. Detroit St. and create 108 new jobs representing $7.1 million in new annual payroll.

The West Liberty operation will produce copper and aluminum wires used in electric transformers. The project will establish a U.S. manufacturing base for Vicente Torns as the company expands its presence in North America and serves growing demand from the energy industry.

“Establishing our first manufacturing operation in the United States marks an important step in the continued growth of Vicente Torns. Within four years, we expect the U.S. market to account for 15 percent of the group’s total revenue,” said Vicente Torns, CEO of Vicente Torns. “West Liberty provides a strong foundation to serve our customers, build a skilled local workforce and expand our production capabilities in North America. We appreciate the partnership and support that helped bring this investment to the Columbus Region.”

With more than 100 years of manufacturing experience, Vicente Torns operates facilities in Spain, Slovakia, Italy, Morocco, India and France. The company serves customers across different sectors, especially is energy, particularly transformers, high-voltage motors, and generators, and, to a lesser extent, electric vehicles and railways.

“Vicente Torns’ decision to establish its first U.S. manufacturing facility in West Liberty is a major vote of confidence in our community and our workforce,” said West Liberty Mayor Brad Hudson. “This investment will create more than 100 jobs and bring a respected international manufacturer with more than a century of experience to Logan County. We look forward to supporting the company’s success here.”

Pending local approval, the project represents a significant foreign direct investment in the Columbus Region and adds to the Region’s growing base of international manufacturers. Vicente Torns’ selection of West Liberty also creates new manufacturing capacity supporting equipment essential to the nation’s electric infrastructure.

“The Columbus Region has become a strong entry point for global manufacturers establishing U.S. operations,” said Jonas Peterson, chief economic development officer and president of One Columbus. “Our central location provides efficient access to major North American markets. Our manufacturing base connects companies with experienced workers and established industrial partners. Communities such as West Liberty offer the capacity and support needed for long-term growth. Vicente Torns’ decision reflects the strength of that regional proposition.”

Vicente Torns selected Logan County for its first U.S. manufacturing operation as rising energy demand drives greater need for the copper and aluminum wire used in electric transformers. The decision reflects the strength of the area’s manufacturing workforce and the Columbus Region’s strategic access to customers across North America.

“Ohio continues to win global manufacturers because we deliver what they actually need: access to customers, resilient supply chains, and the ability to scale fast from the center of the North American market,” said JobsOhio President and CEO J.P. Nauseef. “Vicente Torns’ investment is proof our strategy to attract global companies critical to the nation’s energy infrastructure is working.”

Free Training

Source link

Secretary of War Pete Hegseth Visits Oshkosh Corporation, Highlighting the Strength of American Manufacturing and the Arsenal of Freedom | News


State

AlabamaAlaskaArizonaArkansasCaliforniaColoradoConnecticutDelawareFloridaGeorgiaHawaiiIdahoIllinoisIndianaIowaKansasKentuckyLouisianaMaineMarylandMassachusettsMichiganMinnesotaMississippiMissouriMontanaNebraskaNevadaNew HampshireNew JerseyNew MexicoNew YorkNorth CarolinaNorth DakotaOhioOklahomaOregonPennsylvaniaRhode IslandSouth CarolinaSouth DakotaTennesseeTexasUtahVermontVirginiaWashingtonWashington D.C.West VirginiaWisconsinWyomingPuerto RicoUS Virgin IslandsArmed Forces AmericasArmed Forces PacificArmed Forces EuropeNorthern Mariana IslandsMarshall IslandsAmerican SamoaFederated States of MicronesiaGuamPalauAlberta, CanadaBritish Columbia, CanadaManitoba, CanadaNew Brunswick, CanadaNewfoundland, CanadaNova Scotia, CanadaNorthwest Territories, CanadaNunavut, CanadaOntario, CanadaPrince Edward Island, CanadaQuebec, CanadaSaskatchewan, CanadaYukon Territory, Canada

Zip Code

Country

United States of AmericaUS Virgin IslandsUnited States Minor Outlying IslandsCanadaMexico, United Mexican StatesBahamas, Commonwealth of theCuba, Republic ofDominican RepublicHaiti, Republic ofJamaicaAfghanistanAlbania, People’s Socialist Republic ofAlgeria, People’s Democratic Republic ofAmerican SamoaAndorra, Principality ofAngola, Republic ofAnguillaAntarctica (the territory South of 60 deg S)Antigua and BarbudaArgentina, Argentine RepublicArmeniaArubaAustralia, Commonwealth ofAustria, Republic ofAzerbaijan, Republic ofBahrain, Kingdom ofBangladesh, People’s Republic ofBarbadosBelarusBelgium, Kingdom ofBelizeBenin, People’s Republic ofBermudaBhutan, Kingdom ofBolivia, Republic ofBosnia and HerzegovinaBotswana, Republic ofBouvet Island (Bouvetoya)Brazil, Federative Republic ofBritish Indian Ocean Territory (Chagos Archipelago)British Virgin IslandsBrunei DarussalamBulgaria, People’s Republic ofBurkina FasoBurundi, Republic ofCambodia, Kingdom ofCameroon, United Republic ofCape Verde, Republic ofCayman IslandsCentral African RepublicChad, Republic ofChile, Republic ofChina, People’s Republic ofChristmas IslandCocos (Keeling) IslandsColombia, Republic ofComoros, Union of theCongo, Democratic Republic ofCongo, People’s Republic ofCook IslandsCosta Rica, Republic ofCote D’Ivoire, Ivory Coast, Republic of theCyprus, Republic ofCzech RepublicDenmark, Kingdom ofDjibouti, Republic ofDominica, Commonwealth ofEcuador, Republic ofEgypt, Arab Republic ofEl Salvador, Republic ofEquatorial Guinea, Republic ofEritreaEstoniaEthiopiaFaeroe IslandsFalkland Islands (Malvinas)Fiji, Republic of the Fiji IslandsFinland, Republic ofFrance, French RepublicFrench GuianaFrench PolynesiaFrench Southern TerritoriesGabon, Gabonese RepublicGambia, Republic of theGeorgiaGermanyGhana, Republic ofGibraltarGreece, Hellenic RepublicGreenlandGrenadaGuadaloupeGuamGuatemala, Republic ofGuinea, Revolutionary
People’s Rep’c ofGuinea-Bissau, Republic ofGuyana, Republic ofHeard and McDonald IslandsHoly See (Vatican City State)Honduras, Republic ofHong Kong, Special Administrative Region of ChinaHrvatska (Croatia)Hungary, Hungarian People’s RepublicIceland, Republic ofIndia, Republic ofIndonesia, Republic ofIran, Islamic Republic ofIraq, Republic ofIrelandIsrael, State ofItaly, Italian RepublicJapanJordan, Hashemite Kingdom ofKazakhstan, Republic ofKenya, Republic ofKiribati, Republic ofKorea, Democratic People’s Republic ofKorea, Republic ofKuwait, State ofKyrgyz RepublicLao People’s Democratic RepublicLatviaLebanon, Lebanese RepublicLesotho, Kingdom ofLiberia, Republic ofLibyan Arab JamahiriyaLiechtenstein, Principality ofLithuaniaLuxembourg, Grand Duchy ofMacao, Special Administrative Region of ChinaMacedonia, the former Yugoslav Republic ofMadagascar, Republic ofMalawi, Republic ofMalaysiaMaldives, Republic ofMali, Republic ofMalta, Republic ofMarshall IslandsMartiniqueMauritania, Islamic Republic ofMauritiusMayotteMicronesia, Federated States ofMoldova, Republic ofMonaco, Principality ofMongolia, Mongolian People’s RepublicMontserratMorocco, Kingdom ofMozambique, People’s Republic ofMyanmarNamibiaNauru, Republic ofNepal, Kingdom ofNetherlands AntillesNetherlands, Kingdom of theNew CaledoniaNew ZealandNicaragua, Republic ofNiger, Republic of theNigeria, Federal Republic ofNiue, Republic ofNorfolk IslandNorthern Mariana IslandsNorway, Kingdom ofOman, Sultanate ofPakistan, Islamic Republic ofPalauPalestinian Territory, OccupiedPanama, Republic ofPapua New GuineaParaguay, Republic ofPeru, Republic ofPhilippines, Republic of thePitcairn IslandPoland, Polish People’s RepublicPortugal, Portuguese RepublicPuerto RicoQatar, State ofReunionRomania, Socialist Republic ofRussian FederationRwanda, Rwandese RepublicSamoa, Independent State ofSan Marino, Republic ofSao Tome and Principe, Democratic Republic ofSaudi Arabia, Kingdom ofSenegal, Republic ofSerbia and MontenegroSeychelles, Republic ofSierra Leone, Republic ofSingapore, Republic ofSlovakia (Slovak Republic)SloveniaSolomon IslandsSomalia, Somali RepublicSouth Africa, Republic ofSouth Georgia and the South Sandwich IslandsSpain, Spanish StateSri Lanka, Democratic Socialist Republic ofSt. HelenaSt. Kitts and NevisSt. LuciaSt. Pierre and MiquelonSt. Vincent and the GrenadinesSudan, Democratic Republic of theSuriname, Republic ofSvalbard & Jan Mayen IslandsSwaziland, Kingdom ofSweden, Kingdom ofSwitzerland, Swiss ConfederationSyrian Arab RepublicTaiwan, Province of ChinaTajikistanTanzania, United Republic ofThailand, Kingdom ofTimor-Leste, Democratic Republic ofTogo, Togolese RepublicTokelau (Tokelau Islands)Tonga, Kingdom ofTrinidad and Tobago, Republic ofTunisia, Republic ofTurkey, Republic ofTurkmenistanTurks and Caicos IslandsTuvaluUganda, Republic ofUkraineUnited Arab EmiratesUnited Kingdom of Great Britain & N. IrelandUruguay, Eastern Republic ofUzbekistanVanuatuVenezuela, Bolivarian Republic ofViet Nam, Socialist Republic ofWallis and Futuna IslandsWestern SaharaYemenZambia, Republic ofZimbabwe

Free Training

Source link

Roche Invests $750m to Double US Manufacturing Plant


Roche is far from alone

Roche’s spending sits within a much wider surge of pharmaceutical reshoring across the United States, a trend accelerated by the threat of tariffs on medicines manufactured overseas under President Donald Trump. Rival drugmakers have announced comparably enormous sums in recent months. Novartis has committed $23bn to building or expanding ten US facilities. Johnson & Johnson has pledged $55bn toward domestic manufacturing, including three entirely new sites, while Eli Lilly is midway through a $27bn investment programme covering four additional plants.

Bristol Myers Squibb has made a similar move, unveiling a $2.3bn “multi-modal manufacturing campus” in Houston, Texas, as part of a broader $40bn, five-year plan covering US research, technology and manufacturing. “This investment reflects our confidence in America’s continued leadership in biopharmaceutical innovation,” said BMS Board Chair and CEO Christopher Boerner. “As part of our $40bn commitment to the United States, we’re building the domestic manufacturing capabilities needed to deliver the next generation of medicines and support future scientific breakthroughs. Houston and the state of Texas offer the talent, infrastructure, and partnership needed to help bring that vision to life.”

Free Training

Source link

3 U.S. Manufacturing Stocks Tied To Tariff Driven Onshoring】【。


With a fresh US–Canada trade clash pushing tariffs higher and rattling cross border supply chains, investors face a new map of potential winners and losers. Sudden shifts in costs and sourcing can reshape where production happens and which companies keep pricing power. This article walks through three stocks from our U.S. Onshoring and Domestic Manufacturing Beneficiaries screener that appear well positioned for this moment.

The stocks highlighted below are just a starting sample, and the full screen surfaced 7 more companies with equally detailed domestic manufacturing narratives that are not covered here. If you want to move beyond the short list and start sizing up reshoring beneficiaries for yourself, head straight into the U.S. Onshoring and Domestic Manufacturing Beneficiaries screener to identify, filter and analyze the setups that best fit your own conviction.

SunCoke Energy (SXC)

SunCoke Energy is a coke producer tightly linked to U.S. steelmaking, which puts it squarely in the onshoring and domestic manufacturing story as tariffs push buyers toward tariff-insulated inputs. The business is heavily weighted to Domestic Coke, which generated about US$1.5b of revenue, with Industrial Services adding roughly US$356 million and smaller contributions from Corporate and Other and intersegment eliminations. With a market cap of about US$822 million, SunCoke Energy is a mid-cap stock that gives investors focused exposure to the U.S. steel supply chain rather than a broad metals basket.

For investors looking at how a prolonged US-Canada trade clash could reshape North American steel supply chains, SunCoke Energy offers a direct way to study those shifts. The company supplies coke and logistics services that support domestic blast furnaces, and it has been expanding into industrial services that can help smooth revenue. At the same time, it carries meaningful leverage, relies on a handful of large steel customers and pays a dividend that has raised questions around long term cover. That combination of tariff tailwinds, earnings guidance and balance sheet and customer concentration risk is why this stock may warrant a closer look before deciding where it fits in a portfolio.

SunCoke Energy’s tariff‑shielded position in the U.S. steel chain could be more powerful than the headline story suggests, yet its leverage and customer reliance raise real questions. Get the full picture in the 3 key rewards and 2 important warning signs (2 are major!)

NYSE:SXC Revenue & Expenses Breakdown as at Aug 2026NYSE:SXC Revenue & Expenses Breakdown as at Aug 2026

Build your own tariff beneficiaries shortlist

SunCoke Energy and the two other stocks in this list all came from a single Simply Wall St screener, but the real edge comes when you shape the filters yourself. Use our flexible Screener to mix valuation, growth, balance sheet, risk and dividend filters to suit your style, or tap into our curated Investing Ideas for ready made stock shortlists.

Aebi Schmidt Holding (AEBI)

Aebi Schmidt Holding manufactures specialized vehicles and equipment for airports, municipalities, commercial fleets and agriculture, which fits the onshoring theme through its North American production footprint and focus on workhorse infrastructure gear. The company generates about US$1.4b of revenue from North America and roughly US$576 million from Europe and the rest of the world, giving it meaningful exposure to U.S. demand for domestically produced equipment. With a market cap of about US$956 million, Aebi Schmidt Holding sits in mid cap territory where individual contracts and capacity decisions can materially influence the story.

Investors watching tariff driven reshoring should have Aebi Schmidt Holding on the radar because it brings a large, visible backlog, growing North American operations and a recent beat on Q2 2026 revenue and earnings into a sector where U.S. made fleet and airport equipment may gain share. The company is working through cost inflation and relies on external borrowings, so thin margins and leverage keep execution risk on the table even as management pursues efficiency programs and integration synergies. That mix of potential earnings upside tied to higher utilization and municipal and airport demand, alongside balance sheet and profitability questions, is exactly where deeper research can matter most.

Aebi Schmidt Holding’s backlog and North American footprint could be masking a much bigger earnings story. Get the full context in the 3 key rewards and 2 important warning signs (1 is major!) and see what the latest contracts might really signal

NasdaqGS:AEBI Revenue & Expenses Breakdown as at Aug 2026NasdaqGS:AEBI Revenue & Expenses Breakdown as at Aug 2026

Meritor (MTOR)

Meritor is a long established Michigan based manufacturer of axles, brakes and driveline components for medium and heavy duty trucks, trailers, military vehicles and buses, with growing electric drive systems that tie it directly into the U.S. auto and machinery supply chain story as companies look to source more content domestically. The stock has a market cap of about US$2.6b, which puts it in a bracket where contract wins, product mix and capital allocation decisions can still meaningfully influence long term value for shareholders.

Investors watching the US–Canada trade clash and the push for more U.S. made vehicle content should have Meritor on the radar. The company supplies core hardware that truck and machinery makers struggle to swap out quickly, and it is investing in electric drive systems that align with longer term freight and bus electrification. At the same time, high leverage and limited cash flow cover for debt mean any ramp up in North American production needs to be funded carefully, which keeps execution risk front and center. The balance of improving profitability, potential for a valuation rerating and a balance sheet that demands respect is exactly why a closer look at Meritor could be time well spent.

Meritor’s shift into electric drive systems could be masking a very different earnings path. Scan the 3 key rewards and 1 important major warning sign to see how the balance sheet risk and potential upside really line up.

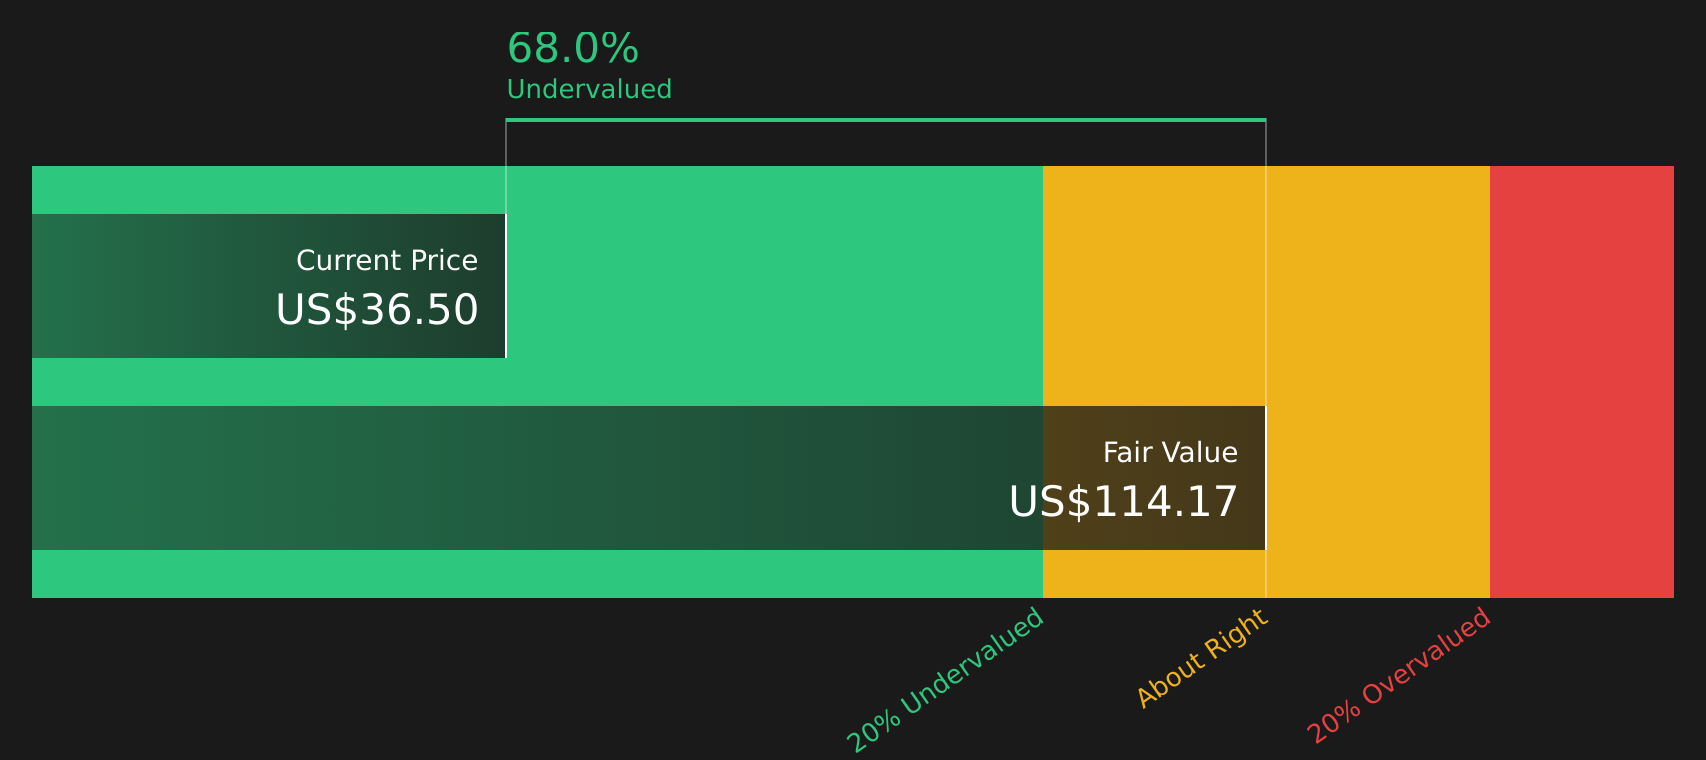
MTOR Discounted Cash Flow as at Aug 2026MTOR Discounted Cash Flow as at Aug 2026

Seeking Curiosity In Fresh Alternatives

Fresh stock ideas can move quickly when momentum builds and pricing gaps close. Consider identifying potential breakouts while they are still under the radar.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: Manage All Your Stock Portfolios in One Place

We’ve created the ultimate portfolio companion for stock investors, and it’s free.

• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks

Try a Demo Portfolio for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

To win the next war, America must give up consumer goods race against China


As we celebrate America’s 250th birthday, our pride in successfully reaching this milestone must be tempered by the challenge we face: ensuring a strong, secure, and resilient nation for the next 250 years and more. 

There is a clear, albeit difficult, path forward. First, revive, reconstitute, and reconfigure America’s manufacturing base. Second, within the confines of the U.S. sphere of influence (encompassing the homeland and the rest of the Americas), assemble and build critical supply chains with respect to the technology, energy, and food sectors that are vital to our economic and military security. Third, put in place a pragmatic fiscal framework that defuses the huge, ticking federal deficit bomb while encouraging private sector-driven, sustainable economic growth.

The foundation of U.S. military power is the size of America’s manufacturing base. Although the United States has the world’s largest economy, with GDP of $30.4 trillion as of 2025, the American manufacturing sector was only $2.9 trillion or about 9.5% of GDP. In sharp contrast, the size of China’s manufacturing sector was $4.8 trillion or about 25% of GDP of $19.5 trillion. Simply put, although the size of the U.S. economy was about 60% larger than China’s, the American manufacturing sector was only about 60% the size of China’s manufacturing sector.

IF AMERICA WON’T BUILD SAUDI ARABIA’S REACTORS, BEIJING WILL

It is unlikely that the United States will be able to close the manufacturing gap with China for the foreseeable future. 

According to the International Monetary Fund projections prepared in July 2026, the real rate of growth of the U.S. economy is expected to be 2.3% in 2026 and 2.2% in 2027. For the comparable periods, China’s real GDP growth rate is projected to be 4.6% and 4.1%. 

Assuming the US will grow at a real rate of 2.5% per annum (which is higher than the 1.8% annual real growth rate assumed by the Congressional Budget Office), then at the end of a decade, the size of the economy would be about $38.9 trillion. If the share of manufacturing increased to 15% of GDP by the end of a decade, the size of the U.S. manufacturing sector would amount to $5.8 trillion. 

Even if the Chinese economy grew at only 2.5% per annum (the same rate as the U.S. and significantly lower than IMF projections), and assuming there is no change in the share of the manufacturing sector’s share of the country’s economy, at the end of ten years the size of China’s manufacturing sector would be $6.3 trillion, which still would be larger than America’s manufacturing sector at that time.

So, the American manufacturing sector will have to shift its focus from consumer goods to military and dual-use products. Other countries within America’s sphere of influence would be key U.S. trade partners facilitating this transition, particularly for consumer goods.

Decoupling from the ecosystems of adversaries such as China and Russia is not a choice but an existential necessity. 

Manufacturing represents the end of the supply chain, but the intermediate and beginning stages are equally important for the integrity and security of the supply chain. After all, the supply chain is only as strong as its weakest link. 

Given the reality of a smaller American manufacturing base relative to China, the United States will have to have comparatively higher productivity driven by Artificial Intelligence and other technologies in order to produce more and better-quality military and dual-use goods with the same resources. 

The backbone of AI-driven productivity is the data centers ecosystem: land, water, and electric power. The United States has sufficient land and water and has the potential to significantly turbocharge its electric power-generating capacity. The key is to substantially expand the share of renewable nuclear fuel in the energy mix to support the huge demand for electric power that an AI-driven productivity revolution requires. 

The NIMBY backlash against data centers and nuclear power is a misguided, self-imposed constraint that will have to be addressed and overcome via the democratic political process, not by fiat. The national security dimensions of the AI revolution have yet to be seriously considered.

The rest of the Americas have the potential to supply the United States with key basic natural resources, critical minerals, fossil fuels, and agricultural products required to safeguard U.S. military and economic security.

Argentina, Bolivia, and Chile collectively have identified lithium reserves of about 64 million tons or about 40% of world identified reserves. Lithium is the key ingredient for rechargeable batteries that power electric vehicles – a sector dominated by China. 

Chile, Peru, and Mexico collectively have proved copper reserves of about 318 million tons or about 33% of world proved reserves. Copper is a basic building block of industry, including the electric power, transportation, communication, and construction sectors.

Venezuela has the world’s largest proved oil reserves of about 303.8 billion barrels. Canada has proved oil reserves of 170.3 billion barrels. Collectively, the two countries account for about 27% of world oil reserves.

Canada has proved potash reserves of about 1.1 billion tons or about 20% of world proved reserves. Potash is the main ingredient for fertilizers and critical for food security.

The quintet of Argentina, Brazil, Canada, Chile, and Mexico is an agricultural combine that guarantees food security within the U.S. sphere of influence and beyond. 

Of course, to regenerate the U.S. manufacturing base and unlock the potential of the other countries of the Americas to ensure robust supply chains from exploration, to development, to refining and processing will require the mobilization of a massive amount of private sector investment. 

The U.S. government cannot continue on its current trajectory to a fiscal meltdown that would destroy America’s capital markets, which have financed our nation’s economic growth. As of fiscal year-end 2025, the total federal debt of $37.6 trillion represented 124% of GDP of $30.4 trillion. According to projections prepared by the Congressional Budget Office, total federal debt held by the public will mushroom to 175% of GDP in 2056.

CHINA HAS ROCKS. WE HAVE LOBBYISTS. GUESS WHO’S WINNING THE CRITICAL MINERALS WAR?

It is within the power of Washington’s decision-makers to craft a pathway to fiscal resiliency. Instead of squandering the nation’s scarce resources to slay imaginary foreign dragons, it’s time to slay the real fiscal monster at home that is an imminent existential threat. 

We cannot betray our Founding Fathers. On our 250th anniversary, the legacy we must bequeath to future generations is a strong, secure and resilient America.

Samir Tata is the founder and president of International Political Risk Analytics, an advisory firm based in Reston, Virginia, and author of the book Reflections on Grand Strategy: The Great Powers in the Twenty-first Century.

Free Training

Source link