Tesla (TSLA) reportedly in talks to buy $2.9B in Chinese solar equipment for 100 GW US push

FERC July 2025
Image: Tesla

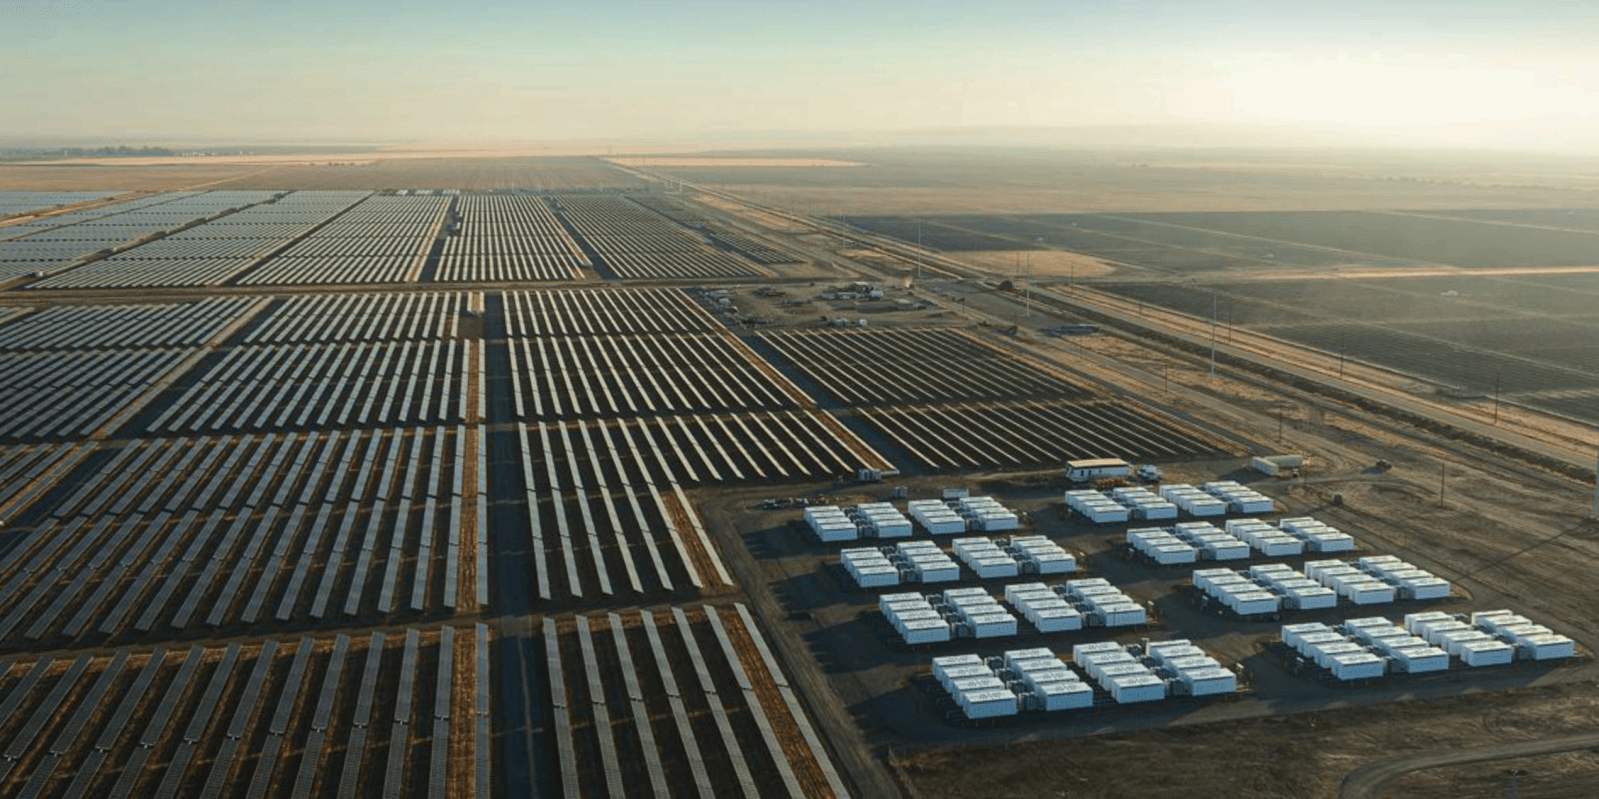
Elon Musk’s plan to build 100 GW of solar manufacturing capacity in the United States just got its first major price tag: $2.9 billion in equipment from Chinese suppliers, according to a Reuters exclusive.

If the deal closes, it marks the biggest concrete investment yet in Musk’s solar ambitions, and a stunning reversal for a company that effectively abandoned its solar business just two years ago.

The deal

Reuters reports that the equipment is valued at roughly 20 billion yuan ($2.9 billion) and that Tesla is in discussions with multiple Chinese suppliers. The frontrunner is Suzhou Maxwell Technologies, a Shenzhen-listed company that dominates the global market for solar cell screen-printing production lines.

Other potential suppliers include Shenzhen S.C New Energy Technology and Laplace Renewable Energy Technology.

Advertisement – scroll for more content

The Chinese companies have been told to deliver the equipment before this autumn, with at least two sources indicating it would be shipped to Texas. That aligns with Tesla’s expanding Texas manufacturing footprint, which already includes its Austin Gigafactory and a new Houston Megafactory under construction for Megapack production.

One significant hurdle remains: Suzhou Maxwell needs export approval from China’s commerce ministry, and it’s unclear how quickly that clearance will come. Beijing has been tightening its grip on solar technology exports over the past two years, and China’s commerce ministry recently made export controls a top priority for 2026.

On the US side, the equipment faces a more favorable regulatory path. Solar manufacturing equipment was excluded from Section 301 tariffs in 2024 at the urging of American solar panel makers, and that exemption has been extended by the Trump administration through November 2026.

The 100 GW ambition

The $2.9 billion equipment purchase is tied directly to a goal Musk laid out at the World Economic Forum in Davos in January 2026. There, he announced that both Tesla and SpaceX are independently working to build 100 GW per year of solar manufacturing capacity in the US — covering the entire supply chain from raw materials to finished panels.

The company’s own job listings reinforce the scale of the ambition, explicitly referencing a target of 100 GW of “solar manufacturing from raw materials on American soil before the end of 2028.”

For context, total US solar installations in 2023 reached about 32 GW. Tesla wants to manufacture more than three times that, every single year, on its own.

The driving force behind the urgency isn’t climate policy, it’s AI. Data center construction and the broader electrification of transportation pushed US power consumption to a second consecutive record in 2025, and the projections keep rising. Musk has argued that no other energy source can scale fast enough or cheaply enough to meet those demands.

Tesla’s troubled solar history

The irony is thick. Tesla acquired SolarCity for $2.6 billion in 2016 and promised to revolutionize the residential solar market with its Solar Roof tiles. Musk set a target of 1,000 new solar roofs per week by the end of 2019. Tesla never came close. By Q2 2022, the company was deploying approximately 23 roofs per week — roughly 2% of the target.

Today, Tesla never talks about its solar roof; it’s essentially a dead product.

Tesla’s solar deployment declined steadily after the SolarCity acquisition. Panasonic, which had partnered with Tesla at the Buffalo Gigafactory to manufacture solar cells, exited the facility in 2020. By late 2024, Tesla stopped reporting solar deployment altogether, and the word “solar” didn’t appear once during the company’s Q3 2024 earnings call.

There were signs of a revival in early 2026 when Tesla launched a new US-made solar panel (the TSP-420) assembled at the Buffalo factory, featuring a proprietary 18-zone power optimization system. But the scale was modest — initial capacity at the Buffalo facility was just over 300 MW per year, a rounding error compared to the 100 GW target.

Energy storage is a different story

While Tesla’s solar business withered, its energy storage division exploded. Tesla deployed a record 46.7 GWh of energy storage in 2025, a 48% increase year-over-year, generating $12.8 billion in revenue with a 29.8% gross margin — nearly double what Tesla earns selling cars.

Energy storage now accounts for 13% of Tesla’s total revenue and 23% of its gross profit. The Lathrop Megafactory in California produces Megapacks at its full planned capacity of 40 GWh per year, and the new Houston facility targets 50 GWh of annual output by end of 2026.

The solar manufacturing push would complement this storage infrastructure — Tesla could theoretically pair its own solar panels with Megapacks and Powerwalls for integrated energy solutions, and potentially use the output to power its own operations and even SpaceX satellites.

Electrek’s Take

We’ve been tracking Tesla’s solar journey since the SolarCity acquisition, and the trajectory has been one of consistent underdelivery. The Solar Roof never materialized at scale. Solar deployments cratered. The entire solar business segment became an afterthought as energy storage consumed all of Tesla’s energy division attention.

So when Musk announced a 100 GW solar manufacturing target at Davos, our first instinct was skepticism — and it still is. Going from roughly 300 MW of annual solar panel capacity at the Buffalo factory to 100 GW is a staggering 300x increase, on a timeline of less than three years.

That said, the $2.9 billion equipment purchase suggests this isn’t just talk. That’s real capital being deployed (or at least negotiated), and the autumn delivery deadline for equipment in Texas suggests Tesla intends to move fast. The company also has genuine tailwinds: the tariff exemption on solar manufacturing equipment, surging electricity demand from AI data centers, and a proven energy division that can integrate solar with its storage products.

The biggest risks are execution, Tesla’s solar track record is dismal, and the Chinese export approval, which Beijing could use as leverage in the ongoing trade tensions. We’ll believe the 100 GW target when we see equipment on the ground and production lines running.

Add Electrek as a preferred source on Google

FTC: We use income earning auto affiliate links. More.

Free Training

Source link

Palantir CTO says artificial intelligence is key to reshoring American manufacturing


Could artificial intelligence be the key to reshoring American manufacturing?

That’s what Palantir’s chief technology officer, Shyam Sankar, believes. His new book, “Mobilize,” asserts that America can prevent World War III by rebuilding its industrial base with AI-powered workers who can outcompete China’s automated factories.

“If you can make the American worker 50 times more productive than any other worker, you can change the math equation and underwrite the business case to re-industrializing at scale,” Sankar told me.

Palantir CTO Shyam Sankar believes, “If you can make the American worker 50 times more productive than any other worker, you can change the math equation and underwrite the business case to re-industrializing at scale.” Bloomberg via Getty Images

“Mobilize” is a remarkably optimistic book that counters the narrative that AI is going to destroy all our jobs (and maybe humanity as a whole). Instead, it argues AI will bring production back to the US, restoring our manufacturing capabilities and that sector’s jobs, while making our nation more secure.

“AI is leading to more jobs — and I’m not talking about ephemeral jobs building data centers,” Sankar said, refuting the prevailing doom-and-gloom narrative around artificial intelligence. “I’m talking about persistent jobs … on the factory floor.”

Sankar applauds what he calls the “heretics” who built our country — innovators like Hyman Rickover, the “Father of the Nuclear Navy,” whom higher-ups initially dismissed, placing his office in a converted bathroom until he proved himself. He’s a big believer in rule-breakers who eschew bureaucracy, and that’s exactly why he thinks America will win.

The 44-year-old is uniquely positioned to make this argument. He’s one of a handful of voices in Silicon Valley with both deep technical expertise when it comes to government systems — he’s spent over a decade ironing out deals with the Pentagon — and a strong sense of patriotism.

Czinger Vehicles uses AI-optimized design software and advanced 3D metal printing to create ultra-lightweight, high-performance supercars with components that can’t be manufactured through traditional methods. Carlin Stiehl for NY Post

The book’s publication comes at a fortuitous moment. War is on everyone’s mind with the conflict in Iran (not to mention the recent intervention in Venezuela and Cuba possibly next). Reshoring has become bipartisan policy, with the CHIPS Act pouring $39 billion into domestic manufacturing, and AI anxiety dominates headlines.

“For a long time I feel like I’ve been screaming into the wind — I’m glad to see that there’s momentum around this,” Sankar said. “It’s a book about our national interest … we’ve survived for 250 years. How will we continue to thrive for the next 250 years? 

He believes the AI race has given America an edge to dominate what could have been a Chinese century, given the Asian superpower’s vast resources and manufacturing capabilities. It’s the kind of game-changing advantage that will help America reshore in record time — and he wants America to grab it by the horns.

He’s already seen Palantir customers adopting the technology. One submarine parts manufacturer used AI to cut planning time from two weeks to ten minutes and hired a third shift as a result.

Alex Karp co-founded and runs Palantir, which builds data analysis and AI systems for military and intelligence agencies. Getty Images

“That’s AI in the hands of the American worker,” Sankar enhused.

These aren’t isolated anecdotes. Defense companies like Anduril, Hadrian, and Divergent are scaling their manufacturing operations in the US, betting on AI-enhanced American workers over overseas alternatives. Firms like Andreessen Horowitz have launched funds like American Dynamism exclusively focused on American innovation.

This story is part of NYNext, an indispensable insider insight into the innovations, moonshots and political chess moves that matter most to NYC’s power players (and those who aspire to be).

Palantir works extensively with both the Pentagon, building data analysis and AI systems for intelligence agencies, and the Department of Homeland Security. While critics see this as the tech industry cozying up to the military-industrial complex, Sankar wants to see more companies embrace helping the military.

In fact, he points to some of the primes — huge defense contractors such as Boeing and Lockheed Martin — as part of the problem

“Consolidation bred conformity … it was more financial engineering than real engineering,” he said. “Competition, not coziness, drives progress.”

“For a long time I feel like I’ve been screaming into the wind,” Sankar said of the need for reshoring manufacturing. “I’m glad to see that there’s momentum around this.”

But Sankar’s larger point is that production and innovation are inseparable — cede one, and you’ll eventually lose the other.

“The central lie of globalization is, ‘Hey, we’ll do the innovation over there, they’ll do the production,’” he explained. “Well, guess what? If you do the production for long enough, that’s all the stimulus you need to figure out how to innovate … We cannot cede production.”

A key component of Sankar’s plan is returning to the World War II model: companies that can pivot from manufacturing consumer goods to weapons when needed. When General Motors and Ford famously retooled for war production, they succeeded because they already had mass manufacturing capabilities in place, so they could rapidly switch what they were building.

That adaptability, not simply stockpiles of weapons, is what actually deters conflicts, Sankar argues.

Hadrian builds AI-powered automated factories that manufacture precision aerospace and defense components. Hadrian

“The lesson of Ukraine that I just can’t unsee is that the stockpile is not the deterrent. That has been our core strategy since the end of the Cold War,” he said. “[In Ukraine], we went through ten years of production in ten weeks of fighting. That should have been a five alarm fire where we fired up the forges started rebuilding the arsenal of freedom.”

His vision demands a complete reimagining of American manufacturing capacity. “I want more than ten times more of the equipment that we have,” he said. “That’s going to force you to reimagine all your constraints.”

The stakes couldn’t be higher, and it’s not just about the defense sector.

“Eighty percent of our generic drugs come from China,” Sankar noted. “In a [potential war] with China, where the average American has to choose between their five-year-old dying of an ear infection because we no longer have generic antibiotics … and having the national will to fight, what do you think is going to happen?”

It’s this dependency crisis that drives Sankar’s sense of urgency. America faces a stark choice. He said, “We can fade away to irrelevance and subjugation, or we can actually mobilize.”

Free Training

Source link

Is CSL’s US$3 Billion US Manufacturing Push Altering The Investment Case For CSL (ASX:CSL)?


  • Earlier this month, CSL broke ground on a major expansion of its Kankakee, Illinois manufacturing facility, aiming to boost plasma-derived therapy and albumin output using its patented Horizon 2 process while adding at least 300 new pharmaceutical roles and about 800 construction jobs.
  • This multiyear U.S. build-out, part of more than US$3.00 billion invested in American operations since 2018, signals CSL’s intention to deepen its U.S. manufacturing base and improve plasma efficiency to support longer-term therapy supply.
  • We’ll now examine how this large-scale U.S. manufacturing expansion, built around CSL’s Horizon 2 technology, could influence the company’s investment narrative.

The future of work is here. Discover the 32 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.

CSL Investment Narrative Recap

To own CSL, you need to believe its plasma and specialty therapies portfolio can translate operational improvements into healthier margins after a tough stretch of lower profitability and share price underperformance. The Kankakee Horizon 2 expansion supports the longer term efficiency story, but it does not materially change the near term focus on cost control, execution on new product launches, and the risk that rising collection and manufacturing costs keep pressuring margins.

The recent Kankakee expansion update ties most closely to CSL’s broader manufacturing and cost transformation efforts, including the multiyear US$0.5 billion savings program targeting better plasma collection and processing efficiency. Together with initiatives like Horizon 2, these moves sit at the heart of the main positive catalyst for the stock: whether CSL can convert process improvements into sustainably higher gross margins while managing risks from price competition, regulatory shifts and the planned Seqirus demerger.

Yet investors should be aware that rising plasma costs and lower recent profit margins could still weigh on CSL if…

Read the full narrative on CSL (it’s free!)

CSL’s narrative projects $18.1 billion revenue and $4.2 billion earnings by 2028.

Uncover how CSL’s forecasts yield a A$205.16 fair value, a 52% upside to its current price.

Exploring Other Perspectives

ASX:CSL 1-Year Stock Price ChartASX:CSL 1-Year Stock Price Chart

Some of the lowest ranked analysts were assuming only about 2.9 percent annual revenue growth to roughly US$16.9 billion and earnings around US$3.7 billion, which is far more cautious than the consensus and could be challenged or reinforced by how effectively CSL’s Kankakee build and wider efficiency plans actually improve margins over time.

Explore 18 other fair value estimates on CSL – why the stock might be worth over 2x more than the current price!

The Verdict Is Yours

Don’t just follow the ticker – dig into the data and build a conviction that’s truly your own.

Ready For A Different Approach?

Our top stock finds are flying under the radar-for now. Get in early:

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: AI Stock Screener & Alerts

Our new AI Stock Screener scans the market every day to uncover opportunities.

• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies

Or build your own from over 50 metrics.

Explore Now for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

LGM Pharma Expands U.S. Manufacturing, Bringing Total Investment to $15M Across Texas and Colorado Sites


— $9M Second Phase of CDMO Investment Builds on 2025 $6M Expansion, Funding Facility Upgrades and Increased Capacity for Suppository, Semi-Solid, and Oral Solid Dose Capacity —

— Enhancements Strengthen Domestic Supply Chains for Finished Dose Manufacturing, Complementing Extensive API Sourcing and Analytical Testing Services —

BOCA RATON, Fla.–(BUSINESS WIRE)–#505b2–LGM Pharma, a leading provider of tailored API sourcing, contract analytical testing, and CDMO services for the full drug product lifecycle, today announced the second phase of its CDMO growth strategy, committing an additional $9 million to its facilities in Rosenberg, Texas, and Colorado Springs, Colorado. The investment follows the company’s previously announced $6 million expansion in Rosenberg in 2025 and is designed to increase commercial capacity, expand R&D capabilities, and support continued demand for U.S.-based drug product manufacturing.


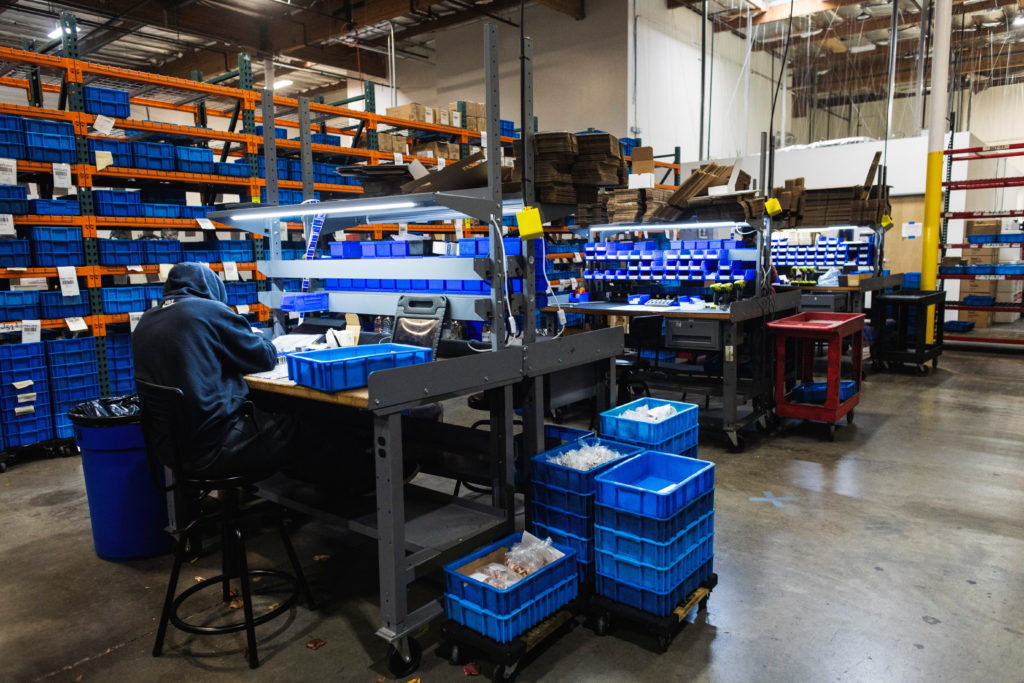
The Texas facility enhancements include a $4 million investment to expand commercial-scale manufacturing suites for suppositories in response to increasing customer and market demand, including growth in women’s health products. The upgrades also expand R&D capabilities to support formulation and scale-up for suppositories, solutions, suspensions, and semi-solids. The Rosenberg site will remain fully operational throughout construction, with upgrades already underway.

In Colorado Springs, LGM Pharma will invest $5 million to expand commercial manufacturing capacity for niche, high-value oral solid dose (OSD) products, including orally disintegrating tablets (ODTs). The facility has served as the company’s center of excellence for OSD development. The expansion, planned for completion this year, will support growing demand for domestic manufacturing. In 2024, the global OSD CDMO market was valued at $43.65 billion, with North America accounting for approximately 40.5% of global OSD pharmaceutical manufacturing activity.1,2

“These multi-site investments totaling $15 million reflect our continued commitment to strengthening pharmaceutical supply chains in the United States,” said Prasad Raje, Chief Executive Officer of LGM Pharma. “Today’s pharma companies need partners that are both resilient and integrated across the full product lifecycle. By reinforcing domestic drug product manufacturing at the downstream end of the supply chain, closer to end markets, and leveraging our global API sourcing capabilities upstream, we create a balanced end-to-end model. This gives customers greater control and visibility as they move products from development to commercialization.”

Earlier in the supply chain, at the drug substance stage, LGM Pharma supports 505(b)(2), NDA, and ANDA programs through a global network of more than 220 pre-qualified API manufacturers. By combining global drug substance sourcing with expanded U.S. finished dose development and manufacturing, the company provides integrated support across the full drug product lifecycle.

Hamilton Lenox, Chief Commercial Officer of LGM Pharma, said the company’s prior Rosenberg upgrades from Phase I of the expansion, including implementation of enhanced track-and-trace serialization systems and increased production volumes, are now complete. “We are executing this next phase of expansion while keeping both facilities fully operational,” Lenox said. “Our teams are experienced in managing complex upgrades without sacrificing quality or disrupting customer supply, which remain our top operational priorities. Rather than overextending in a single phase, we are executing these enhancements incrementally to expand capabilities and capacity while ensuring operational continuity. This approach allows us to strengthen infrastructure, support customer growth, and scale in response to market demand.”

Companies developing 505(b)(2), NDA, or ANDA products, as well as those with commercial branded or generic portfolios, are encouraged to explore LGM Pharma’s API sourcing and expanded drug product manufacturing capabilities by visiting LGMPharma.com or meeting with company executives at DCAT Week, March 23-26, 2026, in New York City.

References:

  1. Grand View Research, “Oral Solid Dosage CDMO Market Size, Share & Trends Analysis Report,” [March 2024].
  2. Persistence Market Research, “Oral Solid Dosage Contract Manufacturing Market,” [May 2023].

About LGM Pharma

LGM Pharma is a leading contract development and manufacturing organization (CDMO) providing comprehensive Active Pharmaceutical Ingredient (API) sourcing, drug product CDMO services, and contract analytical testing services to the pharmaceutical, biotechnology, and compounding pharmacy industries. LGM Pharma assists clients in managing all phases of the drug product development process, from API sourcing through to drug product commercialization. LGM Pharma’s extensive global network of qualified API partners enables clients to optimize supply chain management and distribution. Services include API sourcing and procurement, formulation development, drug product manufacturing, analytical method development, method and process validation, ANDA/NDA submission, stability studies, and raw material and finished product testing and packaging. LGM Pharma is committed to quality and has a long-established positive regulatory track record, providing expert regulatory and market intelligence services to its clients. The company is focused on customer service and customized solutions, providing clients with a comprehensive U.S.-based manufacturing solution that reduces risk, increases efficiency, and accelerates the path to commercialization. For more information, visit LGMPharma.com.

Contacts

Media Contact:

Charya Wickremasinghe, Ph.D.

Brandwidth Solutions LLC

cwickremasinghe@brandwidthsolutions.com


Free Training

Source link

The Missing Layer in U.S. Manufacturing Readiness: Rahul Kumar Thatikonda’s Case for Overlay Interoperability


The Readiness Gap Behind Modern Manufacturing

American manufacturing has spent years improving visibility across supply chains, procurement networks, and production systems. But visibility alone does not guarantee readiness. In many continuity-sensitive environments, the harder problem begins after new information arrives. Supplier instability, material shortages, severe weather, government restrictions, and conflict-related sourcing disruptions can all affect whether production remains on track. Yet in many organizations, those signals still emerge outside the purchasing, inventory, planning, and operations systems that govern daily decisions.

That gap has become harder to ignore. Modern disruption moves faster than many industrial systems were built to handle. Even when companies can detect risk, they may still struggle to translate that information into a procurement adjustment, a supplier-readiness review, or a planning action that can be tracked, escalated, and governed inside existing workflows. In practice, the weakness is often not the absence of data. It is the absence of a practical layer that can turn new information into reviewable operational action.

For large manufacturers, that problem is not theoretical. Many still rely on older enterprise environments that remain deeply embedded in procurement, inventory control, planning, and fulfillment. Replacing those systems outright is often expensive, operationally risky, and slow. The more urgent question is whether the systems companies already depend on can be made more responsive to the kinds of disruption signals that increasingly shape continuity and readiness.

Why Visibility Alone Is Not Enough

The industrial conversation around resilience often emphasizes forecasting, dashboards, and visibility platforms. Those tools can help identify risk, but they do not solve the harder operational problem on their own. A signal is only useful if it reaches the workflow where action can actually be taken.

That is the missing layer in many manufacturing environments: not data collection, but operational translation. A weather event may threaten inbound logistics. A supplier delay may change material availability. A government restriction may affect sourcing or delivery. But unless that information can be connected to the systems that control purchasing, planning, and operations, the organization may still respond too late.

This is one reason legacy dependence remains a serious issue across large enterprises. In practice, many organizations cannot pause operations for a full modernization effort every time new categories of risk emerge. They need ways to work with the infrastructure they already have. That makes interoperability more than a technical convenience. It becomes part of how readiness is preserved under stress.

A Systems-Focused Background

    Rahul Kumar Thatikonda is a digital transformation leader whose work focuses on industrial AI, enterprise interoperability, decision-support systems, orchestration frameworks, and supply-chain resilience in legacy-heavy operating environments. He earned a Master of Science in Business Analytics & Project Management from the University of Connecticut School of Business in 2018, and additional information about his technical work and publications is available through his public research profiles.

    His technical record has centered on a recurring problem in large organizations: how to make new operationally important information usable inside older systems that were never designed to absorb it quickly. Public technical materials associated with his research include work on orchestration for ERP-connected environments, readiness protocols, resilient interoperability, and industrial risk modeling.

    That focus matters because large manufacturers do not operate in abstract digital environments. They operate through embedded workflows, existing system constraints, and decision chains that often cannot be redesigned overnight. In that context, the most valuable technical work is not always the loudest or the most futuristic. It is often the work that makes real systems more usable under real conditions.

    An Overlay Approach to Industrial Readiness

      At the center of Thatikonda’s work is a reusable overlay interoperability framework intended to help manufacturing organizations use incoming disruption-related information without requiring full replacement of their core systems. The approach is designed to connect signals such as supplier delays, shortages, weather events, restrictions, logistics interruptions, and sourcing disruptions to existing workflows and convert them into reviewable, trackable actions. Those actions may include risk alerts, supplier-readiness prompts, procurement adjustments, and other controlled interventions that allow personnel to respond earlier and with greater clarity.

      That distinction matters. Much of the discussion around industrial AI still falls into one of two categories: ambitious modernization programs that are difficult to implement at scale, or analytics layers that increase visibility without changing operational response. Thatikonda’s framework sits in a more practical middle ground. The point is not simply to generate more alerts or more predictions. It is to make incoming disruption information usable inside legacy purchasing, inventory, planning, and operational systems without forcing companies to abandon the systems they already use.

      In that sense, the work is about more than software integration. It is about interoperability as a readiness discipline. The underlying premise is that organizations need a governed way to translate fragmented external signals into workflow actions that can be reviewed, tracked, and acted upon before disruption escalates into a larger continuity problem.

      From Architecture to Early Validation

      What gives this work more weight than a purely conceptual model is that it has already been formalized through technical documentation, public dissemination, and architecture-level development. Publicly available materials associated with Thatikonda’s work include technical reports and protocol documents on AI-enabled order-to-cash acceleration, readiness frameworks, orchestration for ERP-connected systems, and resilient interoperability design. 

      Those materials suggest a pattern that matters in industrial systems work: the contribution is being documented in a way that allows outside readers to assess the architecture, not merely hear broad claims about it. In fields where many ideas remain internal to organizations, that level of technical explanation helps separate a defined framework from a general business concept.

      The record also suggests that the framework has been shaped by experience in large enterprise settings where interoperability, workflow control, and cross-system orchestration matter. The most careful way to read that background is not as proof that every implementation question has already been solved, but as evidence that the framework has been informed by practical operating conditions rather than abstract software theory alone. That is an important distinction in manufacturing, where pilot results and architecture discipline often matter more than broad claims of disruption.

      A further sign of seriousness is that the work has also been formalized through patent-related development covering orchestration, interoperability, and resilient deployment architecture.  This does not by itself establish adoption, nor should it be read that way. What it does suggest is that the contribution is being developed as a defined technical framework with enough coherence to support formalization, scrutiny, and continued refinement.

      Why the United States Needs This Work

      The significance of this kind of work lies less in broad claims about artificial intelligence and more in its relevance to continuity-sensitive industrial environments. In sectors where production readiness and supply continuity matter, earlier and more controlled operational response can make a meaningful difference. The challenge is not simply whether risk can be detected. It is whether organizations can absorb that information into the systems that still drive decisions.

      That is part of what makes overlay interoperability an important idea at this moment. Many manufacturers in the United States are operating in a world where disruption signals are increasing, but infrastructure replacement cycles remain slow. Under those conditions, practical modernization may depend less on rebuilding everything from the ground up and more on making existing systems more capable of using the information modern disruption keeps generating.

      This is where Thatikonda’s work has broader relevance, particularly in supporting the objectives of the Department of Defense’s National Defense Industrial Strategy (NDIS). It addresses a recurring problem faced by large companies across aerospace, defense-related, and other critical manufacturing settings… The United States needs more work in this category because industrial resilience does not depend only on high-level policy goals, domestic capacity, or supplier diversification mandates. It also depends on whether organizations can act on operationally relevant information in time to reduce downstream shortages, delays, and production instability. A practical framework that helps companies use that information inside the systems they already operate addresses a real implementation gap in American manufacturing readiness.

      A More Practical Model of Resilience

        Industrial resilience is often discussed in sweeping terms: digital transformation, predictive intelligence, next-generation manufacturing. Those themes matter, but they can obscure a more immediate operational truth. Many of the systems that still run large organizations were not built to absorb today’s disruption signals in real time, and many companies cannot afford to replace them overnight.

        That reality is what makes a practical overlay model compelling. Instead of assuming that resilience must begin with total replacement, it starts from the conditions large organizations actually face: layered systems, embedded workflows, long modernization cycles, and the need for earlier, better-governed decisions under uncertainty.

        Thatikonda’s work suggests that one of the most important advances in manufacturing readiness may not come from starting over, but from building disciplined ways to make existing systems more responsive under stress. If that approach continues to mature across critical manufacturing settings, it could help define a more realistic path for continuity, responsiveness, and industrial readiness in the United States.

        For additional technical and publication records associated with Rahul Kumar Thatikonda, readers may refer to his ORCID profile: https://orcid.org/0009-0000-1234-7915

        Free Training

        Source link

Trump’s tariffs are causing harm to American manufacturers instead of benefiting them


WASHINGTON (AP) — Jay Allen is a fan of President Donald Trump, and voted for him on the belief that the Republican would cut taxes and trim regulations, helping his manufacturing business in northeast Arkansas.

READ MORE: Trump administration starts new process to try to replace tariffs struck down by Supreme Court

But the tariffs at the core of Trump’s economic agenda have wreaked havoc on his company, Allen Engineering Corp., which makes industrial equipment used to install, finish and pave concrete. The import taxes have raised the costs of engines, steel, gearboxes and clutches made abroad that Allen needs to build power trowels that can sell for up to $100,000 each.

Allen’s experience embodies a growing body of evidence that the tariffs that Trump said would help American factories are, in fact, squashing many of them. The problem could get worse as the administration scrambles to craft new tariffs to replace the emergency import taxes that the Supreme Court ruled illegal in February.

WATCH: Trump says tariffs could replace income tax

Allen said he ran his company at a loss in 2025 because of tariffs. His payroll has fallen to 140 workers from a peak of 205. To get by this year, he has hiked prices by 8% to 10%, even though that might mean fewer sales.

“What’s really sad is the unintended consequences of his tariffs are hurting manufacturing in our country,” said Allen. “Unfortunately, the working-class people are getting squeezed.”

Manufacturing jobs have declined during Trump’s first year back

Trump’s core rationale for tariffs has been that they would force more factories to open in the U.S. and would generate enough revenue to close federal budget deficits. But that hasn’t materialized.

Factories continue to shed workers, with 98,000 manufacturing jobs lost during Trump’s first full 12 months back in the White House. American companies that foot the bill for tariffs are now suing the Trump administration for more than $130 billion in tariff refunds. Meanwhile, the federal deficit is projected to climb over the next decade.

READ MORE: U.S. employers added just 73,000 jobs last month as labor market weakens in face of Trump trade wars

The White House maintains that construction spending is high, more workers are being hired to build factories, new investments are being made and labor productivity in manufacturing is increasing — which could eventually fuel a factory revival.

“It takes time to get production online, and therefore it will be some more time before we fully materialize the benefits of the president’s policies,” Pierre Yared, the acting chairman of the White House Council of Economic Advisers, said in an email.

Construction is up — but that’s due to Biden’s bill

Some of the bright spots in construction cited by the White House appear to be the result of programs launched by then-President Joe Biden, a Democrat.

Factory construction spending began to accelerate in 2022 with the anticipation of government support from Biden’s CHIPS and Science Act, which included big subsidies for computer chip plants. The law was a primary contributor to a historic surge in the annualized rate of construction spending on manufacturing facilities, said Skanda Amarnath, executive director of the economic policy group Employ America.

READ MORE: Trump’s tariffs could squeeze U.S. factories and raise costs by up to 4.5%, a new analysis finds

Construction spending on factories has slipped during Trump’s presidency, but the pace remains relatively high largely because of continuing work on Biden-era projects in Arizona, Texas and Idaho, Amarnath said.

Amarnath has also gone through the interviews regional Federal Reserve banks have held with businesses. Those comments show some companies might expand by taking advantage of Trump’s tax breaks on investments in equipment and new buildings.

But while the pharmaceutical drug sector might be expanding, the comments show no overall uptick in manufacturing because of Trump’s tariffs.

“You don’t get the sense that there is this new manufacturing renaissance underway,” Amarnath said.

Uncertainty in tariffs has deterred investments

Based on orders, proclamations and other statements, Trump has taken more than 50 actions on tariffs so far — and that tally doesn’t include the tariff threats he regularly makes on social media or in conversations with reporters but hasn’t formally put in place.

The flurry of announcements, reversals, exemptions and legal challenges — as well as Trump’s decision to bypass Congress to impose tariffs — has made it difficult for smaller manufacturing companies to plan.

For example, Allen Engineering imports its 75-horsepower diesel engines from Germany. Building them in the United States would require a $20 million investment — a huge risk if the status of the tariffs is unclear.

WATCH: Business owner who challenged Trump’s tariffs reacts to Supreme Court decision

Are engine-makers “going to spend that kind of money to move production from Germany to the U.S. when they don’t know what the landscape is going to be in three years?” Allen said. “I don’t know who is going to be in the White House, and what the stance is going to be on these tariffs.”

Joseph Steinberg, an economist at the University of Toronto, said research shows that under the best-case scenario “it would take a decade for manufacturing employment to rise above where it was before tariffs were enacted.”

But Steinberg said “the current situation is nothing like the ‘best case,'” since U.S. trade policy is unsettled and that leaves companies reluctant to expand.

Equipment makers have been hit hard by rising steel costs

About 98% of U.S. manufacturing establishments have fewer than 200 workers, according to Census Bureau data, and don’t have the kind of name-brand recognition or lobbying heft to minimize the damage from tariffs that big players like Apple, General Motors and Ford possess.

The Association of Equipment Manufacturers in February reported that America’s share of global manufacturing severely lags China’s. The group has urged tax credits to offset the expense of tariffs, and specifically called for tariff relief on raw materials, parts and components that cannot be acquired domestically at scale.

Steel tariffs have been a particular concern. Trump imposed them last March and hiked them to 50% in June. They were not affected by the Supreme Court decision.

READ MORE: Trump’s 50% tariffs on steel and aluminum go into effect. Here’s what to know

Trump has credited the tariffs with restoring profits at American steel mills. But they have hurt companies that use that steel, like Calder Brothers in South Carolina, which makes equipment to pave asphalt.

“The steel tariffs were the first thing that got my attention,” said Glen Calder, the company’s president. “My steel pricing jumped 25% two weeks before the tariffs went into effect for domestic steel. The market price just jumped. It has stayed elevated.”

Meanwhile, China’s trade surplus has grown

Part of Trump’s push to expand manufacturing was to help American companies compete against China — a country he plans to visit this spring for talks with its leader, Xi Jinping.

But the U.S. manufacturing trade imbalance rose last year under Trump instead of narrowing. Meanwhile, China’s trade surplus with the world climbed to a record $1.2 trillion.

WATCH: How China is responding to pressure from Trump as trade war brews

This trend exposes one of the big problems with Trump’s tariff strategy, said Lori Wallach, director of the Rethink Trade program at American Economic Liberties Project. She noted that he largely bypassed Congress and failed to address gaps in the World Trade Organization’s rules for the trade frameworks that he negotiated with other countries.

Instead of working with partners to ensure there were penalties for foreign manufacturers with abusive labor practices and unfair subsidies, Trump chose against rallying partners to counter China as a unified group. American manufacturers are at a disadvantage, Wallach argued, because there is not a coalition of nations that can impose penalties for currency manipulation, subsidies and schemes to evade tariffs.

“The general revulsion of this administration to international cooperation means they’re trying to do it alone,” Wallach said.

A free press is a cornerstone of a healthy democracy.

Support trusted journalism and civil dialogue.


Donate now

Free Training

Source link

Qblox to Begin Manufacturing Quantum Control Electronics in Massachusetts


Insider Brief

  • Qblox announced that effective April 1st, it will manufacture quantum control electronics in the United States at a facility in Canton, Massachusetts, in partnership with Prodrive Technologies, and begin shipping products to customers from this location.
  • The shift to U.S. manufacturing aims to reduce lead times, improve supply-chain security, and align with U.S. procurement, compliance, and funding requirements while supporting Department of Energy and National Lab research through open-architecture manufacturing.
  • The Canton facility will support skilled technical roles across manufacturing, systems integration, logistics, and customer support, building on Qblox’s 2025 expansion into Boston and collaborations with universities, government, and industry partners.

PRESS RELEASE — Qblox, a leading provider of open-architecture quantum control electronics, today announced that effective April 1st, in partnership with Prodrive Technologies, products will be manufactured in the U.S. and will begin shipping to customers from its facility in Canton, MA. 

Building on the company’s 2025 expansion into Boston and its growing collaborations with universities, government, and industry partners, this milestone underscores Qblox’s commitment to strengthening the American quantum ecosystem across innovation, workforce development, and now manufacturing, while further cementing Massachusetts’ role as a hub for quantum innovation.

The shift to manufacturing quantum control systems in the U.S. brings meaningful advantages for customers, including reduced lead times, greater shipping efficiency, improved supply-chain security, and stronger alignment with U.S. procurement, compliance, and funding requirements. Advantages that will be integral for the U.S. to remain competitive in the global quantum industry as it moves closer to full-scale use. 

Responsive Image

It also enhances Qblox’s ability to provide onshore support and service while advancing transparent, open-architecture manufacturing that supports the Department of Energy and National Lab research. 

The Canton facility will support skilled technical roles across manufacturing, systems integration, logistics, and customer support, contributing to the growth of a high-tech workforce aligned with the future needs of quantum infrastructure. As public and private investment in quantum technology accelerates nationwide, Qblox’s expansion in Massachusetts reinforces both its role as a trusted infrastructure partner to the American quantum ecosystem and the Commonwealth’s growing reputation as a place where emerging technologies can be developed, built, and deployed at scale.

“Massachusetts is proud to be a global hub for quantum innovation, and Qblox’s investment in manufacturing in Canton strengthens our leadership in the technologies that will define the future,” said Governor Maura Healey. “I want to congratulate the Qblox team on this milestone and am proud that they are growing in Massachusetts, where our world-class research institutions, talented workforce and innovation ecosystem make it the ideal place to build the technologies of tomorrow.”

“Massachusetts is where breakthrough technologies move from research to real-world deployment,” said Economic Development Secretary Eric Paley. “By establishing its U.S. manufacturing and fulfillment hub in Canton, Qblox is strengthening domestic supply chains while tapping into Massachusetts’ deep bench of scientific talent, world-class research institutions and advanced manufacturing capabilities.”

“Building and shipping our systems in the United States allows us to be closer to the researchers, engineers, and institutions driving quantum innovation forward,” said Niels Bultink, Co-founder and CEO of Qblox. “This expansion reflects our long-term investment in the U.S. quantum ecosystem and our belief that proximity matters operationally, strategically, and economically.”

“Advanced technologies like quantum control systems require precise manufacturing and trusted partnerships,” said Pieter Janssen, co-founder & CEO at Prodrive Technologies. “As two companies with roots in the Netherlands and growing operations in Massachusetts, Prodrive and Qblox are proud to work together to strengthen the quantum ecosystem and deliver the reliability, quality, and scalability required for the next generation of quantum innovation.”

“Quantum technology is strategic infrastructure,” said Gregg Carman, General Manager and Head of North America for Qblox. “By manufacturing and shipping from the U.S., we are not only optimizing logistics, but also aligning with the long-term goals of American research institutions and the broader innovation economy. We’re proud to be growing that presence in Massachusetts, which offers a uniquely strong foundation for innovation-driven manufacturing and collaboration.”

Free Training

Source link

Siemens expands manufacturing footprint in the Carolinas to support data center growth – WSOC TV


Siemens has invested more than $165 million in North Carolina and South Carolina to support the artificial intelligence and data center markets. The investment includes the opening and expansion of several manufacturing sites across both states.

The new facilities are designed to increase the company’s manufacturing capacity in the United States to meet a rise in electrical equipment orders. According to a company news release, the expanded footprint will allow for faster production and delivery of low and medium voltage products to data center operators.

In North Carolina, Siemens is establishing two new all-electric and carbon-neutral facilities. A 131,000-square-foot site in Raleigh is expected to add 100 jobs by the end of 2026.

This location will assemble integrated power delivery solutions, which are prefabricated systems designed to reduce on-site installation time for power infrastructure.

The company is also opening a 101,000-square-foot site in Wendell. This facility will localize the production of medium voltage protection and automation devices. The expansion is expected to create 50 new roles at that location.

In South Carolina, a new 120,000-square-foot facility is opening in Spartanburg.

The site will house a distribution center and lighting panel production. Nearby in Roebuck, Siemens is expanding its existing facility by 22,000 square feet to increase busway production capacity. This expansion includes the addition of a new paint line, epoxy line and plating line.

The combined developments in Spartanburg and Roebuck will create 150 manufacturing roles in Spartanburg County. These investments follow nearly $700 million the company has committed to U.S. manufacturing in recent years, including expansions in Pomona, Calif., and Fort Worth, Texas.

The expansion of the Siemens Electrification and Automation U.S. headquarters in Wendell is expected to create more than 200 additional jobs by 2028. This growth will specifically support expanded local switchgear production.

VIDEO: Proposed data center regulations spark debate in York County

Free Training

Source link

Siemens Invests $165M for U.S. Data Center Manufacturing


Siemens has invested more than $165 million across North and South Carolina to support America’s rapidly accelerating AI and data center markets. The new and expanded sites directly support Siemens’ record levels of data center-related electrical equipment orders while also increasing the company’s US manufacturing capacity.These expanded facilities will enable faster production, assembly, and delivery of essential low and medium voltage products to customers. From protection and automation devices manufactured in Wendell, North Carolina, to busway systems produced in Roebuck, South Carolina, these solutions provide the electrical backbone needed to rapidly scale AI data centers and AI factories across the United States. These investments build on nearly $700 million Siemens has committed over the past several years to expand local U.S. manufacturing capacity, including new and expanded electrical products facilities in Pomona, California, and Fort Worth, Texas. “Customer demand is at an all-time high as advanced infrastructure upgrades are needed to meet the power requirements from increasing AI workloads,” said Ruth Gratzke, President of Siemens Smart Infrastructure U.S. “Through sustained investment in U.S. manufacturing, Siemens is enhancing its capacity to meet the needs of data center and AI factory customers during this transformative phase of the AI industrial revolution, underscoring our long‑standing commitment to American made solutions.”In North Carolina, Siemens is growing its footprint with two new all-electric, carbon�neutral facilities. In Raleigh, the brand new 131,000-square-foot facility will add 100 jobs by the end of the year and will assemble Siemens’ integrated power delivery solutions. These prefabricated systems significantly reduce on-site installation time for critical power infrastructure, helping data center operators bring capacity online faster. In Wendell, a new 101,000-square-foot site will localize production of medium voltage protection and automation devices while adding 50 new roles. Lastly, Siemens’ Wendell-based Electrification and Automation U.S. headquarters will expand local switchgear production, creating more than 200 additional jobs at the facility by 2028. In South Carolina, Siemens is opening a new 120,000-square-foot facility in Spartanburg that will house the company’s lighting panel production and distribution center. Nearby in Roebuck, the company’s current facility will also add 22,000 square feet. This will increase busway production capacity significantly along with additional fabrication capabilities. The expanded facility will feature a new paint line, epoxy line, and an expanded plating line. Together, the Spartanburg and Roebuck facilities will add 150 new manufacturing roles to Spartanburg County. “Siemens’ investment in North and South Carolina will expand America’s ability to build the critical infrastructure that powers our grid, while also creating hundreds of American jobs,” said U.S. Energy Secretary Chris Wright. “The Trump Administration remains committed to unleashing the affordable, reliable, and secure power needed to power the future of American innovation and prosperity.”These electrical products, together with Siemens’ simulation, automation and cooling optimization portfolios create a chip-to-grid-to-buildings solution that reshapes the infrastructure powering AI. Together these technologies ensure efficiency and resiliency for the data center industry as well as neighboring communities across the country.As workforce development is as critical as production capacity for the future of AI infrastructure, the Siemens Foundation recently launched Careers Electric™, a national initiative designed to expand access to high-quality electrical training and create clear pathways to well-paying, in-demand electrical careers. Careers Electric™ launched in North Carolina with a $9.25 million investment from the Siemens Foundation, in partnership with state leaders, education institutions, and national workforce organizations. Together, through increased manufacturing capacity, technology development and workforce training initiatives, Siemens remains committed to aiding the U.S. in its position as a leader in innovation.For more information on Siemens’ data center solutions, visit here.

Free Training

Source link

Skild AI Partners with Foxconn, ABB, Universal Robots for Industrial AI in 2026 – News and Statistics


Mar 16, 2026

According to Reuters, Skild AI will deploy its artificial intelligence model in robots operating on Foxconn assembly lines in Houston. These lines are involved in the construction of Nvidia‘s Blackwell GPU server racks. The companies characterized this as an initial commercial use of a generalized physical AI system.

The startup, which has financial backing from Nvidia and SoftBank, announced it would also collaborate with ABB Robotics and Universal Robots. The goal is to integrate its software into a wide range of industrial robots, providing what it terms a general-purpose brain for machinery. Skild AI stated its model is designed to overcome a major constraint of existing robotics, which are often dedicated to one specific task and need significant reprogramming for any change.

Partnerships with ABB and Teradyne‘s Universal Robots unit are aimed at increasing the volume of data for system training by embedding the software into their robots. The CEO of Skild AI indicated that working with original equipment manufacturers that have vast existing robot deployments creates a pathway for significant scaling and establishes a data feedback cycle.

These developments occur as the United States intensifies initiatives to restore its domestic manufacturing base. In 2025, new U.S. production investments totaling approximately $1.2 trillion were announced, primarily in electronics, pharmaceuticals, and semiconductors. Industry leaders note that the large-scale return of advanced manufacturing to the country will rely substantially on automation.

Nvidia, a key supporter of Skild AI, previously stated its intention to manufacture AI supercomputers completely within the United States. A company executive emphasized that with substantial infrastructure investment planned for the coming years, factories will require greater autonomy.

In a related move, SoftBank announced in October its agreement to purchase ABB’s robotics division. That transaction is anticipated to be finalized around the middle to end of 2026. Skild AI itself secured $1.4 billion in a financing round led by Nvidia and SoftBank earlier this year, resulting in a valuation exceeding $14 billion.

This report provides a comprehensive view of the industrial robot industry in the United States, tracking demand, supply, and trade flows across the national value chain. It explains how demand across key channels and end-use segments shapes consumption patterns, while also mapping the role of input availability, production efficiency, and regulatory standards on supply.

Beyond headline metrics, the study benchmarks prices, margins, and trade routes so you can see where value is created and how it moves between domestic suppliers and international partners. The analysis is designed to support strategic planning, market entry, portfolio prioritization, and risk management in the industrial robot landscape in the United States.

Quick navigation

Key findings

  • Domestic demand is shaped by both household and industrial usage, with trade flows linking local supply to imports and exports.
  • Pricing dynamics reflect unit values, freight costs, exchange rates, and regulatory shifts that affect sourcing decisions.
  • Supply depends on input availability and production efficiency, creating a distinct national cost curve.
  • Market concentration varies by segment, creating different competitive landscapes and entry barriers.
  • The 2035 outlook highlights where capacity investment and demand growth are most aligned within the country.

Report scope

The report combines market sizing with trade intelligence and price analytics for the United States. It covers both historical performance and the forward outlook to 2035, allowing you to compare cycles, structural shifts, and policy impacts.

  • Market size and growth in value and volume terms
  • Consumption structure by end-use segments
  • Production capacity, output, and cost dynamics
  • Trade flows, exporters, importers, and balances
  • Price benchmarks, unit values, and margin signals
  • Competitive context and market entry conditions

Product coverage

  • Prodcom 28993935 – Industrial robots for multiple uses (excluding robots designed to perform a specific function (e.g. lifting, handling, loading or unloading))

Country coverage

Country profile and benchmarks

This report provides a consistent view of market size, trade balance, prices, and per-capita indicators for the United States. The profile highlights demand structure and trade position, enabling benchmarking against regional and global peers.

Methodology

The analysis is built on a multi-source framework that combines official statistics, trade records, company disclosures, and expert validation. Data are standardized, reconciled, and cross-checked to ensure consistency across time series.

  • International trade data (exports, imports, and mirror statistics)
  • National production and consumption statistics
  • Company-level information from financial filings and public releases
  • Price series and unit value benchmarks
  • Analyst review, outlier checks, and time-series validation

All data are normalized to a common product definition and mapped to a consistent set of codes. This ensures that comparisons across time are aligned and actionable.

Forecasts to 2035

The forecast horizon extends to 2035 and is based on a structured model that links industrial robot demand and supply to macroeconomic indicators, trade patterns, and sector-specific drivers. The model captures both cyclical and structural factors and reflects known policy and technology shifts in the United States.

  • Historical baseline: 2012-2025
  • Forecast horizon: 2026-2035
  • Scenario-based sensitivity to income growth, substitution, and regulation
  • Capacity and investment outlook for major producing companies

Each projection is built from national historical patterns and the broader regional context, allowing the report to show where growth is concentrated and where risks are elevated.

Price analysis and trade dynamics

Prices are analyzed in detail, including export and import unit values, regional spreads, and changes in trade costs. The report highlights how seasonality, freight rates, exchange rates, and supply disruptions influence pricing and margins.

  • Price benchmarks by country and sub-region
  • Export and import unit value trends
  • Seasonality and calendar effects in trade flows
  • Price outlook to 2035 under baseline assumptions

Profiles of market participants

Key producers, exporters, and distributors are profiled with a focus on their operational scale, geographic footprint, product mix, and market positioning. This helps identify competitive pressure points, partnership opportunities, and routes to differentiation.

  • Business focus and production capabilities
  • Geographic reach and distribution networks
  • Cost structure and pricing strategy indicators
  • Compliance, certification, and sustainability context

How to use this report

  • Quantify domestic demand and identify the most attractive segments
  • Evaluate export opportunities and prioritize target destinations
  • Track price dynamics and protect margins
  • Benchmark performance against leading competitors
  • Build evidence-based forecasts for investment decisions

This report is designed for manufacturers, distributors, importers, wholesalers, investors, and advisors who need a clear, data-driven picture of industrial robot dynamics in the United States.

FAQ

What is included in the industrial robot market in the United States?

The market size aggregates consumption and trade data, presented in both value and volume terms.

How are the forecasts to 2035 built?

The projections combine historical trends with macroeconomic indicators, trade dynamics, and sector-specific drivers.

Does the report cover prices and margins?

Yes, it includes export and import unit values, regional spreads, and a pricing outlook to 2035.

Which benchmarks are included?

The report benchmarks market size, trade balance, prices, and per-capita indicators for the United States.

Can this report support market entry decisions?

Yes, it highlights demand hotspots, trade routes, pricing trends, and competitive context.

  1. 1. INTRODUCTION

    Making Data-Driven Decisions to Grow Your Business

    1. REPORT DESCRIPTION
    2. RESEARCH METHODOLOGY AND THE AI PLATFORM
    3. DATA-DRIVEN DECISIONS FOR YOUR BUSINESS
    4. GLOSSARY AND SPECIFIC TERMS
  2. 2. EXECUTIVE SUMMARY

    A Quick Overview of Market Performance

    1. KEY FINDINGS
    2. MARKET TRENDSThis Chapter is Available Only for the Professional EditionPRO
  3. 3. MARKET OVERVIEW

    Understanding the Current State of The Market and its Prospects

    1. MARKET SIZE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. MARKET STRUCTURE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. TRADE BALANCE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    4. PER CAPITA CONSUMPTION: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    5. MARKET FORECAST TO 2035
  4. 4. MOST PROMISING PRODUCTS FOR DIVERSIFICATION

    Finding New Products to Diversify Your Business

    1. TOP PRODUCTS TO DIVERSIFY YOUR BUSINESS
    2. BEST-SELLING PRODUCTS
    3. MOST CONSUMED PRODUCTS
    4. MOST TRADED PRODUCTS
    5. MOST PROFITABLE PRODUCTS FOR EXPORTS
  5. 5. MOST PROMISING SUPPLYING COUNTRIES

    Choosing the Best Countries to Establish Your Sustainable Supply Chain

    1. TOP COUNTRIES TO SOURCE YOUR PRODUCT
    2. TOP PRODUCING COUNTRIES
    3. TOP EXPORTING COUNTRIES
    4. LOW-COST EXPORTING COUNTRIES
  6. 6. MOST PROMISING OVERSEAS MARKETS

    Choosing the Best Countries to Boost Your Export

    1. TOP OVERSEAS MARKETS FOR EXPORTING YOUR PRODUCT
    2. TOP CONSUMING MARKETS
    3. UNSATURATED MARKETS
    4. TOP IMPORTING MARKETS
    5. MOST PROFITABLE MARKETS
  7. 7. PRODUCTION

    The Latest Trends and Insights into The Industry

    1. PRODUCTION VOLUME AND VALUE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  8. 8. IMPORTS

    The Largest Import Supplying Countries

    1. IMPORTS: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. IMPORTS BY COUNTRY: HISTORICAL DATA (2012–2025)
    3. IMPORT PRICES BY COUNTRY: HISTORICAL DATA (2012–2025)
  9. 9. EXPORTS

    The Largest Destinations for Exports

    1. EXPORTS: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. EXPORTS BY COUNTRY: HISTORICAL DATA (2012–2025)
    3. EXPORT PRICES BY COUNTRY: HISTORICAL DATA (2012–2025)
  10. 10. PROFILES OF MAJOR PRODUCERS

    The Largest Producers on The Market and Their Profiles

  11. LIST OF TABLES

    1. Key Findings In 2025
    2. Market Volume, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    3. Market Value: Historical Data (2012–2025) and Forecast (2026–2035)
    4. Per Capita Consumption: Historical Data (2012–2025) and Forecast (2026–2035)
    5. Imports, In Physical Terms, By Country, 2012–2025
    6. Imports, In Value Terms, By Country, 2012–2025
    7. Import Prices, By Country, 2012–2025
    8. Exports, In Physical Terms, By Country, 2012–2025
    9. Exports, In Value Terms, By Country, 2012–2025
    10. Export Prices, By Country, 2012–2025
  12. LIST OF FIGURES

    1. Market Volume, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    2. Market Value: Historical Data (2012–2025) and Forecast (2026–2035)
    3. Market Structure – Domestic Supply vs. Imports, in Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    4. Market Structure – Domestic Supply vs. Imports, in Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    5. Trade Balance, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    6. Trade Balance, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    7. Per Capita Consumption: Historical Data (2012–2025) and Forecast (2026–2035)
    8. Market Volume Forecast to 2035
    9. Market Value Forecast to 2035
    10. Market Size and Growth, By Product
    11. Average Per Capita Consumption, By Product
    12. Exports and Growth, By Product
    13. Export Prices and Growth, By Product
    14. Production Volume and Growth
    15. Exports and Growth
    16. Export Prices and Growth
    17. Market Size and Growth
    18. Per Capita Consumption
    19. Imports and Growth
    20. Import Prices
    21. Production, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    22. Production, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    23. Imports, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    24. Imports, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    25. Imports, In Physical Terms, By Country, 2025
    26. Imports, In Physical Terms, By Country, 2012–2025
    27. Imports, In Value Terms, By Country, 2012–2025
    28. Import Prices, By Country, 2012–2025
    29. Exports, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    30. Exports, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    31. Exports, In Physical Terms, By Country, 2025
    32. Exports, In Physical Terms, By Country, 2012–2025
    33. Exports, In Value Terms, By Country, 2012–2025
    34. Export Prices, By Country, 2012–2025

Free Training

Source link