US manufacturing output rises marginally in February


WASHINGTON: US factory production increased marginally in February as strength in motor vehicle output ‌was ⁠offset ⁠by weakness in machinery, data showed on Monday.

Manufacturing output rose 0.2% last month after ⁠an upwardly revised ‌0.8% gain in January, ⁠the Federal Reserve said.

Also Read: Trump may bring back tariffs ‘in another form’
Economists polled ​by Reuters had ​forecast production for the sector, which accounts for 10.1% ‌of the economy, rising 0.1% after ​a ​previously ⁠reported 0.6% rise in January. Production at factories advanced ​1.3% year-on-year in February.

Free Training

Source link

Poilievre unveils auto plan aiming for tariff-free access to U.S. market


Conservative Leader Pierre Poilievre unveiled the party’s most substantial auto strategy to date under his leadership, which he says will both bring back production to Canada and be “highly attractive” to partners south of the border.

“Canada’s auto sector must stay alive and it must have access to the U.S. to do so,” Poilievre said while in Windsor, Ont., on Sunday.  

Poilievre said he’d like to institute a tariff-free auto pact and has a plan to restore Canada’s auto production to two million cars per year over the next 10 years. 

Also included in the plan is a call to remove the GST on all Canadian-made vehicles, something the NDP and Conservatives proposed during the 2025 general election campaign. 

The proposal was announced amid Poilievre’s first visit to the United States since U.S. President Donald Trump launched his trade war, a significant marker in the Conservative leader’s shifting focus on global trade pressures brought about by the Trump administration. 

“He’s going down there to sell Canada, it’s what we have to do,” Conservative labour critic Kyle Seeback told Rosemary Barton Live. 

Seeback said the purpose of the trip is not to give the impression that there are two prime ministers in Canada.

Rather, he said, with the CUSMA (Canada-U.S.-Mexico Agreement) review coming up, Poilievre is making the case to U.S. business leaders about the importance of the trading relationship and how tariffs can hurt both countries.

WATCH | Conservative labour critic on the party’s auto plan, Poilievre’s U.S. trip:

Federal Conservatives pitch new auto strategy as tariffs roil industry

Conservative Leader Pierre Poilievre has announced a plan for the hard-hit auto sector that aims to secure tariff-free access to the U.S. market and boost Canada’s auto production. Chief political correspondent Rosemary Barton speaks with Conservative MP Kyle Seeback, the party’s labour critic, about the plan, as well as Poilievre’s U.S. trip.

Will Trump agree?

At the heart of this auto strategy is the push to get Trump to drop tariffs on Canada by selling this strategy as a better way to restore U.S. manufacturing. 

This push rests on the assumption that Trump is open to solving its trade relationship with Canada, despite there being a lack of evidence to suggest willingness on the part of the administration. 

Asked how he’d get Trump to give the green light, Poilievre says his plan addresses the president’s desire to repatriate production to the U.S. and would see a “massive production gain” on both sides of the border.  

A man in a suit shaking hands with another man in a suit as workers look on Poilievre meets with workers and politicians at Cavalier Tool and Manufacturing in Windsor, Ont., on Sunday. (Pratyush Dayal/CBC)

A 1-for-1 car deal

Poilievre laid out a one-for-one deal, where for every car manufactured in Canada, he said, that same producer would get a car to sell duty free from a partner in CUSMA. 

This can be sold as a “win, win,” said Seeback. 

“It’s a better way for the United States to reshore the auto manufacturing in their country while preserving their best export market for autos, which is Canada.”

Seeback says this strategy harkens back to the 1965 auto pact that kick-started free trade between Canada and the U.S., prior to the North American Free Trade Agreement. 

Seeback said this new version of the auto pact would position Canada to be able to harmonize with the U.S. on Chinese electric vehicle policy, part of Poilievre’s strategy to bring “maximum leverage” to the CUSMA review.

“When you put these things together, helping them restore their auto manufacturing, preserving the Canadian market and better alignment on things like Chinese electric vehicles, we actually think there’s an opportunity to get that deal,” said Seeback. 

The federal government recently struck a deal with China to bring tariff relief for Canada’s agricultural and seafood sectors.

In a move that broke ranks with the U.S., Prime Minister Mark Carney agreed to allow up to 49,000 Chinese electric vehicles into Canada, lowering a 100 per cent tariff on imports, imposed in 2024, back to six per cent. 

A tale of three strategies 

The U.S. strategy has been focused on protecting its big three automakers: General Motors, Ford Motor Company and Stellantis. 

To thwart Trump’s protectionist policies, Carney’s approach has been to diversify Canada’s trading partners and look to attract European, Japanese and Korean automakers to Canada. 

Now, more than a year after Trump returned to office, Poilievre is looking to show his plan for dealing with the White House.

For decades, Canada’s sales pitch to the world has rested on having tariff-free access to the U.S. market. Seeback said that if that’s not the case, there’s “not a single producer in the world” that will come to Canada to start new production.

Seeback calls Carney’s approach “managed decline” and said he does not believe it will work. 

Poilievre said that even Mexico would have to accept the plan to avoid ending up with something “much worse.” 

More U.S. meetings ahead

On Friday, Poilievre was in Detroit to meet with senior executives of General Motors and Ford. He crossed the Detroit River back into Canada Sunday to make his auto strategy announcement in Windsor.

His U.S. travel will continue with stops in Texas and New York, with no visit planned for the U.S. capital. 

In an interview on The Paul Wells Show podcast, Poilievre said he updated Carney about his travel plans on the margins on Question Period last Wednesday and plans to debrief him once he returns.

Free Training

Source link

After China outlay, Lilly plugs $126M into Japan manufacturing plant expansion


While much of the company’s recent focus has remained on beefing up its U.S. infrastructure, Eli Lilly has for the second time this week made moves to raise capacity for its medicines overseas, and once again in Asia. 

The company on Thursday unveiled a 20 billion Japanese yen (nearly $126 million) expansion at its Seishin plant in Kobe, Japan, where Lilly’s local unit plans to install a fresh production line and add a new warehouse by 2028, according to a Japanese-language press release (PDF). 

Lilly did not clarify which drugs the expansion will support, although Nikkei Asia reported on March 12 that the project will bolster manufacturing of medicines for diabetes and obesity. 

The Seishin plant was established in 1981 and currently boasts a headcount of around 315 employees, serving as Lilly’s lone in-house production facility in Japan, according to the release. 

Aside from the new manufacturing line and storage space, Lilly said the investment will promote digitalization and process optimization at the plant to help supply the Japanese market. 

Citing “increasing demand” in the country, Lilly noted that “it is important for us to respond quickly and flexibly to future supply expansions.”

The company pointed out that it previously invested 7 billion yen (around $44 million) at the Seishin facility between 2022 and 2025, which paved the way for new automated device sorting machines, quality testing lab improvements, a new factory building and a fresh packaging line. 

“This additional investment was made in response to the need for further expansion of our supply capacity,” Lilly said of the latest outlay. 

The plant currently occupies a footprint of 23,000 square meters (247,570 square feet) and is primarily involved in analytical testing, inspection and packaging of Lilly products, according to the company’s announcement. 

With its local partner Mitsubishi Tanabe, Lilly has in recent years launched its dual GIP/GLP-1 med tirzepatide across both diabetes and obesity (PDF) indications in Japan, and the company also won approval for its Alzheimer’s disease med Kisunla in the country back in 2024. 

Lilly’s Japan outlay comes on the heels of a major $3 billion investment in the company’s manufacturing operations in China, where the pharma giant has pledged to set up local production for oral solid drugs, and in particular its GLP-1 pill for obesity orforglipron, which is under regulatory review in multiple parts of the world. 

The project, which will play out over a decade, will also see Lilly work with multiple local manufacturing partners, with the first named being Beijing-based CDMO Pharmaron. 

The Indianapolis pharma has also recently committed to a $500 million investment in South Korea. Instead of manufacturing, the money is meant to attract clinical trials to the country, while also support opening an incubator as part of the Lilly Gateway Labs.

Back in the U.S., Eli Lilly has committed to multiple high-profile plant builds in recent months, most recently with plans for a $3.5 billion injectables and device facility in Pennsylvania. Prior to that, the company telegraphed new manufacturing sites in Virginia, Texas and Alabama. 

Those investments have arrived amid a spate of similar U.S. moves by Big Pharma companies looking to navigate the Trump administration’s pharmaceutical import tariff threats. 

Free Training

Source link

Oregon Growers Keeps its Food Manufacturing Local


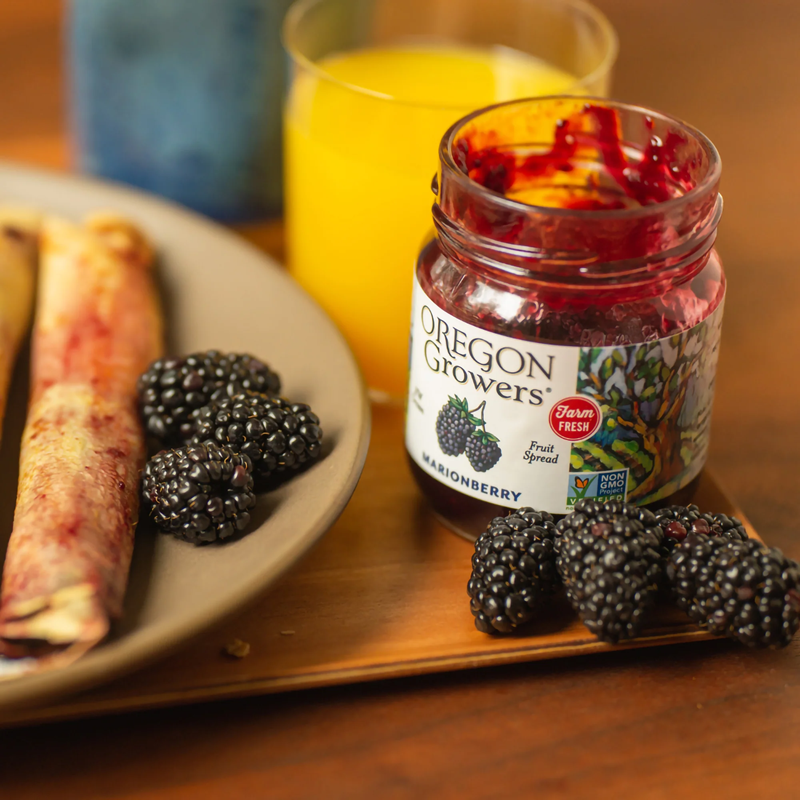
Oregon Growers’ flagship Marionberry Jam fruit spread. | Photo courtesy Oregon Growers

This company makes a truly Pacific Northwest product, from orchard to jar.

In Oregon’s Hood River Valley, fruit isn’t just grown; it’s part of the region’s identity. Orchards line the hillsides, family farms stretch across generations and the harvest has long been tied to the local economy.

Oregon Growers was built around that reality.

Founded in 2003 by Dave Gee, the company started with a simple goal: Capture the bounty of the Hood River Valley and turn it into something people could enjoy year-round. Working directly with nearby farms and orchards, Oregon Growers began producing jams, fruit butters and other specialty foods made from the region’s harvest.

More than two decades later, that same approach still defines the business.

Built on Local Agriculture, and Made in Oregon

To better understand how the company operates I spoke with Lisa Schlecht, who handles wholesale customer service and sales support there, about its approach to local sourcing, domestic production and long-standing partnerships with growers.

 Oregon Growers’ products are “farm direct,” Schlecht explained. “Their quality and great taste is the direct result of the exceptional fruit we use. We seek out the growers who not only produce the best-tasting fruit, but who also use sustainable growing practices.”

The company’s manufacturing footprint is just as local as its sourcing, according to Schlecht. Oregon Growers operates three production facilities in Oregon, where the fruit is turned into finished products. Keeping production close to home allows the company to maintain quality control, manage food safety closely and build long-term partnerships with growers.

It also means the economic impact stays local. When Oregon Growers buys fruit from nearby farms and produces its goods in-state, it supports jobs and business activity across the region, whether it’s in agriculture or in production and distribution.

The Realities of Domestic Supply Chains

Like many U.S.-based manufacturers, Oregon Growers faces challenges when it comes to maintaining a fully domestic supply chain.

Availability and pricing can be unpredictable, particularly in agriculture where harvests vary year to year. Competing on cost with imports can also put pressure on companies trying to keep sourcing and production in the United States.

Even so, Oregon Growers continues to prioritize American-grown ingredients and regional partnerships, choosing consistency, quality and community impact over the lowest possible cost.

Why It Matters

For Oregon Growers, producing food in the United States isn’t just a logistical decision, it’s a reflection of what the company values.

Keeping sourcing and production domestic helps support sustainable growing practices, strengthens local economies and results in products the company believes are higher quality. It also contributes to a more stable and resilient food system at a time when global supply chains can be unpredictable.

For consumers, those choices show up in the product itself.

If there’s one product that captures the company’s roots it’s the Marionberry Jam fruit spread, its flagship jam and a staple of Oregon agriculture. (My personal favorite!)

It’s a simple product, but it tells a larger story: one about American farms, domestic food production and the value of keeping both close to home.

Oregon Growers is a reminder that manufacturing in the United States doesn’t just happen on factory floors. It also happens in kitchens, canneries and production facilities that turn local crops into finished goods, supporting farmers, workers and communities along the way.

The Alliance for American Manufacturing does not receive a commission from purchases made through the above links, nor was the organization or author paid for favorable coverage.

Labeling Note: This story is intended to highlight companies that support American jobs and that make great products in the United States. We rely on the companies listed to provide accurate information regarding their domestic operations and their products. Each company featured is individually responsible for labeling and advertising their products according to applicable standards, such as the Federal Trade Commission’s “Made in USA” standard or California’s “Made in USA” labeling law. We do not review individual products for compliance or claim that because a company is listed in the guide that their products comply with specific labeling or advertising standards. Our focus is on supporting companies that create American jobs.

For more on the Federal Trade Commission’s standards for “Made in USA” claims and California’s “Made in USA” labeling law, please also read this guest post by Dustin Painter and Kristi Wolff of Kelly Drye & Warren, LLP.

Free Training

Source link

US public transit manufacturing in new APTA maps


US public transit manufacturing is the focus of new research from the American Public Transportation Association (APTA). The research shows how federal public transport spending connects thousands of suppliers across the United States. Those suppliers help build rail vehicles and buses.

US public transit manufacturing in new APTA mapsAPTA

APTA says in its bus manufacturing schematic that roughly 77 percent of federal transit funding goes to private-sector businesses. It says that spending supports manufacturing activity and family-wage jobs nationwide. Also, the association has published updated bus and rail manufacturing schematics.

These visuals show how the network works. They also show where components are produced. In addition, they identify the states involved in making different parts for trains and buses.

Don’t miss…Paris metro line 8 automatic control system goes to Alstom

APTA schematics trace the public transport supply chain

According to the research, more than 3,000 suppliers in over 1,700 communities across all 50 states are involved in public transport vehicle production. The diagrams show that components are sourced from multiple states before final assembly into buses or rail cars.

For example, the supply chain for fuel systems used in both buses and trains includes facilities in California, Indiana, Michigan, North Carolina, Nebraska, Ohio, South Carolina and Texas. Meanwhile, the schematics show that transit manufacturing spans multiple states. They also show that bus and rail vehicle production depends on a broad supplier base.

Federal public transit funding and the manufacturing network

APTA says the visuals are intended to show the scale of the transport manufacturing supply chain. They also show its links to workers in many parts of the country. At the same time, the organisation is urging lawmakers to maintain federal investment in the next surface transportation legislation. It says the schematics could help policymakers understand how transit funding affects local economies.

US public transit manufacturing in new APTA mapsAPTA

The diagrams come out of a year-long research effort led by APTA’s policy development and research team. Separately, the team worked with external partners. It gathered nationwide data on transit manufacturing suppliers. Still, the work did not stop there. The team then analysed the dataset. It identified suppliers and mapped where particular components are produced.

Additional APTA materials are still to come

The findings have been condensed into schematic form. They provide a visual summary of the sector’s manufacturing footprint. In addition, APTA expects to unveil two more schematics at its upcoming APTA Legislative Conference in Washington, D.C.

These will focus on bus maintenance facilities and rail stations. For example, they will extend the analysis beyond vehicle production. They are intended to cover additional parts of the public transport system.

News on railway transport, industry, and railway technologies from Railway Supply that you might have missed:

Find the latest news of the railway industry in Eastern Europe, the former Soviet Union and the rest of the world on our page on Facebook, Twitter, LinkedIn, read Railway Supply magazine online.
Place your ads on webportal and in Railway Supply magazine. Detailed information is in Railway Supply media kit

Free Training

Source link

Auto groups urge Trump to keep Chinese carmakers out of US | WKZO | Everything Kalamazoo


By David Shepardson

WASHINGTON, March 13 (Reuters) – Major auto trade groups urged the U.S. government to keep Chinese carmakers out of the country, according to a letter seen by Reuters, potentially complicating President Donald Trump’s planned summit with Chinese ​President Xi Jinping.

The groups raised “serious concerns about China’s ongoing efforts to dominate global ‌automotive manufacturing and to gain access to the U.S. market. These actions pose a direct threat to America’s global competitiveness, national security, and automotive industrial base.”

The five groups representing automakers, car dealers and parts manufacturers called for maintaining a 2025 Commerce Department cybersecurity regulation that effectively keeps nearly all Chinese vehicles ‌out ​of the U.S. market.

The Chinese embassy in Washington rejected ⁠the criticism, saying Chinese-made cars are ⁠popular globally “not by using so-called ‘unfair practices’ but by emerging from the fierce market competition with technological innovation and superb quality. China’s door has been open to global auto companies, including US auto companies who have fully shared in the dividends ​of China’s big market.”

The auto industry letter also criticized Canada’s announcement it would allow some Chinese vehicles into its market.

Trump is expected to visit China from March 31, ⁠as the world’s two biggest economies seek to ⁠maintain the stability that has characterized their relations since late last ​year, after a bruising period marked by Trump’s tariffs and China’s chokehold on rare earths ​exports.

“We also strongly urge the Administration to reject any attempt by Chinese ‌manufacturers to circumvent these existing restrictions by establishing production facilities in the U.S.,” said the letter, dated Thursday, from the Alliance for Automotive Innovation, the National Automobile Dealers Association, Autos Drive America, the American Automotive Policy Council and MEMA, the Vehicle Suppliers Association.

“The market ⁠distortions and risks to the auto industry in the U.S. are fundamentally the same whether these vehicles are imported or produced domestically,” it said.

In January, Trump said he was open ⁠to Chinese automakers building vehicles ‌in the United States. “If they want to come in and ⁠build a plant and hire you and hire your friends and ​your neighbors, ‌that’s great, I love that,” he told the Detroit Economic ​Club.

In December, ⁠the Alliance for Automotive Innovation, which represents General Motors, Ford, Toyota Motor, Volkswagen, Hyundai, Stellantis and other major automakers, said “China poses a clear and present threat to the auto industry in the U.S.” and urged Washington to prevent Chinese government-backed automakers and battery manufacturers from opening U.S. manufacturing plants.

(Reporting by David Shepardson and Parth Chandna; Editing by Alan Barona, Anna ​Driver and William Mallard)

Free Training

Source link

USPTO Expands Discretionary Framework


Key Takeaways

  • The USPTO has formally expanded its discretionary framework. As of March 11, the Director will consider U.S. manufacturing footprint and small business status when deciding whether to institute IPR and PGR proceedings, for cases where the patent owner’s discretionary brief deadline has not yet passed.
  • The Director is now weighing domestic investment and supply chain footprint, a shift that embeds real-economy policy considerations into institution decisions and could influence close cases.
  • Petitioners and patent owners alike should build an early evidentiary record on U.S. manufacturing activity and small business eligibility and integrate those facts into their overall discretionary narrative.

USPTO Director John A. Squires issued a short policy memorandum on March 11 adding U.S. manufacturing footprint and small business status as explicit considerations in the Director’s discretionary analysis of whether to institute inter partes review (IPR) and post-grant review (PGR) proceedings.

This update is best understood as the next incremental step in the post‑2025 discretionary institution framework — a framework that has moved well beyond “classic” Fintiv timing/overlap questions and now routinely incorporates broader reliance, efficiency and policy considerations. While the March 11 memo is not a wholesale recalibration of discretionary denials, it gives petitioners a new hook for potentially surviving discretionary denials and may signal a slight shift in the pendulum toward granting more petitions. 

What Changed on March 11

Director Squires announced that, when deciding whether to institute IPRs/PGRs, the Director will consider:

  1. The extent to which products accused of infringement in a parallel proceeding are manufactured in the United States or are related to investments in American manufacturing operations;
  2. The extent to which the patent owner’s competing products are manufactured in the United States; and
  3. Whether the petitioner is a small business that has been sued for infringement of the patent at issue.

The memo also adds practical guidance on what counts as U.S. manufacturing/investment and how small business status will be evaluated:

  • The Director will look beyond final assembly to include U.S.-made components and situations where products made in the U.S. are sent abroad for further processing.
  • For method claims, the “relevant product” is the device used to carry out the method (e.g., a computer for a method of operating a computer).
  • For “small business,” the Director will consider facts the parties raise, including SBA size standards and 37 C.F.R. § 1.27(a) (reduced-fee eligibility).

The memorandum applies to IPRs and PGRs where the patent owner discretionary brief due date has not yet elapsed.

Why These New Factors Matter in the Bigger Discretionary Picture

Discretionary institution decisions are now functioning as a policy gatekeeper, not merely a docket-management tool tethered to parallel litigation schedules. The changes from March 2025 and October 2025 centralized institution decisions at the Director level and expressly broadened the set of discretionary considerations to include settled expectations, changes in law, expert reliance and macro-level policy interests (economic, public health, national security). 

The March 11 memo is notable because it connects “investment” to the real economy, not just litigation timing or the passage of time. Historically, “investment” in the discretionary context often meant (i) court/party investment in a parallel proceeding (Fintiv factor 3) and (ii) reliance-type “settled expectations” that the Director has increasingly treated as meaningful once a patent has been in force for years (often argued around a six‑year benchmark). 

Now, the Director is explicitly inviting parties to brief a different kind of investment: domestic manufacturing operations and supply-chain footprint. That is a meaningful rhetorical and strategic shift, even if it will often operate as a “plus factor” rather than a standalone dispositive rule.

Finally, the memo reinforces a reality PTAB practitioners have been living with since 2025: discretionary outcomes are increasingly driven by case-specific factual showings made early, on a tight briefing schedule, and often in an environment where routine institution decisions may come as summary notices. The practical consequence is that discretionary briefing is becoming more like a mini-record-building exercise — and manufacturing footprint / small business status are exactly the type of issues that can swing outcomes when the Director views a case as otherwise close.

Practical Guidance: How to Brief this Effectively

For patent owners:

  • Develop a clean evidentiary record on U.S. manufacturing of your competing products: where assembly occurs, where key components are made and what “further processing” occurs outside the U.S. (if any). The memo signals the Director will look beyond final assembly.
  • If the accused products are imported or largely manufactured abroad, consider whether the record supports framing the dispute as one where AIA review would disproportionately benefit entities without U.S. manufacturing investment, a theme the memo expressly highlights.
  • For method claims, be explicit about the relevant device/product used to perform the method and where that device is manufactured.

For petitioners (especially operating companies):

  • If you have U.S. manufacturing operations, or are making concrete U.S. manufacturing investments, do not assume the Director will “find” that story without help. Put it in the discretionary record with supporting evidence.
  • If you qualify as a small business, say so early and substantiate it (SBA size standards and reduced-fee eligibility are explicitly referenced).
  • If you do not have a strong U.S. manufacturing footprint, anticipate that the patent owner may raise this memo offensively. Consider whether other discretionary factors (e.g., Fintiv timing, stipulations, strong merits, or changes-in-law arguments) need to be more thoroughly developed than in prior years. 

For both sides:

  • Treat this as an additional layer on top of existing discretionary themes, not a replacement. The Director’s discretionary process is explicitly holistic and considers existing PTAB precedent plus other circumstances the parties raise. 
  • Expect the other side to seek leverage from supply chain ambiguity (“assembled here, components there”) — so declarations and documentary support matter.

Free Training

Source link

GE Aerospace to invest $18M at Batesville facility


GE Aerospace to invest $18M at Batesville facility

Published 11:42 am Friday, March 13, 2026

GE Aerospace announced plans to invest $1 billion in its U.S. manufacturing sites and suppliers in 2026, including $18 million at its facility in Batesville.

The investment will fund new and upgraded production equipment and tooling to expand ceramic matrix composite component manufacturing, along with additional inspection equipment and facility improvements. Ceramic matrix composite engine parts are about one-third the weight of traditional metal components and can withstand temperatures up to 500 degrees higher.

“What we make in Batesville goes a long way in helping power the newest narrowbody and widebody engines around the world, and this investment allows us to deliver for our customers, U.S. manufacturing, and the region,” said Matt Shambaugh, site leader for GE Aerospace in Batesville.

The Batesville site plays a key role in ramping up production of the CFM LEAP engine used on narrowbody aircraft and also produces components for widebody aircraft. Over the past three years, GE Aerospace has announced plans to invest more than $40 million in the Batesville facility.

The company also plans to hire 5,000 workers across the United States this year. More than 30 positions are currently open at the Batesville site.

Free Training

Source link

Agriculture and Manufacturing Leaders Urge Renewal of USMCA


Agriculture and Manufacturing Leaders Urge Renewal of USMCA | American Ag Network

2429570432

Mozilla/5.0 (Windows NT 10.0; Win64; x64) AppleWebKit/537.36 (KHTML, like Gecko) Chrome/58.0.3029.110 Safari/537.3

e5bc6f5c03d1355cadf58ee9c1ff3663049093ee

1

Free Training

Source link

U.S. Launches Major Trade Investigation into Global Manufacturing Overcapacity | 2026 – News and Statistics


Mar 12, 2026

According to SupplyChainDive, the United States has initiated an investigation into the manufacturing policies of multiple nations to evaluate potential structural excess capacity and its effects on domestic industries. The Office of the U.S. Trade Representative is conducting this Section 301 probe, which includes China, the European Union, Singapore, Switzerland, Norway, Indonesia, Malaysia, Cambodia, Thailand, Korea, Vietnam, Taiwan, Bangladesh, Mexico, Japan, and India.

The investigation will assess possible supply and demand imbalances, policies affecting wages, and barriers to market access. The USTR filing indicates that key trading partners have developed manufacturing capacity that exceeds both domestic and global demand incentives, leading to overproduction, persistent trade surpluses, and underutilized facilities.

Sectors identified as currently experiencing overcapacity and excessive production include automobiles, electronics, processed food, and semiconductors. The filing specifically cited electric vehicle production in China as surpassing demand, noting one manufacturer’s expanding distribution and production networks abroad. USTR Jamieson Greer stated that overproduction by trading partners displaces existing U.S. domestic production or prevents new U.S. manufacturing investment and expansion.

The agency will open a docket for public comments on March 17, with a hearing scheduled for May 5. This investigation adds to a series of Section 301 probes started in the last year. Following a Supreme Court ruling in February that eliminated a broad set of tariffs installed last year, Greer said the U.S. would launch these investigations on an accelerated schedule, with an expectation they could be completed within the next five months.

Trade analysts note that if the investigation concludes that foreign industrial policies are unreasonable or distort trade, the U.S. could respond with tariffs. The current administration has previously used Section 301 investigations to review trading practices of other nations, some of which resulted in levies.

  1. 1. INTRODUCTION

    Making Data-Driven Decisions to Grow Your Business

    1. REPORT DESCRIPTION
    2. RESEARCH METHODOLOGY AND THE AI PLATFORM
    3. DATA-DRIVEN DECISIONS FOR YOUR BUSINESS
    4. GLOSSARY AND SPECIFIC TERMS
  2. 2. EXECUTIVE SUMMARY

    A Quick Overview of Market Performance

    1. KEY FINDINGS
    2. MARKET TRENDS This Chapter is Available Only for the Professional EditionPRO
  3. 3. MARKET OVERVIEW

    Understanding the Current State of The Market and its Prospects

    1. MARKET SIZE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. CONSUMPTION BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. MARKET FORECAST TO 2035
  4. 4. MOST PROMISING PRODUCTS FOR DIVERSIFICATION

    Finding New Products to Diversify Your Business

    1. TOP PRODUCTS TO DIVERSIFY YOUR BUSINESS
    2. BEST-SELLING PRODUCTS
    3. MOST CONSUMED PRODUCTS
    4. MOST TRADED PRODUCTS
    5. MOST PROFITABLE PRODUCTS FOR EXPORT
  5. 5. MOST PROMISING SUPPLYING COUNTRIES

    Choosing the Best Countries to Establish Your Sustainable Supply Chain

    1. TOP COUNTRIES TO SOURCE YOUR PRODUCT
    2. TOP PRODUCING COUNTRIES
    3. TOP EXPORTING COUNTRIES
    4. LOW-COST EXPORTING COUNTRIES
  6. 6. MOST PROMISING OVERSEAS MARKETS

    Choosing the Best Countries to Boost Your Export

    1. TOP OVERSEAS MARKETS FOR EXPORTING YOUR PRODUCT
    2. TOP CONSUMING MARKETS
    3. UNSATURATED MARKETS
    4. TOP IMPORTING MARKETS
    5. MOST PROFITABLE MARKETS
  7. 7. PRODUCTION

    The Latest Trends and Insights into The Industry

    1. PRODUCTION VOLUME AND VALUE: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. PRODUCTION BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  8. 8. IMPORTS

    The Largest Import Supplying Countries

    1. IMPORTS: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. IMPORTS BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. IMPORT PRICES BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  9. 9. EXPORTS

    The Largest Destinations for Exports

    1. EXPORTS: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    2. EXPORTS BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
    3. EXPORT PRICES BY COUNTRY: HISTORICAL DATA (2012–2025) AND FORECAST (2026–2035)
  10. 10. PROFILES OF MAJOR PRODUCERS

    The Largest Producers on The Market and Their Profiles

  11. 11. COUNTRY PROFILES

    The Largest Markets And Their Profiles

    This Chapter is Available Only for the Professional Edition
    PRO

    1. 11.1

      United States

      • Market Size
      • Production
      • Imports
      • Exports
    2. 11.2

      China

      • Market Size
      • Production
      • Imports
      • Exports
    3. 11.3

      Japan

      • Market Size
      • Production
      • Imports
      • Exports
    4. 11.4

      Germany

      • Market Size
      • Production
      • Imports
      • Exports
    5. 11.5

      United Kingdom

      • Market Size
      • Production
      • Imports
      • Exports
    6. 11.6

      France

      • Market Size
      • Production
      • Imports
      • Exports
    7. 11.7

      Brazil

      • Market Size
      • Production
      • Imports
      • Exports
    8. 11.8

      Italy

      • Market Size
      • Production
      • Imports
      • Exports
    9. 11.9

      Russian Federation

      • Market Size
      • Production
      • Imports
      • Exports
    10. 11.10

      India

      • Market Size
      • Production
      • Imports
      • Exports
    11. 11.11

      Canada

      • Market Size
      • Production
      • Imports
      • Exports
    12. 11.12

      Australia

      • Market Size
      • Production
      • Imports
      • Exports
    13. 11.13

      Republic of Korea

      • Market Size
      • Production
      • Imports
      • Exports
    14. 11.14

      Spain

      • Market Size
      • Production
      • Imports
      • Exports
    15. 11.15

      Mexico

      • Market Size
      • Production
      • Imports
      • Exports
    16. 11.16

      Indonesia

      • Market Size
      • Production
      • Imports
      • Exports
    17. 11.17

      Netherlands

      • Market Size
      • Production
      • Imports
      • Exports
    18. 11.18

      Turkey

      • Market Size
      • Production
      • Imports
      • Exports
    19. 11.19

      Saudi Arabia

      • Market Size
      • Production
      • Imports
      • Exports
    20. 11.20

      Switzerland

      • Market Size
      • Production
      • Imports
      • Exports
    21. 11.21

      Sweden

      • Market Size
      • Production
      • Imports
      • Exports
    22. 11.22

      Nigeria

      • Market Size
      • Production
      • Imports
      • Exports
    23. 11.23

      Poland

      • Market Size
      • Production
      • Imports
      • Exports
    24. 11.24

      Belgium

      • Market Size
      • Production
      • Imports
      • Exports
    25. 11.25

      Argentina

      • Market Size
      • Production
      • Imports
      • Exports
    26. 11.26

      Norway

      • Market Size
      • Production
      • Imports
      • Exports
    27. 11.27

      Austria

      • Market Size
      • Production
      • Imports
      • Exports
    28. 11.28

      Thailand

      • Market Size
      • Production
      • Imports
      • Exports
    29. 11.29

      United Arab Emirates

      • Market Size
      • Production
      • Imports
      • Exports
    30. 11.30

      Colombia

      • Market Size
      • Production
      • Imports
      • Exports
    31. 11.31

      Denmark

      • Market Size
      • Production
      • Imports
      • Exports
    32. 11.32

      South Africa

      • Market Size
      • Production
      • Imports
      • Exports
    33. 11.33

      Malaysia

      • Market Size
      • Production
      • Imports
      • Exports
    34. 11.34

      Israel

      • Market Size
      • Production
      • Imports
      • Exports
    35. 11.35

      Singapore

      • Market Size
      • Production
      • Imports
      • Exports
    36. 11.36

      Egypt

      • Market Size
      • Production
      • Imports
      • Exports
    37. 11.37

      Philippines

      • Market Size
      • Production
      • Imports
      • Exports
    38. 11.38

      Finland

      • Market Size
      • Production
      • Imports
      • Exports
    39. 11.39

      Chile

      • Market Size
      • Production
      • Imports
      • Exports
    40. 11.40

      Ireland

      • Market Size
      • Production
      • Imports
      • Exports
    41. 11.41

      Pakistan

      • Market Size
      • Production
      • Imports
      • Exports
    42. 11.42

      Greece

      • Market Size
      • Production
      • Imports
      • Exports
    43. 11.43

      Portugal

      • Market Size
      • Production
      • Imports
      • Exports
    44. 11.44

      Kazakhstan

      • Market Size
      • Production
      • Imports
      • Exports
    45. 11.45

      Algeria

      • Market Size
      • Production
      • Imports
      • Exports
    46. 11.46

      Czech Republic

      • Market Size
      • Production
      • Imports
      • Exports
    47. 11.47

      Qatar

      • Market Size
      • Production
      • Imports
      • Exports
    48. 11.48

      Peru

      • Market Size
      • Production
      • Imports
      • Exports
    49. 11.49

      Romania

      • Market Size
      • Production
      • Imports
      • Exports
    50. 11.50

      Vietnam

      • Market Size
      • Production
      • Imports
      • Exports
  12. LIST OF TABLES

    1. Key Findings In 2025
    2. Market Volume, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    3. Market Value: Historical Data (2012–2025) and Forecast (2026–2035)
    4. Per Capita Consumption, by Country, 2022–2025
    5. Production, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    6. Imports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    7. Imports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    8. Import Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    9. Exports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    10. Exports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    11. Export Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
  13. LIST OF FIGURES

    1. Market Volume, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    2. Market Value: Historical Data (2012–2025) and Forecast (2026–2035)
    3. Consumption, by Country, 2025
    4. Market Volume Forecast to 2035
    5. Market Value Forecast to 2035
    6. Market Size and Growth, By Product
    7. Average Per Capita Consumption, By Product
    8. Exports and Growth, By Product
    9. Export Prices and Growth, By Product
    10. Production Volume and Growth
    11. Exports and Growth
    12. Export Prices and Growth
    13. Market Size and Growth
    14. Per Capita Consumption
    15. Imports and Growth
    16. Import Prices
    17. Production, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    18. Production, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    19. Production, by Country, 2025
    20. Production, In Physical Terms, by Country: Historical Data (2012–2025) and Forecast (2026–2035)
    21. Imports, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    22. Imports, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    23. Imports, In Physical Terms, By Country, 2025
    24. Imports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    25. Imports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    26. Import Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    27. Exports, In Physical Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    28. Exports, In Value Terms: Historical Data (2012–2025) and Forecast (2026–2035)
    29. Exports, In Physical Terms, By Country, 2025
    30. Exports, In Physical Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    31. Exports, In Value Terms, By Country: Historical Data (2012–2025) and Forecast (2026–2035)
    32. Export Prices, By Country: Historical Data (2012–2025) and Forecast (2026–2035)

Free Training

Source link