US manufacturing expansion continues in April despite Iran war


This year’s US manufacturing expansion extended into April even as the Iran war drove input prices sharply higher.

The Institute for Supply Management’s gauge of prices paid for manufacturing inputs climbed for a fourth straight month to a four-year high of 84.6, according to data released Friday.

The group’s measure of overall factory activity held steady at 52.7, matching the highest level since 2022. Readings above 50 indicate growth.

Military conflict in the Middle East and the effective closure of the Strait of Hormuz have disrupted supply chains around the world, driving up the cost of oil and other materials like aluminum and helium. Higher gasoline and diesel prices have also made shipping products more expensive.

Thirteen manufacturing industries reported growth in April, led by textile mills, nonmetallic mineral products and primary metals. Three industries indicated a contraction.

Sustained inflationary pressures may spur manufacturers to hike prices too, which could ultimately lead to higher costs for consumer goods. Data out Thursday showed the Federal Reserve’s preferred gauge of inflation jumped in March by the most since 2022.

The ISM report showed new orders picked up in April as production growth decelerated. A measure of supplier deliveries rose to the highest level since 2022, with the longer lead times likely a result of war-related disruptions.

Select ISM Industry Comments

“Demand for manufactured goods is trending higher versus last year; however, geopolitical uncertainty and rising oil and diesel prices continue to weigh on demand. Many customers are exercising caution and remain in a wait-and-watch mode.” — Transportation Equipment

“Geopolitical risk, especially in the Middle East, as it pertains to commodity and energy markets remains a concern and is being monitored by the business. Supply chain risk concerns pertaining to increased cost and transit time for rerouted shipments due to conflict in the Red Sea, Strait of Hormuz and Suez Canal.” — Transportation Equipment

“Continuing fluctuation in US tariffs as well as market constraints for certain materials are affecting our current business.” — Computer and Electronic Products

“All products tied to crude, polyethylene resin or energy (liquified natural gas) have seen multiple increase spikes tied to the Iran crisis and market supply inflation.” — Chemical Products

“Revenues are very strong. However, price increases are similar to a few years ago with the supply chain crisis. All imports from China are up 15 percent to 25 percent, which is impossible for us to absorb or to fully pass along.” — Chemical Products

“General uncertainty over the total impact of the U.S.-Iran war. Have not yet started to see the full impact of fuel increases but are aware they are coming.” — Machinery

“Business levels have been decent this year, in line with the same period last year and improved from the second half of 2025. However, higher cost pressures are impacting margins.” — Fabricated Metal Products

“Our business remains strong and stable, but there are a lot of concerns in the geopolitical arena. If the Iran conflict persists, the impact on market pricing and supply continuity could be extreme. Electronics component market remains very volatile (pricing and continuity) based on AI.” — Miscellaneous Manufacturing

The group’s gauge of employment fell to a four-month low, indicating factory headcount continued to shrink. The government’s April employment report is scheduled to be released May 8.

“Among panelists, 60% indicated that managing head counts remains the norm at their companies as opposed to hiring, and of those managing head counts, 34% are using layoffs and 43% using attrition or not backfilling positions,” Susan Spence, chair of the ISM Manufacturing Business Survey Committee, said in a statement.

— By Jarrell Dillard

Free Training

Source link

Novartis finalizes US manufacturing and R&D expansion plan with seventh new facility


Real-time Estimate


Cboe Europe


07:06:01 2026-04-30 am EDT

5-day change

1st Jan Change

115.28 CHF

+1.71%

Intraday chart for Novartis AG

-1.12%

+4.91%

Published on 04/30/2026
at 07:00 am EDT

Dow Jones

(MORE TO FOLLOW) Dow Jones Newswires

April 30, 2026 07:00 ET (11:00 GMT)

Dow Jones logo
© Dow Jones –
2026

DurationAuto.2 months3 months6 months9 months1 year2 years5 years10 yearsMax.

PeriodDayWeek

Chart Novartis AGLogo Novartis AG
Novartis AG is one of the world’s leaders in the design, manufacturing, and marketing of pharmaceutical products. Net sales break down by therapeutic area as follows:

– oncology (30.9%);

– immunology (18.9%);

– cardiovascular, renal and metabolic diseases (16.4%);

– neuroscience (11%).

The remaining net sales (22.8%) are from contract manufacturing of pharmaceutical products.

At the end of 2025, Novartis AG had over 31 production sites worldwide.

Net sales are distributed geographically as follows: Switzerland (2.6%), Europe (28.1%), the United States (42.8%), Asia/Africa/Australasia (19.8%), Canada and Latin America (6.7%).

Trader

Trader

This super rating is the result of a weighted average of the rankings based on the following ratings: Valuation (Composite), EPS Revisions (4 months), and Visibility (Composite). We recommend that you carefully review the associated descriptions.

Investor

Investor

This super composite rating is the result of a weighted average of the rankings based on the following ratings: Fundamentals (Composite), Valuation (Composite), EPS Revisions (1 year), and Visibility (Composite). We recommend that you carefully review the associated descriptions.

Global

Global

This composite rating is the result of an average of the rankings based on the following ratings: Fundamentals (Composite), Valuation (Composite), Financial Estimates Revisions (Composite), Consensus (Composite) and Visibility (Composite). The company must be covered by at least 4 of these 5 ratings for the calculation to be carried out. We recommend that you carefully review the associated descriptions.

Quality

Quality

This composite rating is the result of an average of rankings based on the following ratings: Returns (Composite), Profitability (Composite) and Quality of Financial Reporting (Composite), and Financial Health (Composite). The company must be covered by at least 2 of these 3 ratings for the calculation to be performed. We recommend that you carefully read the associated descriptions.

ESG MSCI

ESG MSCI

The MSCI ESG score assesses a company’s environmental, social, and governance practices relative to its industry peers. Companies are rated from CCC (laggard) to AAA (leader). This rating helps investors incorporate sustainability risks and opportunities into their investment decisions.

SellConsensusBuy

Last Close Price

143.45USD

Average target price

153.80USD

Spread / Average Target

+7.21%

Quarterly revenue – Rate of surprise

Indices
Europe

America

Asia

Download from Apple Store

OUR EXPERTS ARE HERE FOR YOU

Monday – Friday 9am-12pm / 2pm-6pm GMT + 1

MarketScreener, Stock Market Live
Legal information
|
Cookie settings
|
MarketScreener Blog
|
About us
|
Copyright © 2026 Surperformance SAS. All rights reserved.

Stock quotes are provided by Factset, Morningstar and S&P Capital IQ

Select your edition

All financial news and data tailored to specific country editions

Free Training

Source link

AbbVie CEO Leads US$1.4bn Manufacturing Expansion


AbbVie is investing £1.1bn (US$1.4bn) in a 185-acre pharmaceutical manufacturing campus in Durham, North Carolina, marking the company’s largest capital investment to date. The decision represents a significant strategic move by the pharmaceutical giant to expand its US manufacturing footprint into a new region.

The campus will integrate advanced manufacturing and laboratory technologies as well as AI to support the production of immunology, neuroscience and oncology medicines. AbbVie expects the facility to create 734 jobs, including engineers, scientists, manufacturing operators and laboratory technicians.

The first phase of construction will include small volume parenteral drug product manufacturing facilities, next-generation laboratories, a warehouse, administrative offices and employee wellness facilities. Small volume parenterals are sterile injectable pharmaceutical products with volumes typically less than 100ml, including vials, prefilled cartridges and prefilled syringes containing medicines for injection or infusion.

Free Training

Source link

US Battery Manufacturing Expansion Surges Ahead


The modern energy storage sector operates through complex production networks where manufacturing capacity development frequently outpaces immediate market absorption. This phenomenon reflects broader industrial scaling patterns where initial overcapacity serves as infrastructure foundation for future demand expansion. Understanding these capacity-demand imbalances provides insight into strategic positioning within rapidly evolving technology markets.

Current U.S. battery manufacturing expansion demonstrates this dynamic through unprecedented facility construction rates and investment flows. Manufacturing infrastructure development now exceeds traditional forecasting models, creating strategic opportunities for industry participants while reshaping global supply chain architectures.

Analyzing Manufacturing Capacity Growth Trajectories

Battery manufacturing infrastructure in the United States has undergone dramatic transformation since 2024, with production capabilities expanding from minimal grid storage capacity to comprehensive domestic supply sufficiency. Industry data reveals systematic capacity building across multiple technology platforms and geographic regions.

Grid Storage Production Capacity Evolution:

• 2024 baseline: 70 GWh annual production capacity across limited facility networks

• 2025 expansion: 145 GWh capacity through foreign investment integration

• 2026 projections: 280 GWh capacity representing 300% growth over two years

• 2027 targets: 421.5 GWh projected capacity with mature supply chain networks

This expansion timeline represents one of the fastest manufacturing scale-ups in modern industrial history. The Centre on Global Energy Policy documented cost reduction mechanisms driving this growth, noting production cost decreases of up to 30 percent through federal incentive structures.

Manufacturing facility diversity has expanded from single-cell suppliers to comprehensive production ecosystems. Current supplier networks include 10 module assembly operations and projected expansion to 11 suppliers by 2027, indicating market maturation beyond initial foreign investment phases.

Regional Manufacturing Distribution:

Geographic Region
Primary Facilities
Investment Value
Technology Focus

Great Lakes Corridor
Michigan, Ohio operations
$15+ billion
LFP battery cells

Southeast Hub
Georgia, Tennessee plants
$20+ billion
Module assembly

Southwest Expansion
Texas, Arizona facilities
$8+ billion
System integration

Furthermore, grid storage manufacturing differs fundamentally from electric vehicle battery production through chemistry selection, form factor requirements, and cycle life optimization. Lithium iron phosphate (LFP) chemistry dominates stationary storage applications due to enhanced safety profiles and extended operational lifespans compared to traditional lithium-ion formulations used in transportation applications.

When big ASX news breaks, our subscribers know first

Federal Policy Architecture and Investment Incentives

Manufacturing investment decisions respond directly to policy framework structures that reduce operational costs while providing market access advantages. The Inflation Reduction Act created competitive positioning for domestic manufacturing through multiple incentive mechanisms.

Cost Reduction Framework Analysis:

• Manufacturing tax credits: Direct production cost reduction averaging 30%

• Local content requirements: Driving foreign manufacturers toward domestic operations

• Supply chain incentives: Encouraging component sourcing diversification

• System integration benefits: Favoring vertically integrated manufacturing approaches

Investment data from S&P Global indicates the United States imported over $100 billion in batteries and components since 2021, with approximately 50% sourced from Chinese suppliers. This import dependency created strategic vulnerabilities that federal policy mechanisms aim to address through domestic capacity building.

Korean manufacturing companies responded most aggressively to these incentive structures, committing approximately $20 billion toward U.S. battery manufacturing expansion between 2025 and 2029. Benchmark Minerals projects Korean producers will contribute over 40% of domestic capacity growth during this period.

Tariff Strategy Implementation

Current tariff policies create protective mechanisms for domestic manufacturers while maintaining supply chain relationships with essential material suppliers. However, the broader trump tariffs impact demonstrates how trade policy complexity emerges from geographic concentration of critical materials processing.

Trade policy complexity emerges from geographic concentration of critical materials processing. Chinese suppliers control approximately 85% of graphite processing, 60% of lithium processing, and 75% of cathode material production, creating strategic supply chain chokepoints despite domestic manufacturing growth.

Leading Manufacturing Scale-Up Companies

LG Energy Solution Strategic Pivot

LG Energy Solution executed the most significant facility transformation in the sector through its Holland, Michigan operation conversion from electric vehicle to grid storage production. The company invested $1.4 billion to establish dedicated lithium iron phosphate production lines with 16.5 GWh current capacity.

This strategic pivot reflects market condition adaptation as electric vehicle demand growth slowed while grid storage requirements accelerated. LG projects capacity expansion to 50 GWh by end-2026, representing 200% growth within 18 months.

Facility Conversion Process:

• Technology transfer: Adapting EV battery lines for stationary storage chemistry

• Equipment modification: Retrofitting assembly systems for different form factors

• Workforce retraining: Developing expertise in grid storage applications

• Quality control systems: Implementing cycle life testing protocols

Korean Investment Leadership

Samsung SDI and SK Innovation complement LG’s expansion through coordinated facility development across multiple states. Combined Korean investment exceeds $20 billion, establishing comprehensive supply chain networks from raw material processing through finished system assembly.

Geographic distribution strategies focus on transportation cost minimisation and workforce availability. Tennessee, Georgia, and Michigan emerged as preferred locations due to existing automotive manufacturing expertise and logistical infrastructure.

Domestic Manufacturing Champions

Tesla Energy operates the largest single-site battery manufacturing facility in California with 40 GWh annual Megapack production capacity. The company’s vertical integration strategy encompasses battery cells, module assembly, and complete system manufacturing under unified operational control.

In addition, Stryten Energy pursues multi-chemistry diversification across lead-acid, lithium-ion, and vanadium redox flow battery technologies. The company operates 11 existing facilities with planned 10 GW capacity addition across military, grid storage, and transportation market segments.

Supply Chain Dependency Analysis

Critical Material Import Vulnerabilities

Despite domestic manufacturing expansion, essential component dependencies persist across multiple supply chain stages. International Energy Agency analysis identifies production capacity and technical expertise concentration in Asian markets as primary supply security risks.

Material Category
Primary Suppliers
Dependency Level
Alternative Sources

Active materials
China (75%)
High
Korea, Japan limited

Precursor chemicals
China (80%)
Critical
Australia, Chile emerging

Processing equipment
China, Korea (70%)
High
European alternatives

Quality control systems
Korea, Japan (60%)
Medium
Domestic development

Raw material processing represents the most significant supply chain vulnerability. Graphite processing remains 85% concentrated in Chinese facilities, while cathode material production shows similar geographic concentration patterns.

This vulnerability underscores the importance of critical minerals energy security considerations that influence manufacturing expansion decisions.

Midstream Manufacturing Gaps

Active material production capabilities require substantial technology transfer and equipment investment to establish domestic alternatives. Current domestic facilities focus primarily on final assembly operations rather than chemical processing stages.

Korea and Japan offer the only significant alternative supplier bases for essential components, but capacity limitations restrict their ability to substitute for Chinese supply chains completely. This creates strategic dependencies despite domestic final assembly capabilities.

Supply Chain Resilience Strategies:

• Inventory management: Maintaining strategic material stockpiles

• Supplier diversification: Developing alternative source relationships

• Technology licensing: Acquiring processing expertise through partnerships

• Vertical integration: Establishing domestic chemical processing capabilities

Technical Manufacturing Challenges

Production Scaling Complexities

Rapid facility expansion creates multiple technical challenges from equipment installation through workforce development. Manufacturing quality control systems require extensive optimisation during capacity ramp phases.

Grid storage applications demand different performance characteristics than electric vehicle batteries, necessitating specialised production processes. Cycle life optimisation becomes paramount for stationary applications where batteries may operate for 20+ years with daily charging cycles.

Technology Transfer Difficulties

Adapting Asian manufacturing processes to American operational environments requires substantial modification of equipment, procedures, and quality control systems. Korean and Japanese production methodologies developed for different labour markets and regulatory frameworks.

Key Technical Challenges:

• Yield optimisation: Achieving target production rates during startup phases

• Quality consistency: Maintaining performance specifications across production volumes

• Process automation: Integrating robotic systems with manual operations

• Material handling: Managing hazardous chemical processing safely

Consequently, workforce development represents a critical bottleneck as battery manufacturing requires specialised technical skills unavailable in traditional automotive or electronics manufacturing. Training programmes require 6-12 months for technician certification in electrochemical processing operations.

Market Demand and Capacity Balance

Supply-Demand Projections

Current manufacturing expansion trajectories suggest domestic production capacity will exceed demand requirements by 2026. This overcapacity scenario creates both opportunities for export market development and risks of industry consolidation.

Energy storage demand growth of 21% annually supports continued capacity expansion, driven primarily by renewable energy integration requirements and data centre backup power needs. However, production capacity growth exceeds 50% annually, creating potential oversupply conditions.

2026 Market Dynamics Analysis:

• Domestic production capacity: 280 GWh annually

• Projected U.S. demand: 200 GWh combined grid and transportation

• Export potential: 40 GWh available for international markets

• Market concentration: 10-12 major suppliers competing for market share

Regional manufacturing clusters enable transportation cost optimisation and supply chain coordination. The Southeast corridor development creates comprehensive ecosystem from raw material processing through finished system delivery.

Demand Growth Drivers

Data centre expansion represents the fastest-growing battery storage market segment as artificial intelligence and cloud computing requirements drive backup power needs. These applications require different battery specifications than traditional grid storage installations.

Furthermore, renewable energy integration continues as the primary demand driver, but growth rates may moderate as grid infrastructure adapts to higher renewable penetration levels. This creates uncertainty for long-term capacity planning.

The next major ASX story will hit our subscribers first

Geopolitical Manufacturing Implications

China Relationship Management

Maintaining supplier relationships with Chinese material producers while developing domestic manufacturing creates complex diplomatic and commercial challenges. Tariff policies must balance protective measures with supply chain continuity.

Chinese companies retain control over critical processing technologies and raw material access despite American manufacturing expansion. This creates ongoing strategic vulnerabilities that policy mechanisms alone cannot eliminate.

Interestingly, the chinese battery recycling breakthrough offers potential collaboration opportunities that could benefit American manufacturing sustainability goals.

International Partnership Development

Korean technology transfer represents the most successful international collaboration model, combining foreign expertise with domestic manufacturing capacity. This partnership approach enables rapid technology acquisition while building domestic capabilities.

Japanese collaboration focuses on advanced materials and precision manufacturing equipment, complementing Korean strengths in battery chemistry and production processes. European partnerships emphasise recycling and circular economy technologies.

Strategic Competition Dynamics:

• Technology leadership: Competing for next-generation battery innovations

• Market access: Securing international customer relationships

• Supply chain control: Developing alternative material sourcing networks

• Manufacturing cost: Achieving competitive production economics

Investment Patterns and Market Evolution

Project Development Timeline

Major facility investments require 2-3 years from announcement to production startup, creating predictable capacity addition schedules. Current project pipelines suggest continued expansion through 2028-2029 before growth rates moderate.

Significant Facility Investments:

Company
Location
Investment
Capacity
Timeline

Toyota-Panasonic
Liberty, NC
$14 billion
75 GWh
2025-2027

LG Energy Solution
Holland, MI
$1.4 billion
50 GWh
2025-2026

AESC
Tennessee
$2.8 billion
30 GWh
2026-2027

Samsung SDI
Multiple states
$5 billion
45 GWh
2025-2028

Cancelled Projects Analysis

Financial constraints and market uncertainty resulted in approximately $8 billion in cancelled investments, including KorePower Arizona ($1.2 billion) and Freyr Georgia ($2.6 billion) projects. These cancellations reflect more realistic demand forecasting and financing challenges.

Project cancellations concentrated amongst smaller companies lacking established customer relationships or proven manufacturing expertise. Larger corporations with automotive industry partnerships demonstrated greater project completion rates.

Financial Market Assessment

Manufacturing investment patterns reveal preference for companies with proven production expertise and established customer relationships. Financial markets increasingly scrutinise demand projections and competitive positioning before committing development capital.

Equity valuations reflect manufacturing capacity expansion but discount future profitability due to competitive pressures and potential oversupply scenarios. Debt financing requires demonstrated customer contracts and operational cash flow projections.

Technology Evolution and Manufacturing Adaptation

Next-Generation Technology Development

Solid-state battery development threatens current lithium-ion manufacturing investments through superior energy density and safety characteristics. However, manufacturing complexity and cost structures delay commercial deployment until 2030 or later.

Alternative chemistry development includes sodium-ion and iron-air storage systems targeting different market segments than traditional lithium-ion applications. These technologies require different manufacturing equipment and processes.

Manufacturing Process Innovation

Automation advancement reduces labour costs while improving quality consistency, particularly important for achieving competitive production economics. Robotic systems handle hazardous materials processing and precision assembly operations.

Energy efficiency improvements lower production carbon footprints, increasingly important for regulatory compliance and customer requirements. Manufacturing facilities integrate renewable energy sources to minimise operational emissions.

Moreover, american battery recycling initiatives complement manufacturing expansion by providing sustainable material sourcing options.

Technology Differentiation Strategies:

• Cycle life optimisation: Extending battery operational lifespans

• Energy density improvements: Reducing system footprint requirements

• Safety enhancements: Minimising fire and thermal runaway risks

• Cost reduction: Achieving competitive pricing through scale economies

Modular facility design enables rapid capacity adjustments based on market demand fluctuations. This flexibility becomes increasingly important as demand forecasting uncertainty persists across different application segments.

Industry Structure and Consolidation Dynamics

Overcapacity Scenario Planning

Potential industry consolidation by 2027-2028 reflects manufacturing capacity exceeding demand absorption rates. Smaller producers lacking scale economies or customer relationships face greatest financial pressure during market adjustment periods.

Market share concentration amongst 3-5 major producers appears likely as competitive pressures eliminate marginal operations. Korean companies and established American manufacturers demonstrate strongest competitive positioning.

This trend aligns with broader industry consolidation dynamics affecting resource-intensive manufacturing sectors.

Competitive Differentiation Requirements

Technology advancement becomes essential for maintaining market position as basic manufacturing capabilities commoditise. Companies invest heavily in research and development to create sustainable competitive advantages.

Vertical integration strategies provide cost advantages and supply chain control but require substantial capital investment. Companies must balance integration benefits against financial requirements and operational complexity.

Export Market Development

North American integration through Canadian and Mexican partnerships creates natural export opportunities for excess production capacity. Trade agreements facilitate cross-border manufacturing and distribution networks.

Global competitiveness requires achieving cost parity with Asian manufacturers while maintaining quality and delivery advantages. American manufacturers leverage proximity to customers and supply chain responsiveness as competitive factors.

The U.S. battery manufacturing expansion represents a fundamental restructuring of global energy storage supply chains, transforming America from import-dependent to potentially export-capable within five years. However, persistent dependencies on Asian supply chains for critical materials and continued manufacturing cost challenges suggest ongoing strategic vulnerabilities.

Success in this transformation requires maintaining technological competitiveness while developing alternative supply sources and adapting to evolving demand patterns. The US battery manufacturing capacity industry’s rapid expansion creates both unprecedented opportunities for energy independence and significant risks from potential overcapacity scenarios that could reshape competitive dynamics across the entire sector.

Want to capitalise on the next energy storage breakthrough?

Discovery Alert’s proprietary Discovery IQ model delivers real-time alerts on significant ASX mineral discoveries, including critical battery materials like lithium, graphite, and rare earth elements powering the global energy transition. Begin your 14-day free trial at Discovery Alert today and position yourself ahead of the market as energy storage demand creates unprecedented opportunities for strategic mineral discoveries.

Free Training

Source link

Apple adds US manufacturing partners with $400M expansion


Listen to the article

This audio is auto-generated. Please let us know if you have feedback.

Dive Brief:

  • Apple recently added four semiconductor companies to its American Manufacturing Program, including Bosch, Cirrus Logic, TDK and Qnity Electronics.
  • The Cupertino, California-based company on Thursday said it plans to spend $400 million through 2030 in support of its new partners as they produce materials and components in the United States for Apple products sold around the world.
  • As part of the expansion, longtime Apple supplier TDK has agreed to make iPhone sensors in the U.S. for the first time. The advanced sensors support camera stabilization, among other features. Apple is also working with Bosch on producing circuits that support crash detection, activity tracking and elevation.

Dive Insight:

Apple’s expansion is part of a larger $600 billion commitment to U.S. manufacturing and innovation. It adds to a growing number of companies participating in Apple’s American Manufacturing Program as uncertainty fueled by tariffs and international conflict spur domestic investments.

Initial members such as Amkor, GlobalWafers and Corning are already starting to implement their plans with Apple. The technology giant has redirected all of its iPhone and Apple Watch cover glass production to Corning’s Harrodsburg, Kentucky, facility. It also recently announced plans to bring Mac mini production to Houston later this year.

GlobalWafers has begun wafer production at its Sherman, Texas, factory. Meanwhile, Amkor has broken ground on its advanced packaging and test facility in Peoria, Arizona, where Apple is set to be its first and largest customer.

“We’re proud to partner with even more companies to produce critical components and cutting-edge materials for our products right here in the U.S,” Apple CEO Tim Cook said in a statement.

In addition to new partnerships with TDK and Bosch, Apple is working with Cirrus Logic to establish new semiconductor process technologies at GlobalFoundries’ facility in Malta, New York. Apple said this collaboration will enable Cirrus Logic to develop “mixed-signal solutions” for its applications, including advanced integrated circuits for Face ID systems.

Qnity Electronics and HD Microsystems have also agreed to provide materials and technologies that enhance semiconductor manufacturing through artificial intelligence and high-performance computing. Qnity, a Dupont spinoff, recently formed in November and opened a 385,000-square-foot chips facility in Newark, Delaware, to meet rising AI demand.

Apple also said it has served nearly 150 businesses through dozens of free, in-person training sessions and virtual programming. It is scheduled to host its first Spring Forum from April 30 to May 1 at Michigan State University in East Lansing, Michigan.

Free Training

Source link

After China outlay, Lilly plugs $126M into Japan manufacturing plant expansion


While much of the company’s recent focus has remained on beefing up its U.S. infrastructure, Eli Lilly has for the second time this week made moves to raise capacity for its medicines overseas, and once again in Asia. 

The company on Thursday unveiled a 20 billion Japanese yen (nearly $126 million) expansion at its Seishin plant in Kobe, Japan, where Lilly’s local unit plans to install a fresh production line and add a new warehouse by 2028, according to a Japanese-language press release (PDF). 

Lilly did not clarify which drugs the expansion will support, although Nikkei Asia reported on March 12 that the project will bolster manufacturing of medicines for diabetes and obesity. 

The Seishin plant was established in 1981 and currently boasts a headcount of around 315 employees, serving as Lilly’s lone in-house production facility in Japan, according to the release. 

Aside from the new manufacturing line and storage space, Lilly said the investment will promote digitalization and process optimization at the plant to help supply the Japanese market. 

Citing “increasing demand” in the country, Lilly noted that “it is important for us to respond quickly and flexibly to future supply expansions.”

The company pointed out that it previously invested 7 billion yen (around $44 million) at the Seishin facility between 2022 and 2025, which paved the way for new automated device sorting machines, quality testing lab improvements, a new factory building and a fresh packaging line. 

“This additional investment was made in response to the need for further expansion of our supply capacity,” Lilly said of the latest outlay. 

The plant currently occupies a footprint of 23,000 square meters (247,570 square feet) and is primarily involved in analytical testing, inspection and packaging of Lilly products, according to the company’s announcement. 

With its local partner Mitsubishi Tanabe, Lilly has in recent years launched its dual GIP/GLP-1 med tirzepatide across both diabetes and obesity (PDF) indications in Japan, and the company also won approval for its Alzheimer’s disease med Kisunla in the country back in 2024. 

Lilly’s Japan outlay comes on the heels of a major $3 billion investment in the company’s manufacturing operations in China, where the pharma giant has pledged to set up local production for oral solid drugs, and in particular its GLP-1 pill for obesity orforglipron, which is under regulatory review in multiple parts of the world. 

The project, which will play out over a decade, will also see Lilly work with multiple local manufacturing partners, with the first named being Beijing-based CDMO Pharmaron. 

The Indianapolis pharma has also recently committed to a $500 million investment in South Korea. Instead of manufacturing, the money is meant to attract clinical trials to the country, while also support opening an incubator as part of the Lilly Gateway Labs.

Back in the U.S., Eli Lilly has committed to multiple high-profile plant builds in recent months, most recently with plans for a $3.5 billion injectables and device facility in Pennsylvania. Prior to that, the company telegraphed new manufacturing sites in Virginia, Texas and Alabama. 

Those investments have arrived amid a spate of similar U.S. moves by Big Pharma companies looking to navigate the Trump administration’s pharmaceutical import tariff threats. 

Free Training

Source link

U.S. Department of War promotes defense manufacturing expansion


Key Points

  • United States Secretary of War Pete Hegseth concluded the first phase of the Arsenal of Freedom tour with visits to General Dynamics and L3Harris facilities in Arkansas promoting faster domestic defense production.
  • The Department of War used the nationwide tour to emphasize strengthening the U.S. defense industrial base and expanding workforce support tied to missile and advanced weapons manufacturing.

United States Secretary of War Pete Hegseth concluded the first phase of the Department’s nationwide “Arsenal of Freedom” tour on Feb. 27, 2026, with visits to defense industry facilities operated by General Dynamics and L3Harris in Camden, Arkansas, where he delivered remarks focused on expanding production capacity and accelerating weapons manufacturing.

The tour, organized by the United States Department of War, is intended to demonstrate federal support for the defense industrial base while urging industry and workforce leaders to increase output of military systems and modernize manufacturing practices supporting U.S. warfighters.

Speaking before more than 1,500 employees at the L3Harris facility, Hegseth highlighted the role of defense workers in sustaining military readiness.

– ADVERTISEMENT – CONTINUE READING BELOW –

“Thank you for being the backbone of our department and our great nation [and] for having the backs of our warfighters because what you build right here in Camden is absolutely central to the 21st-century arsenal of freedom,” Hegseth said.

He added that the technologies produced at the site directly support advanced weapons programs.

“The technology that you build for our missiles, interceptors and hypersonic weapons is what allows the War Department to achieve peace through strength, and that mission comes with a nonnegotiable mandate from the War Department [and] straight from the Resolute Desk and President [Donald J.] Trump,” he said.

According to remarks released during the visit, Hegseth emphasized innovation and faster production timelines as core priorities of the tour. He encouraged industry partners to increase manufacturing tempo while maintaining technological advancement across defense programs.

(Photo by Alexander Kubitza)

The secretary also addressed long-standing concerns about inefficiencies within the defense industrial base, arguing that production culture must shift toward faster delivery cycles. Praising L3Harris operations in Camden, he said the company had “set the pace” for industry performance through rapid production practices.

“For far too long, our defense and aerospace industry was a giant swamp, much like Washington. … Those companies moved at a snail’s pace, led by CEOs who cared more about their stock options and golden parachutes than delivering for those on the front lines,” Hegseth said.

He further criticized earlier trends toward outsourcing defense production overseas, stating that domestic manufacturing remains central to national security priorities.

“Well, let them tell that to these great workers and these great patriots at L3,” Hegseth said during the event.

According to the Department of War, the Arkansas stop marked the conclusion of a seven-and-a-half-week first phase of the Arsenal of Freedom tour, which began Jan. 5 with a visit to a shipyard in Newport News, Virginia. The tour included additional stops in Texas, California, Rhode Island, Maine, Missouri, Florida, and Colorado.

As part of each visit, Hegseth has administered enlistment oaths to new service members. During the Arkansas stop, he swore in 40 recruits, bringing the total number of enlistees participating in ceremonies during the tour to more than 260.

(Photo by Alexander Kubitza)

The Department said the enlistment ceremonies are intended to link industrial workforce contributions with military service, underscoring the connection between manufacturing capacity and operational readiness.

In practical military terms, the facilities visited in Camden contribute components and systems supporting missile production, interceptor technologies, and hypersonic weapon development. These systems form part of layered defense architectures designed to counter aerial threats and maintain deterrence capabilities.

The Arsenal of Freedom initiative draws its name from the historical “Arsenal of Democracy,” the large-scale industrial mobilization undertaken by the United States prior to and during World War II, when domestic manufacturing was expanded to supply military equipment to Allied forces.

Free Training

Source link

Apple’s Houston Expansion Puts U.S. Manufacturing And AI At Center Stage


  • Apple announced plans to expand its U.S. manufacturing footprint with a new campus in Houston focused on Mac mini production and AI server hardware, targeting a start date later in 2026.
  • The company outlined large investments in American manufacturing facilities, workforce training, and domestic sourcing of chips and components.
  • These moves are aimed at diversifying Apple’s supply chain in response to global geopolitical risks and concentrating more high value hardware production in the U.S.

For investors watching NasdaqGS:AAPL, this move ties directly into how the company builds and supports its core hardware and AI infrastructure. Apple’s shares recently closed at $272.95, with returns of 3.2% over the past week, 6.4% over the past month, and 13.4% over the past year. Over a longer stretch, the stock has delivered 83.3% over three years and 130.8% over five years.

This new Houston build out and broader U.S. supply chain push indicate that Apple is committing more capital and attention to where and how its devices and AI systems are produced. For investors, the key questions are how these manufacturing and training investments affect Apple’s cost structure, product reliability, and its role in U.S. chip and AI hardware ecosystems over time.

Stay updated on the most important news stories for Apple by adding it to your watchlist or portfolio. Alternatively, explore our Community to discover new perspectives on Apple.

NasdaqGS:AAPL Earnings & Revenue Growth as at Feb 2026NasdaqGS:AAPL Earnings & Revenue Growth as at Feb 2026

📰 Beyond the headline: 0 risks and 2 things going right for Apple that every investor should see.

For Apple, the Houston expansion is as much about control and resilience as it is about capacity. Shifting Mac mini and AI-server assembly into the U.S., while tying that into a $600b domestic supply-chain commitment, gives Apple more direct oversight of high value hardware tied to Apple Intelligence and its broader services ecosystem. It also tangibly responds to the geopolitical concerns around Taiwan and China that investors have been hearing about since at least 2023, without Apple needing to match the very heavy AI data-center spending seen at Microsoft, Alphabet, or Amazon. At the same time, more U.S. manufacturing can mean higher labor and compliance costs, so the key question is whether Apple’s scale and process discipline can offset that through efficiency and pricing.

How This Fits Into The Apple Narrative

  • The U.S. manufacturing push supports the narrative’s focus on supply-chain optimization, which aims to reduce tariff and geopolitical risk and support margin stability over time.
  • Bringing AI servers and Mac mini production onshore adds execution risk around cost control and yields, which could challenge assumptions that hardware and AI features will easily translate into higher margins.
  • The dedicated Advanced Manufacturing Center and wider supplier investments deepen Apple’s U.S. industrial footprint, an element not fully captured in the narrative’s emphasis on services and on-device AI as drivers of the story.

Knowing what a company is worth starts with understanding its story.
Check out one of the top narratives in the Simply Wall St Community for Apple to help decide what it’s worth to you.

The Risks and Rewards Investors Should Consider

  • ⚠️ Higher-cost U.S. production and complex AI-server builds could pressure hardware margins if Apple cannot offset expenses through pricing, mix, or efficiency gains.
  • ⚠️ Even with diversification, Apple remains exposed to China and Taiwan, so investors still face geopolitical and regulatory risk alongside the large U.S. commitments.
  • 🎁 A broader U.S. chip and manufacturing base, including suppliers like TSMC and Texas Instruments, may help Apple reduce single-region dependence and improve component security.
  • 🎁 Housing AI-server production closer to its data centers could support more reliable Apple Intelligence services, strengthening differentiation versus peers such as Samsung and Google hardware.

What To Watch Going Forward

From here, you will want to watch how quickly the Houston site ramps Mac mini and AI-server output, and whether Apple comments on any margin impact in future earnings calls. Progress on sourcing chips from U.S. facilities, along with utilization of the Advanced Manufacturing Center, will help show whether this shift is improving resilience rather than simply adding cost. It is also worth tracking how Apple positions these U.S. investments alongside its AI partnerships and on-device features as competition from Microsoft, Alphabet, and Samsung continues to evolve.

To ensure you’re always in the loop on how the latest news impacts the investment narrative for Apple, head to the
community page for Apple to never miss an update on the top community narratives.

This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.

New: Manage All Your Stock Portfolios in One Place

We’ve created the ultimate portfolio companion for stock investors, and it’s free.

• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks

Try a Demo Portfolio for Free

Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com

Free Training

Source link

Apple to bring Mac mini production to Houston in major US manufacturing expansion


Apple has announced a significant expansion of its Houston manufacturing operations, confirming that production of the Mac mini will move to the United States for the first time as part of a broader investment in advanced manufacturing and AI infrastructure.

The move will also see Apple expand AI server production at the Texas site and open a new Advanced Manufacturing Center later this year, initiatives that together are expected to create thousands of jobs.

Bringing Mac mini production Stateside

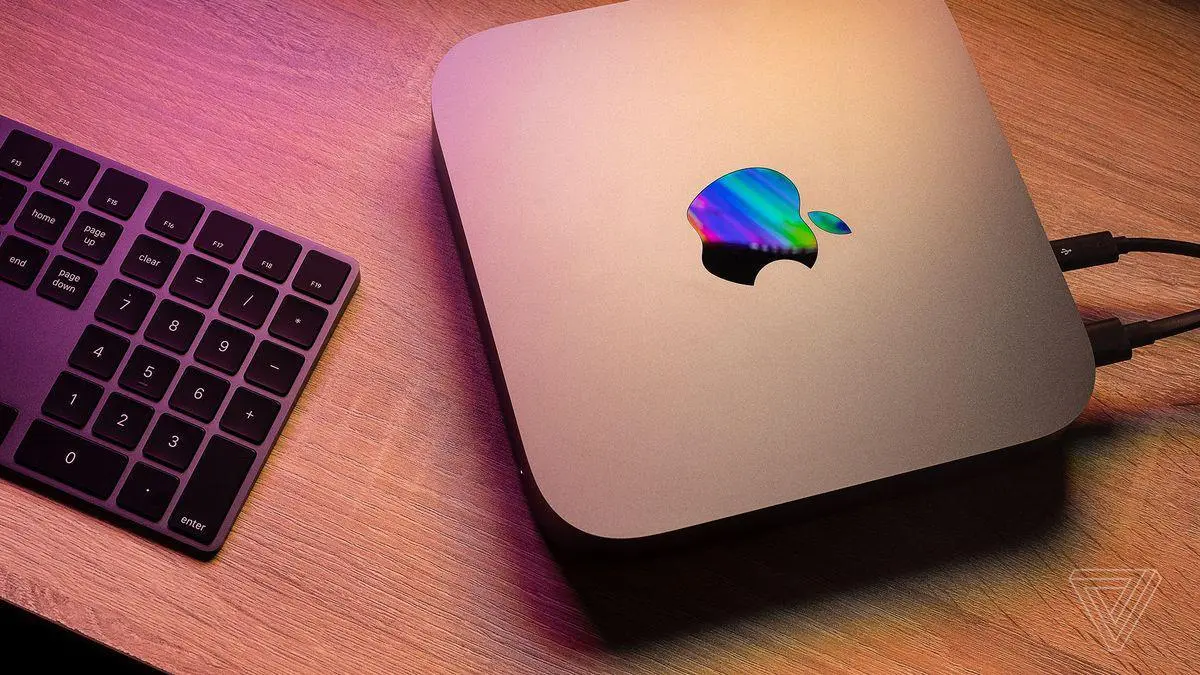
Apple said Mac mini manufacturing will begin later in 2026 at a new factory within its Houston campus, effectively doubling the site’s footprint. The compact desktop computer has been a core part of Apple’s product lineup for more than two decades, and the decision marks a notable shift in the company’s global manufacturing strategy.

According to Apple CEO Tim Cook, the investment reflects the company’s growing commitment to U.S. manufacturing capacity: “Apple is deeply committed to the future of American manufacturing, and we’re proud to significantly expand our footprint in Houston with the production of Mac mini starting later this year.”

The move follows a wider trend among technology firms seeking to diversify supply chains and expand domestic production capacity, particularly in high-value electronics manufacturing.

Expansion of AI server manufacturing

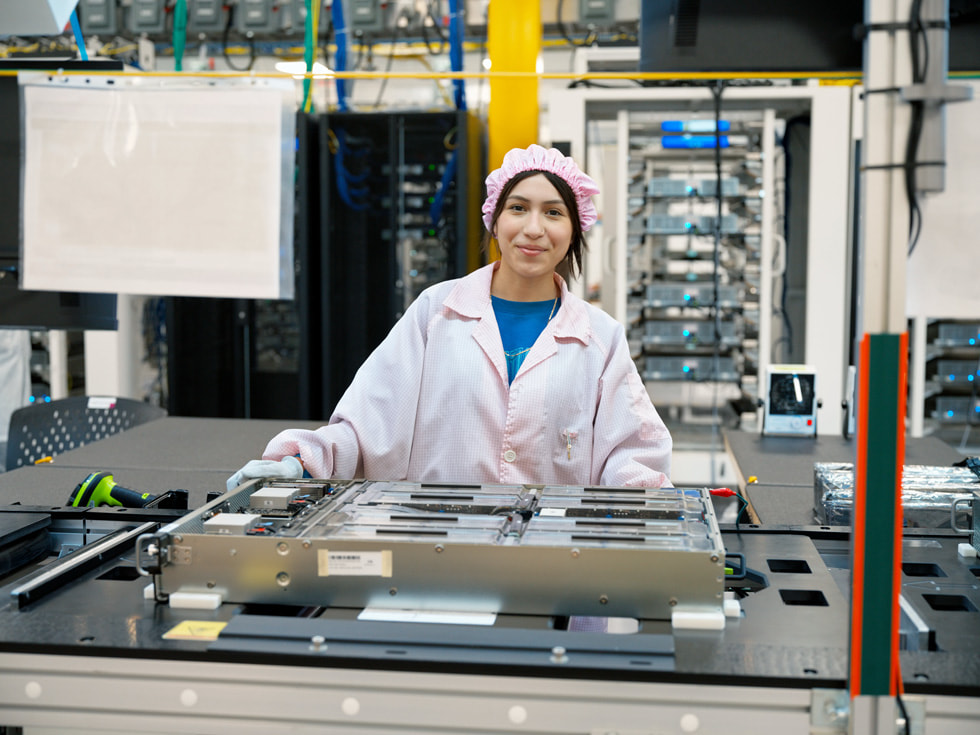
Alongside Mac mini production, Apple is ramping up output of advanced AI servers at the Houston site. The company began assembling servers there in 2025, with production already ahead of schedule.

Servers built in Houston—including logic boards produced onsite—are used in Apple data centres across the United States. The expansion reflects Apple’s growing investment in artificial intelligence infrastructure, an area that has become central to both consumer devices and cloud services.

Cook noted the accelerated rollout of AI server production as an early success for the site: “We began shipping advanced AI servers from Houston ahead of schedule, and we’re excited to accelerate that work even further.”

Investing in skills and workforce development

Beyond hardware production, Apple is also investing in workforce development with the launch of a 20,000-square-foot Advanced Manufacturing Center in Houston. The facility, currently under construction, will provide hands-on training in advanced manufacturing techniques.

The centre is expected to train students, supplier employees, and small- and medium-sized manufacturers in processes used in Apple’s own production lines. Apple engineers will lead training sessions designed to help U.S. manufacturers adopt new technologies and improve efficiency.

The company said the initiative aims to strengthen the domestic manufacturing ecosystem while building a pipeline of skilled workers.

Strategic implications for North American manufacturing

Apple’s expansion comes amid a broader push to localise manufacturing in North America, driven by supply-chain resilience concerns, geopolitical tensions, and government incentives.

Bringing Mac mini production to Houston signals that high-tech consumer electronics assembly—traditionally concentrated in Asia—may increasingly be split across multiple regions. Meanwhile, Apple’s investment in AI server production reflects surging demand for data-centre hardware as artificial intelligence applications expand.

For Houston, the project adds another high-profile technology manufacturing investment to the region’s growing industrial base.

A long-term commitment

Apple’s announcement highlights how technology companies are blending product manufacturing, infrastructure development, and workforce training into integrated investment strategies.

By combining Mac mini assembly, AI server production, and advanced manufacturing training, Apple is positioning Houston as a key node in its global supply chain—while signalling a deeper commitment to U.S. manufacturing capacity.

As reshoring momentum continues across North America, Apple’s move could encourage other electronics manufacturers to consider similar strategies, particularly for high-value or strategically important products.

Free Training

Source link

Apple to move part of Mac Mini production to US with Houston expansion


Apple Inc. will move part of its Mac Mini production to the United States, with assembly set to begin later this year at a Foxconn facility in north Houston, according to a Wall Street Journal report.

Apple Inc. will move part of its Mac Mini production to the United States, with assembly set to begin later this year at a Foxconn facility in north Houston, according to a Wall Street Journal report.

Apple will move some
production of its Mac Mini desktop computer ​to the U.S. from
Asia, with a new manufacturing ‌effort set to begin later this
year at ​a Foxconn facility in north Houston, ⁠The Wall Street
Journal reported on Monday.

The plan marks the iPhone maker’s most recent U.S.
investment, following its commitment announced ‌last August to
invest $600 billion in the U.S. over the next four years.

In May, ‌U.S. President Donald Trump had threatened Apple
with ‌a ⁠25% tariff on products manufactured overseas, a ⁠sharp
reversal from earlier policy when his administration had
exempted smartphones, computers and other electronics from
rounds of tariffs on Chinese imports.

The ​production for Mac ‌Mini will continue in Asia, its chief
operating officer Sabih Khan told WSJ, adding that the facility
will meet local demand as the U.S. assembly ‌line ramps up.

It was not immediately clear ​whether Apple plans to
scale down production in its Asia facilities. Apple did not
immediately ⁠respond to a Reuters request for comment.

The company feels more confident projecting long-term demand
for the Mac ‌Mini, which is more popular than the Mac Pro, Khan
added.

It is also expanding the Houston facility to include a new
training center for advanced manufacturing, according to the
report.

Apple has a mixed track record when it comes to following
through on ‌investment promises.

In 2019, for instance, Cook toured a Texas ​factory
with Trump that was promoted as a new manufacturing site.
However, the facility had ⁠been producing Apple computers since
2013 and Apple has since ⁠moved that production to Thailand.

Apple continues to manufacture most of its products,
including iPhones ‌and iPads, in Asia, primarily in China,
although it has shifted some production to Vietnam, Thailand ​and
India in recent years.

Published on February 24, 2026

Free Training

Source link