Duffy Scolds Ford Over Deals With China in Urging More American Manufacturing


Transportation Secretary Sean Duffy has warned Ford Motor Company about maintaining “questionable foreign alliances” with Chinese companies amid calls from the Trump administration to reshore its manufacturing operations.

In a recent letter to Ford CEO Jim Farley, Duffy derided the company’s recent deals with China-backed auto manufacturers, and said Ford “fails to act as [a] reliable partner” to the American public.

“The company’s recent strategic decisions paint a troubling picture of a foundational American brand actively intertwining its future with Chinese state-backed enterprises,” Duffy wrote in the letter sent Sept. 3 and released publicly Tuesday.

Ford pushed back sharply in a statement to NOTUS on Tuesday, calling Duffy’s letter an error-filled and “wrongheaded attempt to capture headlines.”

The company said it produces more vehicles in the United States and employs more American workers than any other automaker.

Ford has been under continued pressure from the White House to return to domestic supply chains and manufacturing, and recently announced it would relocate manufacturing operations of its Lincoln models from China to the United States by 2030.

Commerce Secretary Howard Lutnick recently celebrated the announcement as a tariff success, but Duffy asserted the four-year timeline “leaves an unacceptable, multi-year window of reliance on Chinese manufacturing while depriving skilled American workers of vital manufacturing jobs.”

Duffy went on to highlight Ford’s dependence on licensed technology from Chinese battery manufacturer Contemporary Amperex Technology Co., Limited — a company that appears on the Defense Department’s list of banned companies. He also criticized Ford over a new deal with Chinese automotive company Geely Auto to build zero-emission vehicles at a Ford factory in Spain.

Ford defended its arrangement with Chinese battery makers, saying its Michigan battery hub is owned and operated by Ford and can’t be classified as a foreign-owned manufacturing operation. The company said Duffy’s assessment of its operations in Spain are also fraught.

“Ford supports the Trump administration’s vision for advancing American innovation and manufacturing,” Ford’s response states. “Had Secretary Duffy reached out before issuing his letter to the press, we would have been happy to share more details about Ford’s U.S. commitment.”

Free Training

Source link

Bombardier highlights US manufacturing after President Trump threat | Corporate Jet Investor


Bombardier

There could be stormy weather ahead for Bombardier’s relations with the US government.

Bombardier has highlighted its commitment to business jet manufacturing in the US after President Donald Trump threatened to ban the sale of the company’s aircraft unless the firm relocated production to America.

Commenting on his social media platform Truth Social yesterday (September 7th), President Trump wrote: “NO MORE SELLING BOMBARDIER IN THE UNITED STATES!”. He added: “If they want our Market, they must build here and stop treating America like a ‘piggybank’.”

The president also claimed that more than half of Bombardier’s revenue comes from US customers and said Canada of imposing “unfair” restrictions on American customers.

Without naming President Trump, the manufacturer said in a statement: “Bombardier values its great partnership with American companies and its US employees. Our plan is to continue to invest in our people, our customers and the communities in which we operate across the country.”  

‘Clear winner’

The American aerospace industry is “a clear winner on trade and exports”, it said. “Aerospace is routinely one of the top export sectors for the United States and a continual trade surplus winner.” Bombardier contributed strongly to the sector, creating tens of thousands of jobs across the US, according to the manufacturer. 

The company highlighted its US workforce throughout the US, citing facilities in Kansas, Texas, Arizona, Florida, Connecticut, Illinois, Delaware, California, Washington D.C. and New Jersey. The business has an overall direct employment presence in more than 20 states and worked with about 2,800 American companies across 47 states. In total, the spends over $2.5bn with suppliers each year. Bombardier aircraft are built with American-made components such as engines, avionics and many more key systems provided by great American companies, it continued.

Grow its service network

Bombardier also highlighted plans to grow its defence activities as well as its service network and will, later this year, inaugurate a new facility in Fort Wayne, Indiana.  In August last year the manufacturer pledged to expand its service network throughout the US and hailed its new manufacturing facility in Moorpark, California as an “important move”, which showed its “cutting-edge innovation” and commitment to “high-quality jobs”.

President Trump’s post was made amid growing economic tensions between the two countries after he placed a 25% tax on Canadian cars and trucks, as well as taxes on Canadian steel, aluminium and lumber. Last month the president imposed new 50% tariffs goods on goods such as dairy, alcohol, hockey sticks and perfume. Canada has responded with counter tariffs of up to C$28bn ($20.24bn) on American products.

Read the manufacturer’s statement in full here and the president’s social media post here.

Meanwhile, the president’s Truth Social post concluded with the advice: “BUY AMERICAN. FLY ON AMERICAN AIRLINERS. ENJOY AMERICAN LIQUOR AND BEVERAGES. SAIL ON LAKE AMERICA. AMERICA FIRST!”

Free Training

Source link

‘Wings For The World’s Fastest Business Jet Are Made By American Workers’ — TradingView News


Bombardier Inc. (BDRBF) fired back Monday after President Donald Trump threatened to block sales of the Canadian planemaker’s jets in the United States, issuing a statement defending its American manufacturing footprint and thousands of U.S. jobs tied to its business-jet production.

Bombardier Highlights U.S. Economic Impact 

Trump posted on Truth Social that he would end Bombardier sales in the United States, saying the company’s products were not worth it.

“NO MORE SELLING BOMBARDIER IN THE UNITED STATES! Their products aren’t good enough! Over 50% of their revenue comes from the United States — They live off American Buyers, American Companies, American Airports, and American Service — All while Canada blocks our GREAT American Banks, and Companies, throughout the U.S.A. They even blocked Gulfstream Aerospace from doing business in Canada — Completely unjust and unfair!”

The Montreal-based manufacturer pushed back within hours, emphasizing its existing U.S. manufacturing operations. The company said its American operations support tens of thousands of jobs, both directly and through its supplier network. Bombardier class B stock slipped 0.6% last week, logging three straight weeks of losses.

Bombardier employs workers across more than 20 states, including Kansas, Texas, Arizona, Florida, Connecticut, Illinois, Delaware, California, New Jersey and Washington, D.C. Its U.S. operations work with roughly 2,800 domestic suppliers spanning 47 states. The company spends more than $2.5 billion annually with those businesses.

“Bombardier aircraft are built with American-made components such as engines, avionics and many more key systems provided by great American companies. Significantly, the wings for the world’s fastest business jet are made by American workers at Bombardier’s facility in Red Oak, Texas while crucial flight control components are made in Bombardier’s Los Angeles, California area facility.”

Canada Prepares New Tariffs On U.S. Goods 

The disagreement comes as trade tensions between the U.S. and Canada grow. Trump criticized Canada for restricting American banks and companies, while Canada prepares to respond to U.S. tariffs, raising fears of a broader trade war.

According to a Bloomberg report, Canada plans to place 15% to 50% tariffs on hundreds of U.S. products, starting Tuesday, as Prime Minister Mark Carney tries to strengthen Canada’s position in trade talks with the U.S. The tariffs would raise duties on many U.S. steel products to 50% from 25% and add new taxes on items such as motorcycles, cosmetics and cheese.

BDRBF Stock: Retail View

Meanwhile, on Stocktwits, retail sentiment around the stock jumped to ‘bullish’ from ‘bearish’ territory.

“They do build in the US… they are in Texas, California, Kansas, Connecticut, Florida and Indiana. At least 3000 American employees,” said one user in response to Trump’s latest post.

BDRBF stock has gained 34% year-to-date.

Free Training

Source link

US launches Foundry School to build advanced manufacturing workforce


The programme will train entrepreneurs, engineers, technicians, and industrial leaders through a 17-session advanced manufacturing curriculum.

The US launched the Foundry School on 3 September 2026 as a training programme for entrepreneurs, engineers, technicians, and industrial leaders to support the rebuilding of US manufacturing. Vice President J.D. Vance and Secretary of State Marco Rubio announced the programme at an event hosted by Under Secretary for Economic Affairs Jacob Helberg at the Donald J. Trump Institute of Peace.

Foundry School is being developed with Stanford University and seven other universities: Arizona State University, Georgia Institute of Technology, The Ohio State University, The Pennsylvania State University, the University of Kansas, Vanderbilt University, and Washington University in St. Louis. The programme will run 17 sessions across the eight campuses, with each session taught by founders and CEOs from advanced manufacturing enterprises in the United States and Pax Silica economies, including South Korea, Japan, Taiwan, and India.

The curriculum will be delivered in two phases. Seven regional sessions beginning in September 2026 will cover modern factory design, materials and supply chains, assembly-line engineering, plant economics, regulation and permitting, and workforce development at scale. A ten-session core programme at Stanford University beginning in January 2027 will cover advanced manufacturing capabilities including precision tooling, industrial automation, quality systems, new product introduction, digital manufacturing, capital equipment, energy, global site selection, and defence production.

Foundry School is a flagship initiative of Pax Silica, the Trump administration’s economic security partnership connecting governments, industry, and universities around critical supply chains and industrial capabilities underpinning the AI economy. The US Department of State estimates that American manufacturers will need 3.8 million skilled workers by 2033 across sectors including semiconductors, defence, and energy. The programme is intended to help close gaps in design and manufacturing capacity and connect students and workers directly with companies building and operating advanced manufacturing facilities.

Why does it matter?

Advanced manufacturing requires specialised technical and industrial skills as investment in areas such as semiconductors, energy, and defence expands. Bringing universities and industry leaders into a common training programme can connect workforce development with the practical requirements of manufacturing enterprises.

The programme also links skills development with industrial and economic security priorities. Its focus on both foundational and advanced manufacturing capabilities provides training across different stages of the manufacturing process, from factory design and supply chains to automation, digital manufacturing, and production.

Would you like to learn more about AI, tech, and digital diplomacy? If so, ask our Diplo chatbot!

Free Training

Source link

US manufacturing jobs rise by 16,000 in August


The US labour market added 162,000 nonfarm payroll jobs in August, while the unemployment rate was unchanged at 4.1 per cent, official data for September 4, 2026 showed, giving apparel and textile sourcing teams a fresh read on factory hiring, construction-linked capacity and wage pressure in a key consumer and supply market.

Manufacturing employment continued its upward trend with 16,000 jobs added in August and was up by 58,000 from a recent low in December 2025. Machinery manufacturing and fabricated metal product manufacturing each continued to trend up, adding 6,000 jobs, while construction changed little at 22,000 jobs added.

The US Bureau of Labor Statistics (BLS) said total nonfarm payroll gains in August were above the average monthly increase of 31,000 over the prior 12 months. Employment rose in food services and drinking places and local government education, while the information industry lost jobs.

US nonfarm payrolls rose by 162,000 in August, with manufacturing adding 16,000 jobs and construction up 22,000.
The unemployment rate held at 4.1 per cent, while labour force participation edged up to 61.6 per cent and part-time for economic reasons fell.
Average hourly earnings rose to $37.75, a wage signal for apparel and retail sourcing teams tracking US labour costs.

The BLS said the release draws on two monthly surveys: the household survey, which measures labour force status including unemployment by demographic characteristics, and the establishment survey, which measures nonfarm employment, hours and earnings by industry.

In the household survey, the number of unemployed people was little changed at 7.0 million. The unemployment rate for Asian workers declined to 3.2 per cent, the teenage rate edged up to 14.1 per cent, and jobless rates showed little change for adult men at 4.0 per cent, adult women at 3.5 per cent, White workers at 3.7 per cent, Black workers at 6.0 per cent and Hispanic workers at 4.8 per cent.

The number of long-term unemployed, defined as people jobless for 27 weeks or more, changed little at 1.9 million and accounted for 27.0 per cent of all unemployed people. The labour force participation rate edged up to 61.6 per cent but was down by 0.5 percentage point since January, while the employment-population ratio changed little at 59.1 per cent.

The number of people employed part time for economic reasons decreased by 414,000 to 4.4 million. The number of people not in the labour force who wanted a job changed little at 5.7 million; amongst them, 1.7 million were marginally attached to the labour force and 441,000 discouraged workers believed no jobs were available for them.

Employment showed little change in mining, quarrying, and oil and gas extraction; wholesale trade; retail trade; transportation and warehousing; financial activities; professional and business services; social assistance; and other services.

Average hourly earnings for all employees on private nonfarm payrolls rose by 10 cents, or 0.3 per cent, to $37.75 in August, and were up by 3.1 per cent over the year. Average hourly earnings of private-sector production and nonsupervisory employees rose by 11 cents, or 0.3 per cent, to $32.53.

The average workweek for all employees on private nonfarm payrolls edged up by 0.1 hour to 34.4 hours. In manufacturing, the average workweek edged up by 0.1 hour to 40.5 hours, while overtime was unchanged at 3.1 hours.

In a White House statement, spokesman Kush Desai said the US added 162,000 jobs in August, described as nearly triple economists’ expectations, and that the private sector had created more than one million jobs in President Donald J Trump’s second term.

The White House said federal employment remained at its lowest share of the workforce on record.

The White House also characterised the 16,000 manufacturing gain as the strongest monthly increase in three years and said manufacturers had added 58,000 jobs this year, driven by demand for pharmaceutical and defence production, data centre construction and semiconductor plants. It said factory construction jobs were up nearly 100,000 in President Trump’s second term and that private-sector workers’ average weekly earnings were up 3.7 per cent over the year.

The White House added that the labour force participation increased at its strongest level in almost a year, college graduate unemployment remained at 2.7 per cent, and Black unemployment posted a second monthly decline.

Fibre2Fashion News Desk (CG)

Free Training

Source link

Fabry-Perot Laser Diodes Market in the United States | Report – IndexBox


United States Fabry-Perot Laser Diodes Market 2026 Analysis and Forecast to 2035

Executive Summary

Key Findings

  • United States demand for Fabry-Perot laser diodes is projected to expand at a 6–9% compound annual rate from 2026 to 2035, driven by precision manufacturing, optical sensing, and datacom upgrade cycles.
  • Industrial automation and instrumentation currently represent roughly 40–50% of US consumption, with semiconductor precision manufacturing emerging as the fastest-growing application vertical at 8–12% annual growth.
  • The US market remains structurally import-dependent, with 60–75% of packaged devices sourced from overseas fabrication and assembly, creating meaningful supply-chain lead-time and inventory-cost exposure.

Market Trends

  • Wavelength-stabilized and high-power Fabry-Perot laser modules are gaining share over commodity bare-die components, supporting average selling prices in the $800–$3,000 range for premium configurations.
  • Replacement cycles in US industrial installed bases are lengthening toward 3–5 years as end users prioritize reliability and field-serviceability over upfront component cost.
  • Domestic integration activity is shifting toward module-level assembly and testing rather than epitaxial wafer fabrication, reflecting the economics of US labor costs and specialized quality-control requirements.

Key Challenges

  • Supply-chain concentration in Asia-Pacific epitaxial growth and wafer fabrication leaves US buyers exposed to 8–16 week lead times and freight-related cost volatility.
  • Price erosion of 3–5% annually for standard telecom-grade Fabry-Perot laser diodes pressures margins for distributors and integrators that compete on commodity specifications.
  • Export-control and technology-transfer compliance adds administrative overhead for US importers of advanced laser diodes, particularly for dual-use optical and sensing applications.

Market Overview

The United States Fabry-Perot laser diodes market operates as a specialized B2B component and module ecosystem rather than a consumer-driven category. Fabry-Perot laser diodes are edge-emitting semiconductor lasers that generate coherent light through a simple Fabry-Perot cavity, typically fabricated on gallium arsenide (GaAs) or indium phosphide (InP) substrates. These devices serve as cost-effective optical sources for short-to-medium reach datacom transceivers, industrial sensors, precision measurement instruments, medical diagnostic equipment, and semiconductor manufacturing tools.

Within the United States, demand is concentrated among OEM integrators, system designers, and maintenance organizations that require reliable, reproducible optical output at specific wavelengths—commonly 780 nm, 850 nm, 980 nm, 1064 nm, 1310 nm, and 1550 nm—with power levels ranging from milliwatt-class sensing applications to multi-watt industrial processing.

The market structure spans four distinct value layers: bare laser diode chips and discrete components; packaged laser diode modules with integrated optics and monitoring photodiodes; fully integrated optical subsystems; and consumables or replacement parts for installed equipment. US buyers typically procure through authorized distributors, specialty optical-component suppliers, and direct OEM relationships, with purchasing decisions driven by technical specifications—wavelength accuracy, spectral linewidth, output power stability, and operating lifetime—rather than brand recognition. The market is characterized by high engineering involvement, qualification testing, and long-term supply agreements, reflecting the critical role Fabry-Perot laser diodes play in downstream system reliability.

Market Size and Growth

The United States Fabry-Perot laser diodes market is best understood through growth-rate and segment-share signals rather than absolute revenue figures, given the fragmented nature of specialty optical component sales and the absence of a single consolidated reporting category. Demand is projected to grow at a 6–9% compound annual rate over the 2026–2035 forecast horizon, a pace that outpaces general industrial production growth but trails the more explosive expansion seen in coherent and tunable laser segments. This growth trajectory reflects steady adoption in industrial automation, gradual replacement of legacy optical sources in datacom infrastructure, and increasing penetration of Fabry-Perot laser diodes in compact sensing modules for environmental monitoring, autonomous vehicle lidar, and biomedical diagnostics.

Volume growth in the US market is closely correlated with capital expenditure cycles in semiconductor fabrication, optical network upgrades, and precision manufacturing. The 2026–2028 period is expected to show acceleration as US semiconductor fabs expand capacity and as industrial end users modernize optical inspection and alignment systems. By the early 2030s, growth is likely to moderate to the mid-single digits as the datacom upgrade cycle matures and as alternative laser architectures—particularly vertical-cavity surface-emitting lasers (VCSELs) and external-cavity designs—capture share in select applications. The relative forecast suggests the US market could expand by roughly 80–120% in unit terms between 2026 and 2035, with premium module segments growing faster than bare-chip commodity sales.

Demand by Segment and End Use

Demand segmentation in the United States Fabry-Perot laser diodes market follows both product architecture and application logic. By product type, discrete laser diode chips and low-cost packaged components account for the largest unit share, approximately 55–65% of US consumption, driven by high-volume OEM integration in datacom transceivers, barcode scanners, and compact optical sensors. Components and modules—packaged devices with integrated thermoelectric coolers, monitor photodiodes, and fiber pigtails—represent 25–35% of demand by value, reflecting higher engineering content and per-unit pricing.

Integrated systems, including turnkey optical sources for scientific and industrial instrumentation, constitute a smaller but growing share, while consumables and replacement parts contribute a stable recurring revenue stream tied to the installed base of US optical equipment.

By application, industrial automation and instrumentation dominate, representing an estimated 40–50% of US demand. This includes laser-based dimensioning sensors, optical encoders, spectroscopy systems, and machine-vision illumination. Electronics and optical systems account for another 20–30%, spanning datacom transceivers, test-and-measurement equipment, and consumer-electronics optical components. Semiconductor and precision manufacturing is the fastest-growing application, expanding at 8–12% annually, as Fabry-Perot laser diodes are deployed in wafer inspection, photolithography alignment, and laser-based metrology tools. OEM integration and maintenance demand rounds out the market, with replacement cycles of 3–5 years driving recurring purchases for industrial laser systems and laboratory instruments.

Prices and Cost Drivers

Pricing for Fabry-Perot laser diodes in the United States spans a wide range depending on wavelength, power, packaging, and qualification level. Commodity-grade bare die and low-power packaged components for consumer and datacom applications typically price between $50 and $500 per unit, with high-volume procurement achieving the lower end of this band. Industrial-grade modules with wavelength stabilization, fiber coupling, and hermetic sealing command $500–$2,000, while fully integrated subsystems with drive electronics and thermal management can reach $3,000 or more. Prices for standard telecom-grade Fabry-Perot laser diodes have experienced 3–5% annual erosion, driven by GaAs and InP wafer cost reductions, improved epitaxial growth yields, and competitive pressure from Asian suppliers.

Cost drivers in the US market are dominated by epitaxial wafer quality, packaging complexity, and testing requirements. Fabry-Perot laser diode performance—threshold current, slope efficiency, and lifetime—is fundamentally determined during epitaxial growth and wafer fabrication, making upstream input costs critical. US buyers face additional cost pressure from import logistics, customs clearance, and inventory carrying costs, particularly when maintaining safety stock to hedge against 8–16 week overseas lead times.

Energy costs for burn-in testing and reliability screening, which can run 100–500 hours per device lot, add meaningful cost for US integrators that perform incoming inspection. Labor costs for specialized optical assembly and test personnel in the United States are higher than in Asian manufacturing hubs, reinforcing the economic logic of importing packaged devices rather than performing domestic wafer-level fabrication.

Suppliers, Manufacturers and Competition

The competitive landscape for Fabry-Perot laser diodes in the United States is characterized by a mix of global semiconductor laser manufacturers, specialized optical component suppliers, and domestic module integrators. Recognized technology vendors—including established players in the laser diode space such as II-VI Incorporated (now part of Coherent), Lumentum Holdings, and Hamamatsu Photonics—are active in the US market through direct sales teams and authorized distribution networks.

Asian manufacturers, particularly Japanese and Chinese producers with strong epitaxial growth and wafer fabrication capabilities, supply a substantial portion of the bare chips and low-cost packaged devices consumed by US OEMs. European specialty suppliers also maintain a presence in the premium industrial and scientific segments, competing on wavelength accuracy and long-term reliability.

Competition in the US market is primarily technical rather than price-led. Buyers qualify suppliers based on optical performance, reliability data, and consistency across production lots, with qualification cycles of 6–18 months common in industrial and medical applications. This creates high switching costs and favors incumbents with established reliability track records. Domestic module integrators and value-added distributors compete by offering custom packaging, wavelength selection, burn-in testing, and just-in-time delivery—services that Asian wafer fabs typically do not provide directly to US end users.

The competitive intensity varies by segment, with commodity datacom components facing aggressive price competition while specialized industrial and scientific devices sustain premium pricing through differentiation and certification barriers.

Domestic Production and Supply

Domestic production of Fabry-Perot laser diodes in the United States exists but is concentrated in specialized, high-value segments rather than high-volume commodity manufacturing. The United States retains meaningful capability in epitaxial growth and wafer fabrication for advanced laser structures, particularly at research institutions, defense-oriented foundries, and specialty commercial producers serving aerospace, scientific, and medical applications.

However, the commercial-scale production of standard Fabry-Perot laser diodes for datacom and industrial sensing has largely migrated to Asia-Pacific fabrication facilities, where epitaxial growth capacity, wafer processing economics, and labor costs are more favorable. US domestic production is estimated to cover only 25–40% of total national consumption, with the balance supplied through imports.

The domestic supply model is therefore oriented around module-level assembly, testing, and system integration rather than wafer-level manufacturing. US facilities perform die-attach, wire bonding, optical alignment, hermetic sealing, and reliability screening, adding value through precision packaging and quality assurance that overseas wafer fabs do not provide. This domestic capability is strategically important for defense, aerospace, and medical applications where ITAR compliance, supply-chain security, and traceability requirements favor US-based final assembly.

The United States also hosts significant R&D activity in advanced laser diode structures, with university laboratories and national research facilities developing next-generation epitaxial designs, though technology transfer to commercial domestic production remains limited by cost competitiveness and scale economics.

Imports, Exports and Trade

The United States is a net importer of Fabry-Perot laser diodes, with import dependence estimated at 60–75% of packaged device consumption. Import patterns reflect the global distribution of epitaxial growth and wafer fabrication capacity, with Asia-Pacific suppliers—particularly those in Japan, South Korea, China, and Taiwan—accounting for an estimated 70–80% of global Fabry-Perot laser diode wafer fabrication. US imports arrive through multiple channels: direct procurement from Asian manufacturers by US OEMs, purchases through authorized distributors with regional inventory hubs, and transfers from foreign subsidiaries of multinational optical component companies. Import lead times for custom devices typically range from 8–16 weeks, while standard catalog items may be available from domestic distribution inventory within days.

US exports of Fabry-Perot laser diodes are comparatively small and concentrated in specialized devices with advanced specifications, defense-related applications, and scientific instruments where US technology leadership justifies premium pricing. Export controls and technology-transfer regulations affect certain high-performance laser diodes with potential dual-use applications, requiring export licenses or compliance reviews that add administrative overhead and delivery lead times.

Tariff treatment for Fabry-Perot laser diodes depends on product classification, country of origin, and applicable trade agreements, with rates varying meaningfully across supplier countries. The trade balance is unlikely to shift dramatically over the forecast horizon, as the economics of wafer-scale epitaxial growth favor Asian production, though US policy incentives for semiconductor manufacturing may gradually support expanded domestic packaging and testing capacity.

Distribution Channels and Buyers

Distribution of Fabry-Perot laser diodes in the United States follows a multi-tier model that reflects the technical complexity and qualification requirements of the product. Authorized distributors—specializing in photonics, optoelectronics, and semiconductor components—maintain inventory of standard catalog devices, provide technical application support, and manage small-to-medium volume orders for US OEMs and research institutions.

Direct manufacturer sales channels serve high-volume customers, defense primes, and applications requiring custom specifications, where engineering collaboration and supply agreements justify the absence of distribution intermediaries. Online marketplaces and specialty electronics distributors also handle lower-complexity purchases, though these channels typically serve prototyping and low-volume production needs rather than high-reliability industrial applications.

Buyer segments in the United States include OEM integrators in industrial automation, datacom equipment manufacturers, semiconductor capital-equipment producers, medical device companies, defense contractors, and university or government research laboratories. Purchasing behavior varies significantly by segment: industrial OEMs prioritize reliability and long-term supply stability, datacom manufacturers emphasize cost and volume scalability, defense buyers require traceability and compliance documentation, and research customers value technical flexibility and small-quantity availability.

Procurement cycles range from spot purchases for prototyping to multi-year supply agreements for production programs, with qualification testing and vendor audits common for critical applications. The US buyer base is geographically dispersed, with concentrations in technology clusters such as Silicon Valley, the Boston photonics corridor, and emerging optical manufacturing hubs in the Southwest and Pacific Northwest.

Regulations and Standards

Regulatory oversight of Fabry-Perot laser diodes in the United States spans laser safety, export control, and environmental compliance frameworks. The Food and Drug Administration (FDA) regulates laser products under 21 CFR Part 1040, requiring manufacturers to classify laser devices by hazard class and comply with labeling, safety interlocks, and emission limits. Fabry-Perot laser diodes integrated into US-manufactured equipment must meet these requirements, with Class 3B and Class 4 devices subject to additional administrative and engineering controls. The Occupational Safety and Health Administration (OSHA) standards for laser hazards in workplaces also influence how US industrial buyers specify and deploy Fabry-Perot laser diode systems, particularly for open-beam applications in manufacturing environments.

Export controls under the International Traffic in Arms Regulations (ITAR) and Export Administration Regulations (EAR) apply to certain high-performance laser diodes with military or dual-use applications, requiring US suppliers and integrators to maintain compliance programs and obtain licenses for controlled exports. Environmental regulations, including the Restriction of Hazardous Substances (RoHS) directive and waste electrical and electronic equipment rules, affect the materials and disposal of laser diode products, though US adoption of these frameworks is less prescriptive than in the European Union.

Industry standards from organizations such as the International Electrotechnical Commission (IEC) and Telcordia provide reliability testing and qualification guidance for telecommunications-grade laser diodes, with US buyers often requiring compliance with these standards even when not legally mandated. Regulatory complexity adds cost and lead time to US market participation but also creates barriers to entry that favor established suppliers with compliance infrastructure.

Market Forecast to 2035

The United States Fabry-Perot laser diodes market is forecast to grow at a 6–9% compound annual rate from 2026 through 2035, with unit demand potentially doubling over the period as industrial automation, semiconductor manufacturing, and optical sensing applications expand. The fastest growth is expected in semiconductor precision manufacturing, where Fabry-Perot laser diodes are integral to wafer inspection, overlay metrology, and process control systems, with 8–12% annual growth driven by US semiconductor fabrication capacity expansion and advanced packaging development.

Industrial automation and instrumentation demand is projected to grow at 5–8% annually, supported by factory modernization, robotics integration, and quality-control automation. Datacom applications will grow more modestly at 3–6% annually as the installed base of short-reach optical links matures and alternative laser architectures capture incremental design wins.

By 2035, premium module and subsystem segments are expected to gain share relative to commodity bare-die components, reflecting the US market’s orientation toward high-reliability, application-specific solutions rather than volume-driven commodity production. Price erosion of 3–5% annually for standard devices will continue, but value-added packaging, wavelength stabilization, and reliability screening will sustain or increase average selling prices in specialized segments.

The import dependence of the US market is unlikely to change dramatically, though policy incentives for domestic semiconductor manufacturing may support modest expansion of US-based packaging, testing, and module assembly capacity. Supply-chain resilience will remain a priority, with US buyers maintaining higher inventory levels and dual-sourcing strategies than was common in the pre-2025 period. The overall market trajectory is positive, with growth driven by the proliferation of optical sensing and measurement technologies across US manufacturing, healthcare, and research sectors.

Market Opportunities

Significant opportunities exist in the United States Fabry-Perot laser diodes market for suppliers that address unmet needs in wavelength diversity, integration, and supply-chain security. The expansion of US semiconductor manufacturing capacity—supported by federal incentives and private investment—creates demand for Fabry-Perot laser diodes in metrology, inspection, and process-control equipment, with opportunities for suppliers that can qualify devices for cleanroom-compatible, high-reliability operation.

The growth of autonomous vehicles, drones, and robotic systems is driving demand for compact, cost-effective optical sensors, where Fabry-Perot laser diodes offer a lower-cost alternative to more complex laser architectures for short-range lidar and proximity sensing. Medical diagnostics and point-of-care testing devices represent another growth area, with Fabry-Perot laser diodes used in flow cytometry, optical coherence tomography, and fluorescence-based assays.

Supply-chain localization presents a strategic opportunity for US-based module integrators and packaging facilities. As US buyers seek to reduce dependence on Asia-Pacific fabrication, domestic assembly and testing capacity that can offer shorter lead times, compliance with US defense and medical regulations, and responsive engineering support will capture premium pricing. Opportunities also exist in the development of higher-power and wavelength-stabilized Fabry-Perot laser diodes for emerging applications in quantum sensing, precision agriculture, and environmental monitoring.

Suppliers that invest in reliability data generation, extended lifetime testing, and application-specific qualification support will differentiate themselves in a market where technical credibility and long-term supply assurance are valued more highly than low initial cost. The convergence of industrial digitalization and optical sensing across US manufacturing creates sustained demand for Fabry-Perot laser diodes as a cost-effective, proven optical source technology.

Free Training

Source link

U.S. Hails Hyundai Steel, POSCO Mill in Louisiana


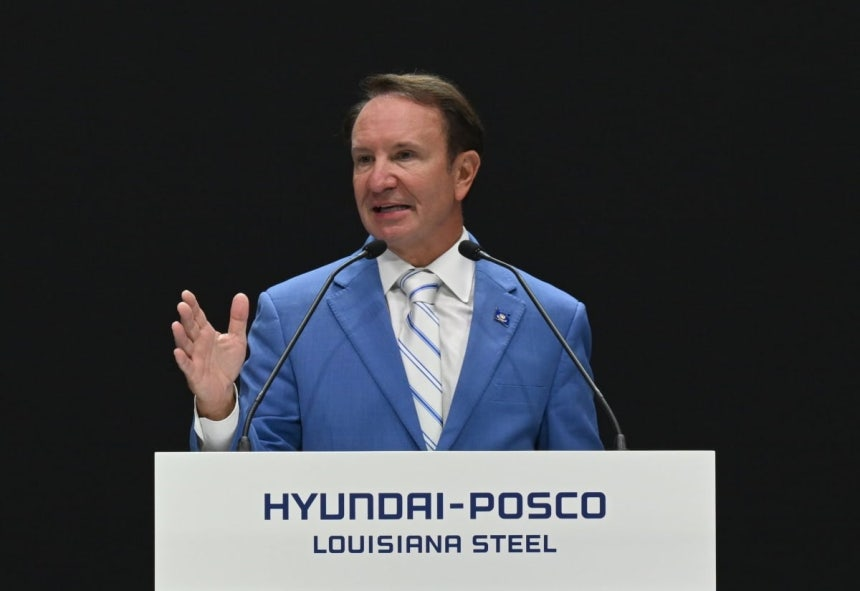
Louisiana Governor Jeff Landry speaks at the groundbreaking ceremony for the Hyundai Steel-POSCO Louisiana Steel (HPLS) electric arc furnace mill on Sept. 4 local time. Courtesy of Hyundai Motor Group - Seoul Economic Daily Finance News from South KoreaLouisiana Governor Jeff Landry speaks at the groundbreaking ceremony for the Hyundai Steel-POSCO Louisiana Steel (HPLS) electric arc furnace mill on Sept. 4 local time. Courtesy of Hyundai Motor Group

Federal and state officials in the United States welcomed the decision by Hyundai Steel (004020) and POSCO to build their first integrated steel mill in the country, calling the project a milestone as Washington works to rebuild its manufacturing base. One official said a country that cannot produce steel cannot be a great power.

Louisiana Gov. Jeff Landry, speaking on the 4th at the groundbreaking ceremony for the Hyundai Steel-POSCO Louisiana electric arc furnace steel mill, known as HPLS, said he had watched manufacturing leave the United States. The first thing the Donald Trump administration pursued was bringing manufacturing back to the United States, he said.

“This is about creating high-wage jobs in America and creating new opportunities in Louisiana in particular,” he said, adding that steel is the core and the foundation of U.S. manufacturing. Expanding domestic steel capacity is needed to ensure a stable supply of materials for major manufacturing industries including autos, machinery and construction, he said.

That is why the Louisiana mill is seen as aligning with the U.S. push to rebuild manufacturing. The United States is a major steel producer but cannot meet demand from domestic output alone. Its crude steel production last year was 82 million tons, according to the World Steel Association, and the country imports more than 20 million tons of steel annually.

The U.S. Commerce Department also praised the investment by Hyundai Steel and POSCO. William Kimmitt, under secretary of commerce for international trade, said the same day that a country that cannot produce steel cannot be a great power and cannot build a strong auto industry. Countries should not depend on others for the basic materials that underpin key industries, he said.

Policy alone cannot build a steel mill, Kimmitt said, adding that companies with the actual ability to invest are needed. Hyundai Steel and POSCO are the companies taking on exactly that role, he said.

Free Training

Source link

US manufacturing jobs rise 16,000 in August labour report


The US labour market added 162,000 nonfarm payroll jobs in August, while the unemployment rate was unchanged at 4.1 per cent, official data for September 4, 2026 showed, giving apparel and textile sourcing teams a fresh read on factory hiring, construction-linked capacity and wage pressure in a key consumer and supply market.

Manufacturing employment continued its upward trend with 16,000 jobs added in August and was up by 58,000 from a recent low in December 2025. Machinery manufacturing and fabricated metal product manufacturing each continued to trend up, adding 6,000 jobs, while construction changed little at 22,000 jobs added.

The US Bureau of Labor Statistics (BLS) said total nonfarm payroll gains in August were above the average monthly increase of 31,000 over the prior 12 months. Employment rose in food services and drinking places and local government education, while the information industry lost jobs.

US nonfarm payrolls rose by 162,000 in August, with manufacturing adding 16,000 jobs and construction up 22,000.
The unemployment rate held at 4.1 per cent, while labour force participation edged up to 61.6 per cent and part-time for economic reasons fell.
Average hourly earnings rose to $37.75, a wage signal for apparel and retail sourcing teams tracking US labour costs.

The BLS said the release draws on two monthly surveys: the household survey, which measures labour force status including unemployment by demographic characteristics, and the establishment survey, which measures nonfarm employment, hours and earnings by industry.

In the household survey, the number of unemployed people was little changed at 7.0 million. The unemployment rate for Asian workers declined to 3.2 per cent, the teenage rate edged up to 14.1 per cent, and jobless rates showed little change for adult men at 4.0 per cent, adult women at 3.5 per cent, White workers at 3.7 per cent, Black workers at 6.0 per cent and Hispanic workers at 4.8 per cent.

The number of long-term unemployed, defined as people jobless for 27 weeks or more, changed little at 1.9 million and accounted for 27.0 per cent of all unemployed people. The labour force participation rate edged up to 61.6 per cent but was down by 0.5 percentage point since January, while the employment-population ratio changed little at 59.1 per cent.

The number of people employed part time for economic reasons decreased by 414,000 to 4.4 million. The number of people not in the labour force who wanted a job changed little at 5.7 million; amongst them, 1.7 million were marginally attached to the labour force and 441,000 discouraged workers believed no jobs were available for them.

Employment showed little change in mining, quarrying, and oil and gas extraction; wholesale trade; retail trade; transportation and warehousing; financial activities; professional and business services; social assistance; and other services.

Average hourly earnings for all employees on private nonfarm payrolls rose by 10 cents, or 0.3 per cent, to $37.75 in August, and were up by 3.1 per cent over the year. Average hourly earnings of private-sector production and nonsupervisory employees rose by 11 cents, or 0.3 per cent, to $32.53.

The average workweek for all employees on private nonfarm payrolls edged up by 0.1 hour to 34.4 hours. In manufacturing, the average workweek edged up by 0.1 hour to 40.5 hours, while overtime was unchanged at 3.1 hours.

In a White House statement, spokesman Kush Desai said the US added 162,000 jobs in August, described as nearly triple economists’ expectations, and that the private sector had created more than one million jobs in President Donald J Trump’s second term.

The White House said federal employment remained at its lowest share of the workforce on record.

The White House also characterised the 16,000 manufacturing gain as the strongest monthly increase in three years and said manufacturers had added 58,000 jobs this year, driven by demand for pharmaceutical and defence production, data centre construction and semiconductor plants. It said factory construction jobs were up nearly 100,000 in President Trump’s second term and that private-sector workers’ average weekly earnings were up 3.7 per cent over the year.

The White House added that the labour force participation increased at its strongest level in almost a year, college graduate unemployment remained at 2.7 per cent, and Black unemployment posted a second monthly decline.

Fibre2Fashion News Desk (CG)

Free Training

Source link

Hyundai Steel Celebrates Louisiana EAF Steel Mill Project Launch, Driving Growth for U.S. Manufacturing | Prnewswire


State

AlabamaAlaskaArizonaArkansasCaliforniaColoradoConnecticutDelawareFloridaGeorgiaHawaiiIdahoIllinoisIndianaIowaKansasKentuckyLouisianaMaineMarylandMassachusettsMichiganMinnesotaMississippiMissouriMontanaNebraskaNevadaNew HampshireNew JerseyNew MexicoNew YorkNorth CarolinaNorth DakotaOhioOklahomaOregonPennsylvaniaRhode IslandSouth CarolinaSouth DakotaTennesseeTexasUtahVermontVirginiaWashingtonWashington D.C.West VirginiaWisconsinWyomingPuerto RicoUS Virgin IslandsArmed Forces AmericasArmed Forces PacificArmed Forces EuropeNorthern Mariana IslandsMarshall IslandsAmerican SamoaFederated States of MicronesiaGuamPalauAlberta, CanadaBritish Columbia, CanadaManitoba, CanadaNew Brunswick, CanadaNewfoundland, CanadaNova Scotia, CanadaNorthwest Territories, CanadaNunavut, CanadaOntario, CanadaPrince Edward Island, CanadaQuebec, CanadaSaskatchewan, CanadaYukon Territory, Canada

Zip Code

Country

United States of AmericaUS Virgin IslandsUnited States Minor Outlying IslandsCanadaMexico, United Mexican StatesBahamas, Commonwealth of theCuba, Republic ofDominican RepublicHaiti, Republic ofJamaicaAfghanistanAlbania, People’s Socialist Republic ofAlgeria, People’s Democratic Republic ofAmerican SamoaAndorra, Principality ofAngola, Republic ofAnguillaAntarctica (the territory South of 60 deg S)Antigua and BarbudaArgentina, Argentine RepublicArmeniaArubaAustralia, Commonwealth ofAustria, Republic ofAzerbaijan, Republic ofBahrain, Kingdom ofBangladesh, People’s Republic ofBarbadosBelarusBelgium, Kingdom ofBelizeBenin, People’s Republic ofBermudaBhutan, Kingdom ofBolivia, Republic ofBosnia and HerzegovinaBotswana, Republic ofBouvet Island (Bouvetoya)Brazil, Federative Republic ofBritish Indian Ocean Territory (Chagos Archipelago)British Virgin IslandsBrunei DarussalamBulgaria, People’s Republic ofBurkina FasoBurundi, Republic ofCambodia, Kingdom ofCameroon, United Republic ofCape Verde, Republic ofCayman IslandsCentral African RepublicChad, Republic ofChile, Republic ofChina, People’s Republic ofChristmas IslandCocos (Keeling) IslandsColombia, Republic ofComoros, Union of theCongo, Democratic Republic ofCongo, People’s Republic ofCook IslandsCosta Rica, Republic ofCote D’Ivoire, Ivory Coast, Republic of theCyprus, Republic ofCzech RepublicDenmark, Kingdom ofDjibouti, Republic ofDominica, Commonwealth ofEcuador, Republic ofEgypt, Arab Republic ofEl Salvador, Republic ofEquatorial Guinea, Republic ofEritreaEstoniaEthiopiaFaeroe IslandsFalkland Islands (Malvinas)Fiji, Republic of the Fiji IslandsFinland, Republic ofFrance, French RepublicFrench GuianaFrench PolynesiaFrench Southern TerritoriesGabon, Gabonese RepublicGambia, Republic of theGeorgiaGermanyGhana, Republic ofGibraltarGreece, Hellenic RepublicGreenlandGrenadaGuadaloupeGuamGuatemala, Republic ofGuinea, Revolutionary
People’s Rep’c ofGuinea-Bissau, Republic ofGuyana, Republic ofHeard and McDonald IslandsHoly See (Vatican City State)Honduras, Republic ofHong Kong, Special Administrative Region of ChinaHrvatska (Croatia)Hungary, Hungarian People’s RepublicIceland, Republic ofIndia, Republic ofIndonesia, Republic ofIran, Islamic Republic ofIraq, Republic ofIrelandIsrael, State ofItaly, Italian RepublicJapanJordan, Hashemite Kingdom ofKazakhstan, Republic ofKenya, Republic ofKiribati, Republic ofKorea, Democratic People’s Republic ofKorea, Republic ofKuwait, State ofKyrgyz RepublicLao People’s Democratic RepublicLatviaLebanon, Lebanese RepublicLesotho, Kingdom ofLiberia, Republic ofLibyan Arab JamahiriyaLiechtenstein, Principality ofLithuaniaLuxembourg, Grand Duchy ofMacao, Special Administrative Region of ChinaMacedonia, the former Yugoslav Republic ofMadagascar, Republic ofMalawi, Republic ofMalaysiaMaldives, Republic ofMali, Republic ofMalta, Republic ofMarshall IslandsMartiniqueMauritania, Islamic Republic ofMauritiusMayotteMicronesia, Federated States ofMoldova, Republic ofMonaco, Principality ofMongolia, Mongolian People’s RepublicMontserratMorocco, Kingdom ofMozambique, People’s Republic ofMyanmarNamibiaNauru, Republic ofNepal, Kingdom ofNetherlands AntillesNetherlands, Kingdom of theNew CaledoniaNew ZealandNicaragua, Republic ofNiger, Republic of theNigeria, Federal Republic ofNiue, Republic ofNorfolk IslandNorthern Mariana IslandsNorway, Kingdom ofOman, Sultanate ofPakistan, Islamic Republic ofPalauPalestinian Territory, OccupiedPanama, Republic ofPapua New GuineaParaguay, Republic ofPeru, Republic ofPhilippines, Republic of thePitcairn IslandPoland, Polish People’s RepublicPortugal, Portuguese RepublicPuerto RicoQatar, State ofReunionRomania, Socialist Republic ofRussian FederationRwanda, Rwandese RepublicSamoa, Independent State ofSan Marino, Republic ofSao Tome and Principe, Democratic Republic ofSaudi Arabia, Kingdom ofSenegal, Republic ofSerbia and MontenegroSeychelles, Republic ofSierra Leone, Republic ofSingapore, Republic ofSlovakia (Slovak Republic)SloveniaSolomon IslandsSomalia, Somali RepublicSouth Africa, Republic ofSouth Georgia and the South Sandwich IslandsSpain, Spanish StateSri Lanka, Democratic Socialist Republic ofSt. HelenaSt. Kitts and NevisSt. LuciaSt. Pierre and MiquelonSt. Vincent and the GrenadinesSudan, Democratic Republic of theSuriname, Republic ofSvalbard & Jan Mayen IslandsSwaziland, Kingdom ofSweden, Kingdom ofSwitzerland, Swiss ConfederationSyrian Arab RepublicTaiwan, Province of ChinaTajikistanTanzania, United Republic ofThailand, Kingdom ofTimor-Leste, Democratic Republic ofTogo, Togolese RepublicTokelau (Tokelau Islands)Tonga, Kingdom ofTrinidad and Tobago, Republic ofTunisia, Republic ofTurkey, Republic ofTurkmenistanTurks and Caicos IslandsTuvaluUganda, Republic ofUkraineUnited Arab EmiratesUnited Kingdom of Great Britain & N. IrelandUruguay, Eastern Republic ofUzbekistanVanuatuVenezuela, Bolivarian Republic ofViet Nam, Socialist Republic ofWallis and Futuna IslandsWestern SaharaYemenZambia, Republic ofZimbabwe

Free Training

Source link

Hyundai Steel Celebrates Louisiana EAF Steel Mill Project Launch, Driving Growth for U.S. Manufacturing


  • $5.8 billion investment part of Hyundai Motor Group’s $26 billion U.S. commitment, strengthening local supply chain and industrial resilience
  • Commercial production to begin in 2029 with 2.7 million metric tons annual capacity, supporting 5,400 jobs including 1,300 direct employments
  • First Electric Arc Furnace-based integrated steel mill in the U.S., leveraging advanced technologies including Direct Reduction Process
  • Supplying high-quality, low-carbon emissions steel to global automakers including Hyundai Motor and Kia

SEOUL, South Korea and ASCENSION PARISH, La., Sept. 5, 2026 /PRNewswire/ — Hyundai Steel Company held a ceremonial event today for a $5.8 billion Electric Arc Furnace-based integrated steel mill in Louisiana, the first of its kind in North America, marking a pivotal moment in strengthening U.S. manufacturing resurgence.

(From left) Gang Hyun Seo, Hyundai Motor Group President; Kwang-moo Kim, Senior Executive Vice President; Leroy Sullivan, Mayor of Donalsonville; José Muñoz, President and CEO of Hyundai Motor Company; Susan Bourgeois, Louisiana Economic Development Secretary; Julia Letlow, U.S. Representative; Kyung-wha Kang, South Korean Ambassador to the U.S.; In-hwa Chang, POSCO Group Chairman; Jeff Landry, Louisiana Governor; Euisun Chung, Hyundai Motor Group Executive Chair; Troy Carter, U.S. Representative; Jung-kwan Kim, Korea’s Minister of Trade, Industry and Resources; William Kimmitt, U.S. Under Secretary of Commerce for International Trade; Bo-Ryong Lee, President and CEO of Hyundai Steel; Clint Cointment, Ascension Parish President; Ho Sung Song, President and CEO of Kia Corporation; Sung Kim, Hyundai Motor Group President; Cortaz Johnson, Student of River Parishes Community College (RPCC)

Under the slogan of “Building the Future of Steel, Together with Louisiana,” the ceremonial event took place at the RiverPlex MegaPark in Ascension Parish, Louisiana. The new mill will be operated by HYUNDAI-POSCO Louisiana Steel LLC (HPLS), a joint venture between Hyundai Steel, POSCO, Hyundai Motor Company and Kia Corporation.

The $5.8 billion investment establishes the first North American steel production base for Hyundai Steel, Hyundai Motor Group’s steelmaking arm. With commercial production targeted for 2029, the mill will have an annual capacity of 2.7 million metric tons of hot-rolled and cold-rolled steel sheets, primarily for automotive applications, and is expected to create 5,400 jobs, including 1,300 direct positions.

“As America strengthens its manufacturing leadership, steel will continue to power the next chapter of its industrial resurgence,” said Hyundai Motor Group Executive Chair Euisun Chung. “We are proud to contribute to that vision and to the future of ‘Made in America’. Together, we will turn our shared ambitions into greater productivity and prosperity.”

Advancing Hyundai Motor Group’s Commitment to U.S. Manufacturing

The Louisiana steel mill is a cornerstone of Hyundai Motor Group’s $26 billion U.S. investment commitment through 2028, announced in 2025. This strategic initiative represents Hyundai Motor Group’s significant expansion in the U.S. spanning automotive production, advanced steelmaking, robotics innovation, and other key sectors—establishing a fully integrated ecosystem expanding the U.S. manufacturing footprint and mobility value chain. Since entering the U.S. market in 1986, Hyundai Motor Group has invested more than $20.5 billion.

About Hyundai Steel

More information about Hyundai Steel, please see: https://hyundai-steel.com/en

About HYUNDAI-POSCO Louisiana Steel (HPLS)

More information about HPLS can be found at: https://www.linkedin.com/company/hyundai-posco-louisiana-steel/

About Hyundai Motor Group
More information about Hyundai Motor Group can be found at: http://www.hyundaimotorgroup.com or Newsroom: Media Hub by Hyundai, Kia Global Newsroom, Genesis Newsroom


This article was produced by Cision PR Newswire, our trusted news partner. The views expressed and the content presented here are solely those of the author and may not fully reflect the opinions of Thailand Business News.
Read the original article : Hyundai Steel Celebrates Louisiana EAF Steel Mill Project Launch, Driving Growth for U.S. Manufacturing

Free Training

Source link